Profitability tells you whether a company's revenue exceeds its costs over a period. Cash flow tells you how much actual cash moved in and out of the business. A company can post a healthy profit and still run short of cash, or report a loss and still generate cash. For a stock investor, the useful question is not which one matters more. It is whether the two numbers tell the same story, and if they don't, why.
TL;DR
- Profit is an accounting measure built on accrual rules. Cash flow tracks real cash receipts and payments.
- The gap between them comes from timing (credit sales, inventory, prepaid costs), non-cash charges like depreciation, and financing such as loans.
- Free cash flow, usually operating cash flow minus capital spending, shows what is left for owners after the business reinvests. Its definition varies, so check how each source calculates it.
- Single-year free cash flow is noisier than earnings. Use both, over several years, rather than picking one.
- Persistent gaps between earnings and operating cash flow are the first thing to investigate in a 10-K.
Table of Contents
- The core difference in plain terms
- Why profit is not the same as cash
- The three buckets of the cash-flow statement
- How a profitable company runs out of cash
- How a company with a loss can still generate cash
- Free cash flow: the bridge between the two
- Which matters more: profit or cash flow?
- Warning signs worth checking
- Where to find the numbers
- Putting profit and cash flow together in one view
- Our perspective
- Compare profitability and financial health side by side
- FAQ
- Sources
The core difference in plain terms
Profit is what remains after revenues and operating expenses are accounted for. Cash flow is the net balance of cash moving into and out of a business, according to Harvard Business School Online. Both come from the same company, but they answer different questions.
- Profitability asks: did the company earn more than it spent to produce its sales this period?
- Cash flow asks: did more cash come in than went out, and from which activities?
The first is about economic performance. The second is about liquidity and the company's ability to pay bills, fund growth, service debt and reward shareholders. A stock can look cheap on one and expensive on the other, which is why serious analysts read both.
Why profit is not the same as cash
The main reason is accrual accounting. U.S. financial statements record revenue and expenses when they are earned or incurred, not necessarily when cash changes hands. The Financial Accounting Standards Board (FASB) describes accrual accounting as recording the financial effects of transactions in the periods they occur, rather than only when cash is received or paid. The cash-flow statement then reports cash receipts and payments separately and reconciles them with earnings.
In practice, OpenStax explains that an accrual-based income statement can record revenue before the customer pays and record an expense before the company pays it. The cash-flow statement exists to bridge that difference.
Three everyday examples show how this plays out:
- Credit sales. A company ships $10 million of product in December and books the revenue. The customers pay in February. Profit rises in December, cash arrives later.
- Inventory build. A retailer buys $5 million of extra stock ahead of a season. Nothing hits the income statement until the goods sell, but the cash is gone now.
- Prepaid or capitalized costs. A company pays three years of software or insurance upfront. Cash drops immediately, while the expense is spread over time.
None of these is wrong or deceptive. They are the normal mechanics of accrual accounting. The risk comes when the gap keeps growing year after year.
The three buckets of the cash-flow statement
To compare profit with cash, you need to know where the cash came from. The cash-flow statement sorts it into three categories, which both HBS Online and OpenStax describe:
| Category | What it covers | What an investor should look for |
|---|---|---|
| Operating | Cash from the activities that produce net income | Whether it tracks or exceeds net income over time |
| Investing | Purchases and sales of long-term assets and other investments | Capital spending levels, acquisitions, asset sales |
| Financing | Debt and equity issuance, repayments, dividends and share repurchases | Whether cash is coming from customers or from lenders and new shareholders |
FASB's cash-flow reporting standard uses the same three classes and allows the indirect method, which starts from net income and adjusts it to arrive at operating cash flow. Most public companies use it, so when you open a cash-flow statement, the first lines are usually net income followed by the adjustments that explain the difference.
The distinction between operating and financing cash is the one that trips up beginners. A company can show a pile of new cash at year-end because it borrowed, not because the business earned it.
How a profitable company runs out of cash
The University of Minnesota's FINPACK guide points to several causes: large loan payments, owner withdrawals and cash-timing differences. One detail matters a lot for investors. Loan principal payments reduce cash but are not income-statement expenses, while depreciation is an expense that may not line up with the principal payments.
Here is a simplified illustration. The numbers are invented to show the mechanics, not drawn from a real company.
| Year 1 | |
|---|---|
| Revenue | $100 |
| Operating costs (cash) | $70 |
| Depreciation | $10 |
| Net profit (ignoring interest and tax) | $20 |
| Increase in receivables (customers haven't paid) | $15 |
| Equipment purchased | $25 |
| Loan principal repaid | $10 |
The income statement shows $20 of profit. Cash tells a different story. Start with the $20 profit, add back $10 of non-cash depreciation, subtract the $15 of sales not yet collected: operating cash flow is $15. Subtract $25 of equipment and the free cash flow is negative $10. Repaying $10 of principal leaves the company $20 short, even though it "made money."
The company in this example is not necessarily in trouble. It may be growing fast and funding that growth. But an investor who looked only at profit would miss that it needs outside financing to keep going.
How a company with a loss can still generate cash
The reverse also happens. Investopedia explains that depreciation reduces net income but is not a cash outlay, so it is added back when computing cash flow indirectly. That alone can turn a reported loss into positive operating cash flow for asset-heavy businesses.
Borrowing is the other path, and it is the one to be wary of. The same article notes that JC Penney reported a $78 million loss and a positive $181 million cash position in the second quarter of 2018, with borrowing helping supply the cash. Cash on the balance sheet is only reassuring if you know where it came from. Cash from operations is sustainable. Cash from new debt is a bill that arrives later.
Free cash flow: the bridge between the two
Free cash flow (FCF) is the number most investors reach for when they want to know what a business really earns for its owners. It sits between profit and raw cash flow.
A common definition, as Investopedia describes it, is cash flow from operations minus the capital expenditures required to maintain current production capacity. Because companies rarely disclose how much of their capital spending is maintenance, analysts often subtract total capital expenditures or estimate the maintenance portion. The result is only as good as that estimate. Free cash flow shows financial flexibility after capital spending, but its usefulness depends on whether the capital-expenditure figure reflects what the business needs to stand still.

So, are free cash flow and profit the same thing? No. NYU's Aswath Damodaran notes that adding depreciation back to earnings is, at best, an intermediate step toward free cash flow, and that the measure can be defined inconsistently. When you compare FCF across data providers or articles, confirm each one subtracts the same things.
For a deeper walk-through, see our guide to free cash flow for smarter investing, and our FCF conversion bridge for moving from EBITDA to free cash flow step by step.
Which matters more: profit or cash flow?
Neither wins outright. They work on different time horizons and fail in different ways.
- Profit is the better guide to long-run earning power. It smooths lumpy items such as a big equipment purchase across the years the equipment is used.
- Cash flow is the better guide to survival and flexibility. A company that cannot pay suppliers, lenders or payroll is in trouble no matter what its income statement says.
Damodaran adds an important caution for stock analysis. A single year of free cash flow is noisier and less informative about operating health than a single year of earnings. His suggestion is to use free cash flow to augment rather than automatically replace earnings-based pricing measures. He also says historical FCF helps explain what a company did in the past and can serve as a base for forecasting, but it is more volatile than earnings.
In practice that means:
- Look at three to five years of both, not one.
- Compare operating cash flow with net income each year. A healthy business tends to convert earnings into cash over time.
- Treat a one-year dip in FCF from a big investment differently from a decade of FCF that never catches up with profit.
Warning signs worth checking
These patterns do not prove anything on their own. They are prompts to read further.
- Net income keeps rising while operating cash flow stays flat or falls. Receivables or inventory may be growing faster than sales. Our piece on the accruals ratio shows one way to measure this gap.
- Cash increases only in the financing section. The business may be funding itself with debt or share issuance.
- Free cash flow is persistently negative in a mature company. Growth companies can justify negative FCF for a while. A mature one usually can't.
- Capital spending far below depreciation for years. The company may be under-investing, which flatters FCF today at the cost of tomorrow.
- Large one-time items such as asset sales or working-capital swings that inflate a single year.
For a broader framework, our earnings quality analysis and financial health analysis guides go through the checks in more detail.
Where to find the numbers
You do not need a paid terminal. The U.S. Securities and Exchange Commission's investor site explains that the Form 10-K includes audited income statements, balance sheets, statements of cash flows and notes. The management discussion and analysis (MD&A) in 10-Ks and 10-Qs covers results, liquidity, capital resources, known trends or uncertainties and critical accounting judgments.
All of it is free on EDGAR: 10-Ks hold the audited annual statements, 10-Qs the quarterly ones, and 8-Ks disclose material events.
A practical reading order:
- Start with the income statement for revenue, operating income and net income. Mercer Capital notes that operating income (EBIT) is unaffected by financing sources, which makes operating margin useful for comparing efficiency across companies. Our income statement checklist covers this step.
- Move to the cash-flow statement and compare operating cash flow with net income.
- Check capital expenditures in the investing section, then compute free cash flow.
- Read the financing section to see whether debt or share issuance is plugging gaps.
- Read the MD&A liquidity discussion. The SEC also advises investors to weigh audit qualifications and disclosed material weaknesses in internal controls.
Liquidity discussions are also where you see how management thinks about funding. Some large shareholders, for example, are equity rich and cash poor and look for ways to raise cash without selling shares. That is a different problem from a company's own cash flow, but it is a reminder that paper wealth and spendable cash are never the same thing.
Putting profit and cash flow together in one view
A simple routine for any stock:
| Check | Question | Healthy pattern |
|---|---|---|
| Profit trend | Are operating income and margins stable or rising? | Steady or improving over several years |
| Cash conversion | Is operating cash flow close to or above net income? | Roughly in line over multiple years |
| Free cash flow | Is there cash left after reinvestment? | Positive, or negative for a clear growth reason |
| Funding source | Is cash coming from operations? | Operating section does the heavy lifting |
| Valuation | What price are you paying for earnings and for FCF? | Reasonable on both |
Once you have free cash flow figures, they feed valuation work such as discounted cash flow analysis and Warren Buffett's owner earnings approach, which is built on the same idea: what the business really leaves for its owners. If you want the whole process in order, our 10-step fundamental analysis checklist ties these checks together.
Our perspective
We built Oracle Investments because we saw the same pattern again and again: investors either trust a single headline number or drown in spreadsheets. Profit and cash flow are a good example. Each one is easy to misread alone, and comparing them for 260 companies by hand takes hours.
Our view is that a stock score should be rule-based and grounded in reported company fundamentals, with every input visible. If a company scores well on profitability but poorly on financial health, you should be able to see why in seconds, without trusting a black box. The value investors we learn from, Buffett, Munger and Lynch, all returned to the same idea: understand what the business actually earns and what it actually keeps. Profit shows the first, cash flow shows the second, and the gap between them is where good questions start.
We would also add a note of humility. No ratio replaces reading the filing. Use scores to narrow the field, then check the cash-flow statement of the companies that make your shortlist.
— Matt
Compare profitability and financial health side by side
If you would rather not rebuild these comparisons in a spreadsheet every time, Oracle Investments scores over 260 stocks on profitability, valuation and financial health, and lets you compare companies side by side with the scoring inputs shown. The app is available as a Premium Annual subscription through the Apple App Store, with real-time portfolio tracking and educational content from legendary value investors.
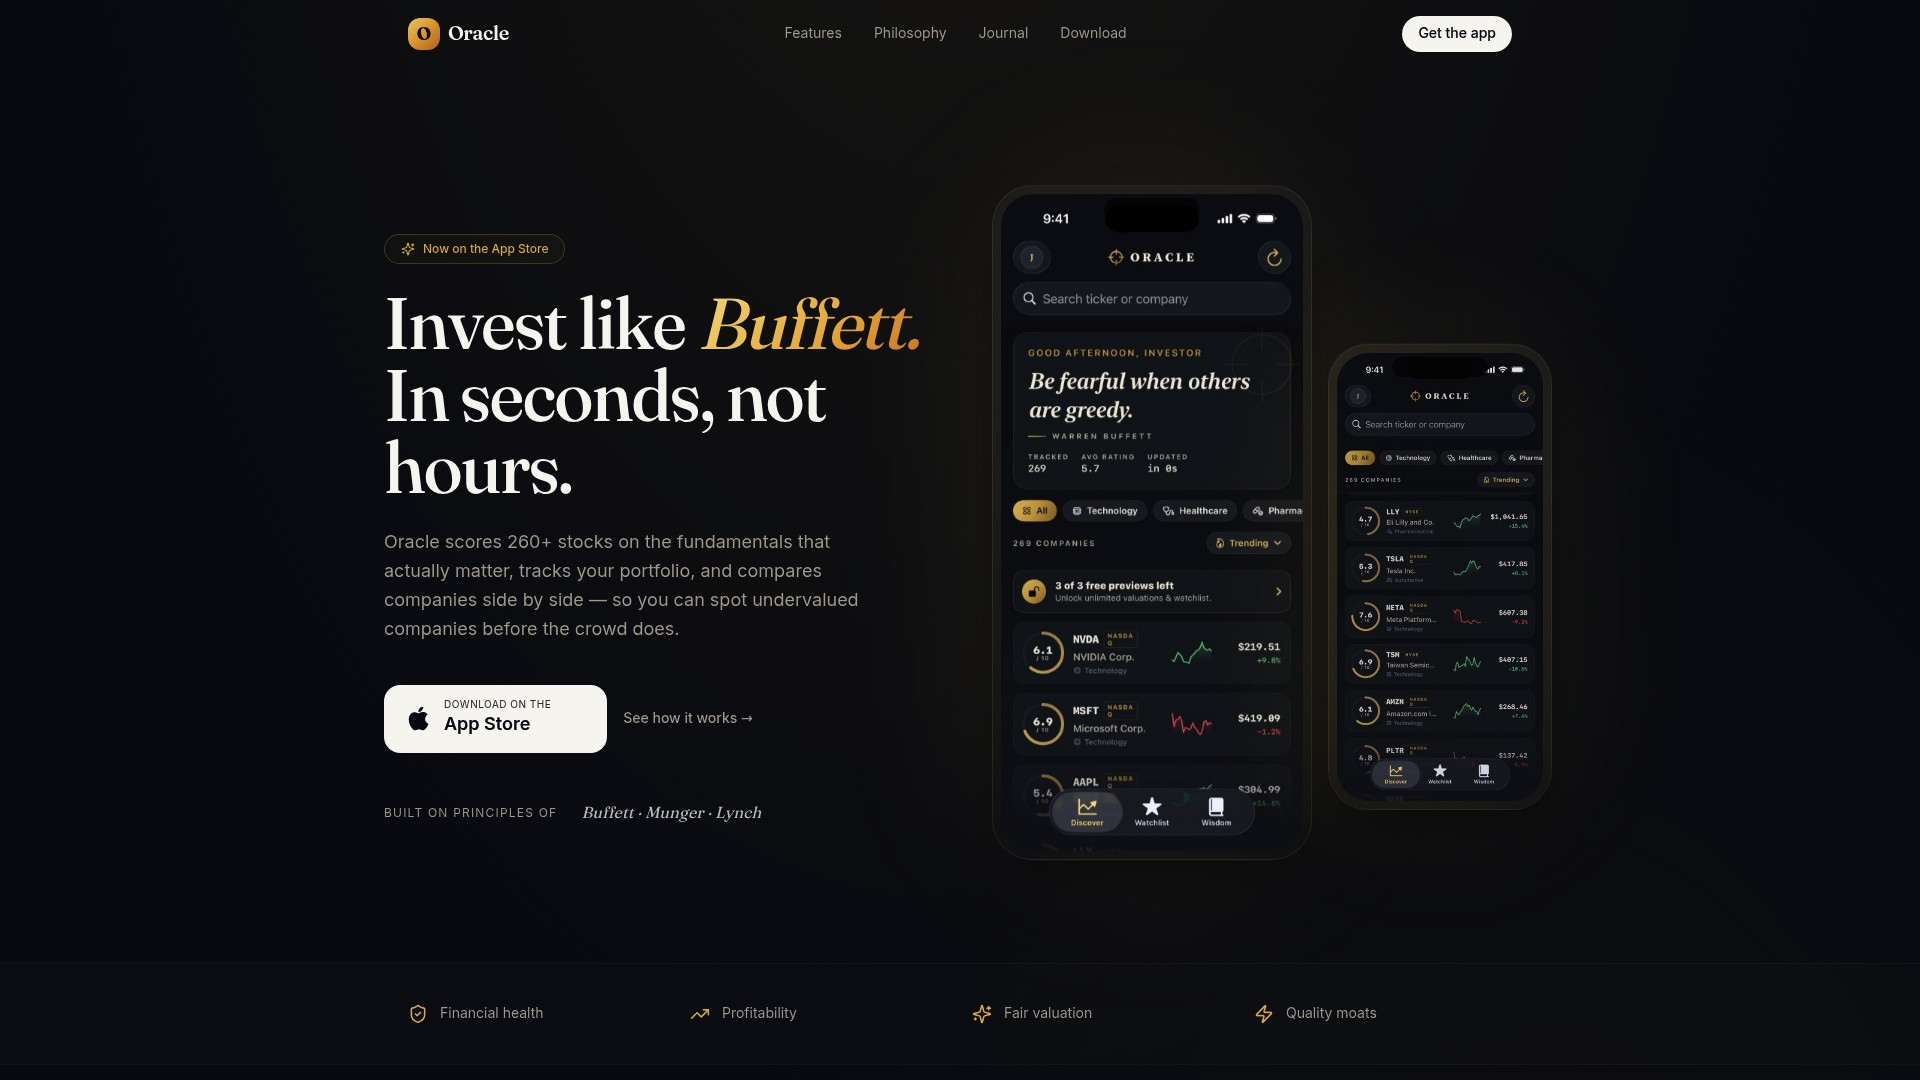
See Oracle Investments Premium Annual and spot the companies where profit and cash tell different stories.
FAQ
What is the difference between profit and cash flow?
Profit is what remains after revenues and operating expenses are accounted for, using accrual rules. Cash flow is the net movement of cash into and out of the business. Profit measures performance over a period, while cash flow shows whether the company has money to pay its obligations.
Is profit more important than cash flow?
It depends on the question. Profit is a better guide to long-run earning power, and cash flow is a better guide to short-term liquidity. Single-year free cash flow is noisier than earnings, so investors do best using both over several years.
Are free cash flow and profit the same thing?
No. Free cash flow is generally operating cash flow minus capital expenditures, so it reflects cash left after reinvestment. Profit includes non-cash items like depreciation and ignores timing differences in collections and payments. Definitions of free cash flow also vary, so check how each source calculates it.
Why is profit not the same as cash?
Because U.S. companies use accrual accounting, which records revenue when earned and expenses when incurred, not when cash moves. Credit sales, inventory purchases, depreciation and loan repayments all create gaps. The cash-flow statement reconciles net income to actual cash.
Can a company have negative cash flow and still be profitable?
Yes. Fast growth that ties up cash in receivables, inventory or equipment, or heavy loan repayments, can leave a profitable company short of cash. The reverse is also possible: depreciation or borrowing can produce positive cash despite a loss.
Sources
- Cash Flow vs. Profit: What's the Difference? (HBS Online)
- Differentiate between Operating, Investing, and Financing Activities (OpenStax)
- What Is "Profit" versus "Loss" for the Company? (OpenStax)
- Profitability vs Cash Flow (University of Minnesota FINPACK)
- Is It Possible to Have Positive Cash Flow and Negative Net Income? (Investopedia)
- How to Evaluate a Statement of Cash Flows (Investopedia)
- Earnings and Cash Flows: A Primer on Free Cash Flows (Aswath Damodaran)
- FASB Concepts Statement No. 5
- Summary of FASB Statement No. 95
- How to Read a 10-K/10-Q (Investor.gov)
- Using EDGAR to Research Investments (Investor.gov)
- Basics of Financial Statement Analysis (Mercer Capital)
- Equity Rich, Cash Poor: How Shareholders Unlock Liquidity