The accruals ratio measures how much of a company's reported profit is not backed by actual cash from operations. The formula is simple: (net income minus operating cash flow) divided by average total assets. A negative or near-zero number is usually a good sign.
TL;DR:
- An accruals ratio above 10% typically warrants closer examination of receivables and inventory growth relative to sales.
- Using the full Sloan formula helps filter out capex and acquisition effects, especially for capital-intensive or growing companies.
- The ratio's usefulness is limited for financial firms and can be misleading during seasonal or depreciation-driven inventory or deferred revenue shifts.
- A three to five year increasing trend in the accruals ratio indicates declining earnings quality, rather than a single-quarter spike.
- Comparing accruals ratios within industry peers and along with other cash flow metrics improves the accuracy of earnings quality assessments.
Table of Contents
- What Is the Accruals Ratio and Where Did It Come From?
- How to Calculate the Accruals Ratio Step by Step
- Operating-Only vs. Full Sloan: Which Formula Should You Use?
- What Counts as a Normal Accruals Ratio?
- How Investors Actually Use the Accruals Ratio
- Where the Accruals Ratio Falls Short
- A Worked Example: Calculating the Accruals Ratio From Scratch
- How Oracle Investments Applies the Accruals Ratio in Stock Scoring
- A Quick Checklist for Students and Analysts
- Track Accruals Trends Without Building a Spreadsheet Every Quarter
- Sources
What Is the Accruals Ratio and Where Did It Come From?
Accruals are the non-cash pieces of an income statement: money booked as revenue before cash arrives (receivables), inventory sitting on shelves, prepaid expenses, deferred costs. Accrual accounting requires companies to record revenue and expenses when they're earned or incurred, not when cash actually changes hands. That timing mismatch is normal. Every company has some gap between net income and operating cash flow.
The problem starts when that gap grows large and stays large. Richard Sloan, in a 1996 study published in The Accounting Review, found that firms with high accruals relative to their cash flow tended to see weaker stock returns over the following one to two years, while firms with low or negative accruals tended to outperform. His work became known as the accrual anomaly, and it's the reason this ratio carries his name in practice: the Sloan ratio.
Here's the important caveat: a high accruals ratio is a flag, not a verdict. It tells you to look closer, not that something is wrong.
How to Calculate the Accruals Ratio Step by Step
You need four numbers, all pulled straight from a company's filings: net income, cash flow from operations, and total assets at the start and end of the period. Optionally, cash flow from investing if you want the fuller version covered in the next section.
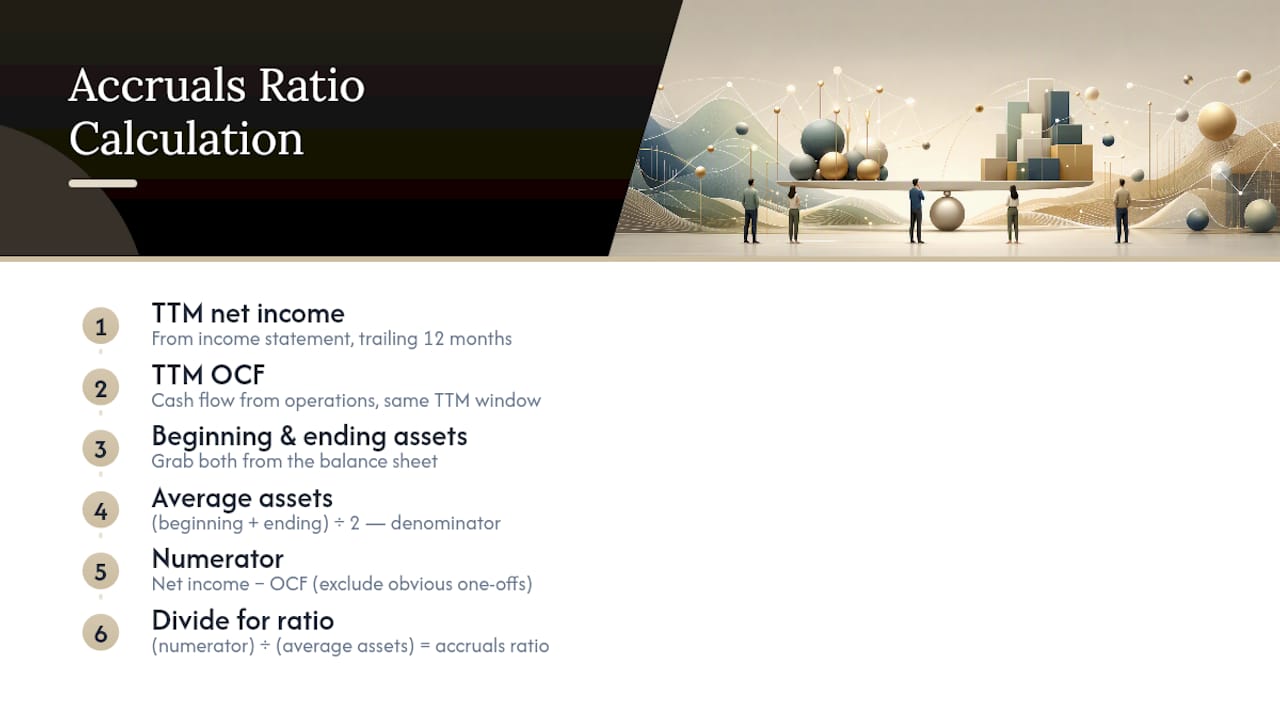
Here's the workflow:
Pull trailing twelve months (TTM) net income from the income statement rather than a single quarter, which smooths out seasonal noise and one-off swings. 2. Pull TTM cash flow from operations (OCF) from the cash flow statement, using the same trailing twelve month window. 3. Strip out obvious one-offs where you can, such as a large litigation settlement or a one-time tax benefit that inflated net income but has nothing to do with core operations. 4. Grab beginning and ending total assets from the balance sheet for the period you're measuring. 5. Compute average total assets: (beginning total assets + ending total assets) divided by two. This is the standard scaling method practitioners use rather than dividing by revenue or ending assets alone. 6. Subtract OCF from net income, then divide that result by average total assets. That's your operating accruals ratio. 7. Cross-check with quarterly filings if you're working with a company that just reported. Combine the last four quarters rather than waiting for the annual 10-K to get a current read.
If a company doesn't publish a full cash flow statement (common with some private companies or thinly reported small caps), you can approximate accruals by summing changes in working capital accounts and adding back non-cash expenses like depreciation. It's rougher, but it gets you in the ballpark. Building this in a spreadsheet takes about ten minutes once you know where the four inputs live in a 10-K.
Operating-Only vs. Full Sloan: Which Formula Should You Use?
The version described above, net income minus operating cash flow, is the operating-only accruals ratio. It's the fast screening version and the one most retail tools default to.
The full Sloan formula goes a step further: it subtracts both operating cash flow and cash flow from investing from net income, then scales by average assets. Why bother? Because capex and acquisitions are real economic investments, not the kind of accrual games Sloan was worried about. Subtracting investing cash flow strips that noise out and isolates the working-capital driven accruals that actually predict weaker earnings quality.
Use the operating-only version when you're running a quick screen across a watchlist. Use the full Sloan version when you're doing deep diligence on a single name, particularly one with heavy capex or recent acquisitions, where the operating-only number alone could mislead you.
What Counts as a Normal Accruals Ratio?
These bands are heuristics, not laws of physics. Treat them as a starting point, not a hard cutoff.
Three things matter more than any single reading:
- The trend over three to five years matters more than one quarter. A company that has run a +12% accruals ratio for three straight years is telling you something different than one with a single spike.
- Peer and sector comparison matters because some industries run structurally higher accruals than others.
- The specific driver matters. Rising accounts receivable, ballooning inventory, or shrinking deferred revenue each tell a different story about why the number moved.
Rule of thumb: readings between −10% and +10% are generally considered normal, while sustained readings above +10% warrant a harder look at receivables and inventory growth relative to sales.
How Investors Actually Use the Accruals Ratio
Screening is the most common use. A high accruals ratio paired with a rich valuation multiple is a much bigger red flag than the same ratio on a cheap, out-of-favor stock.
Two workflows come up constantly:
- Pre-purchase quality check. Before buying a high-multiple growth name, run the accruals ratio alongside free cash flow trends to confirm the growth story is backed by real cash, not just booked revenue.
- Post-earnings sanity check. When a company beats EPS estimates but operating cash flow lags net income for that same quarter, the accruals ratio helps you decide whether the beat is real or just accounting timing.
Pro Tip: Watch for persistence, not spikes. A single quarter of elevated accruals tied to a known one-off (a big new contract just booked, a working-capital build ahead of a seasonal peak) is far less concerning than a ratio that creeps upward for three years running with no clear operational explanation.
Where the Accruals Ratio Falls Short
The ratio breaks down for financial-sector companies. Banks and insurers have balance sheets and cash flow statements built around loans, deposits, and float, structures the accruals ratio was never designed to interpret. Applying it to a bank produces a number that tells you almost nothing useful.
Capex-heavy manufacturers and fast-growing companies present a subtler trap. Heavy depreciation, rising deferred revenue from subscription growth, or a seasonal inventory build ahead of a strong quarter can all push the ratio into caution territory without any real earnings-quality problem underneath. The fix: compute both the operating-only and full Sloan variants, check receivables and inventory-day trends alongside the ratio, and never treat this number as a standalone verdict.
A Worked Example: Calculating the Accruals Ratio From Scratch
Take a hypothetical mid-cap company reporting the following for its trailing twelve months:
- Net income: $400 million
- Cash flow from operations: $250 million
- Cash flow from investing: negative $80 million (mostly capex)
- Beginning total assets: $2.8 billion
- Ending total assets: $3.2 billion
First, average total assets: ($2.8 billion + $3.2 billion) / 2 = $3.0 billion.
Worth watching over the next few quarters, not worth panicking about today.
How Oracle Investments Applies the Accruals Ratio in Stock Scoring
The app builds earnings-quality checks like the accruals ratio directly into how it scores stocks across profitability, valuation, and financial health. Instead of pulling three financial statements apart manually, you get a side-by-side view of how a company's reported earnings stack up against its actual cash generation.
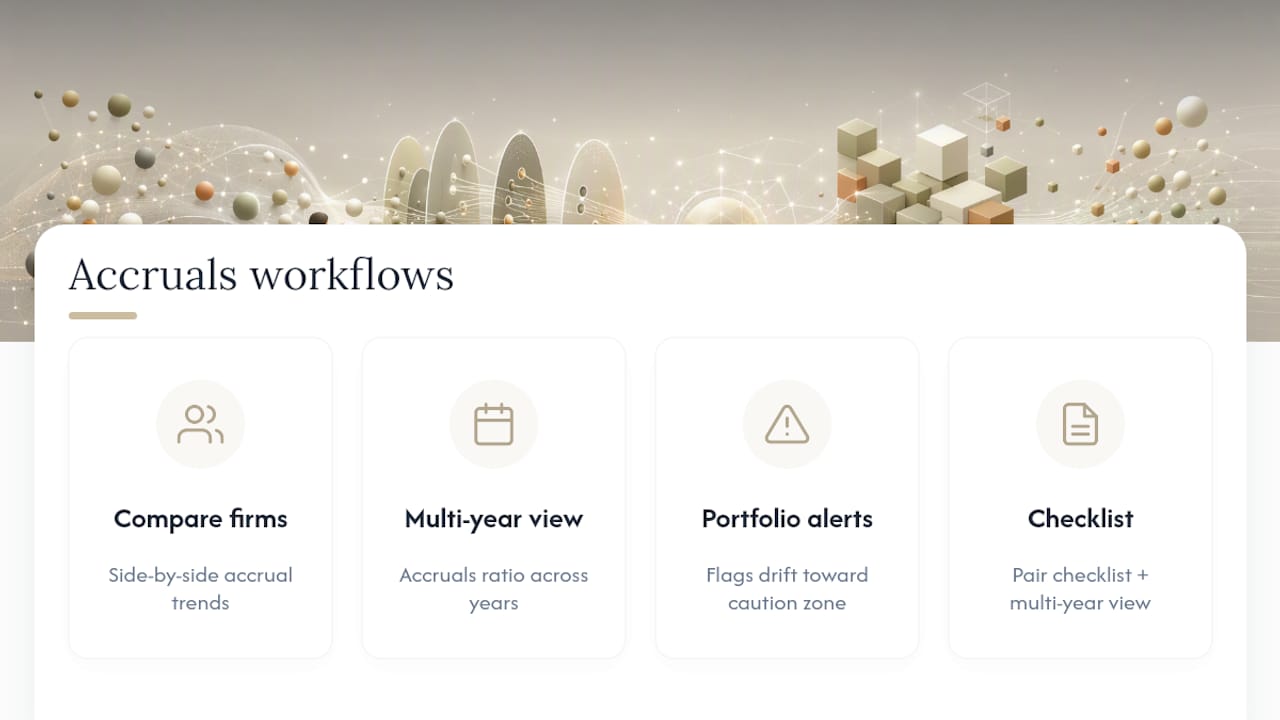
The app is built around a few practical workflows: comparing two companies' accrual trends side by side before deciding between them, viewing a single stock's accruals ratio across several years instead of one snapshot, and getting flagged when a name in your portfolio starts drifting toward the caution zone. Pairing an income statement checklist with a multi-year accruals view catches quality issues a single-quarter glance would miss. For a broader look at how earnings-quality signals fit into overall scoring, the earnings quality analysis breakdown on the Oracle blog walks through the fuller framework.
A Quick Checklist for Students and Analysts
Here's the order I'd actually run through, whether it's a homework problem or a real position I'm sizing up: check the trend first, not the single-period number. A three to five year pattern tells you far more than one quarter ever will. Second, identify what's driving the number: rising receivables, bloated inventory, or shrinking deferred revenue each point to a different story, and lumping them together hides the real issue.
Third, compare against sector peers before assuming a reading is abnormal; capital-intensive industries run structurally different baselines than software companies. Fourth, verify whether any spike traces back to a known one-off rather than a genuine operating shift.
One distinction worth holding onto: in coursework, the ratio is often treated as a clean pass/fail test. In real-world screening, it's one input among several, useful mainly for deciding where to spend your diligence time next.
— Matt
Track Accruals Trends Without Building a Spreadsheet Every Quarter
Running this calculation by hand across a watchlist gets old fast, especially when you're trying to catch a trend before it shows up in next quarter's headlines. The app folds accruals-based earnings-quality checks into its stock scores for numerous companies, so you can compare a name's multi-year cash-flow-versus-earnings pattern against peers in seconds instead of pulling three statements apart by hand.
The app pairs that with the kind of fundamentals-first thinking Warren Buffett, Charlie Munger, and Peter Lynch built their reputations on, scoring profitability, valuation, and financial health side by side so a rising accruals ratio doesn't slip past you between earnings seasons. If you want to see how a stock's accruals trend actually shows up in its overall score, check out Oracle Investments and pull up any name on your watchlist to start comparing.