FCF conversion measures the share of a company's operating profit, usually EBITDA, that actually turns into free cash flow. The formula is simple: (Free Cash Flow ÷ EBITDA) × 100. A higher number generally signals better cash quality, but the figure only means something when you know which denominator was used and whether it stayed consistent across the periods and peers you're comparing.
TL;DR:
- Companies with free cash flow conversion rates below 50% should be examined for potential cash generation issues or high capital expenditures.
- Using EBITDA as the denominator is standard, but asset-heavy businesses may need to compare with net income or EBIT for more accurate analysis.
- A 80% FCF conversion rate is a typical benchmark, but variations depend on industry capital intensity and business models.
- Building an EBITDA to FCF bridge helps identify whether changes in conversion rates stem from operational shifts or timing effects.
- Always reconcile company-provided FCF figures to GAAP cash flow to avoid misleading comparisons caused by different non-GAAP definitions.
Table of Contents
- What FCF conversion measures and why analysts use it
- How to calculate FCF conversion step-by-step
- Choosing a denominator that keeps comparisons honest
- What counts as a good FCF conversion rate
- Building an EBITDA to FCF bridge to find the real story
- A worked example of FCF conversion in practice
- Levers management can pull to improve conversion
- Where FCF conversion can mislead you
- Using FCF conversion in everyday analyst work
- This tool helps you compare cash efficiency across companies
- Sources
- FAQ
What FCF conversion measures and why analysts use it
Free cash flow is typically cash from operations minus capital expenditures, both found on the cash flow statement. EBITDA comes from the income statement: net income plus interest, taxes, depreciation, and amortization. FCF conversion links the two, showing how much of a company's reported operating profit survives the trip to actual cash in the bank, as Corporate Finance Institute explains.
This matters because earnings can be manufactured through accounting choices in ways cash flow can't. Analysts lean on the ratio for a few recurring jobs:
- Testing whether reported EBITDA reflects real cash-generating power before using it in a valuation multiple.
- Screening credit risk, since lenders care about cash available to service debt, not accounting profit.
- Flagging aggressive revenue recognition or working capital manipulation before it shows up elsewhere.
Before trusting the ratio, check that the FCF definition and time period match across whatever you're comparing. For a deeper walkthrough of the components, see this explainer on free cash flow.
How to calculate FCF conversion step-by-step
- Pull cash from operations (CFO) and capital expenditures from the cash flow statement, then compute FCF = CFO minus CapEx.
- Calculate EBITDA from the income statement: net income plus interest, taxes, depreciation, and amortization, reconciling any add-backs management discloses separately.
- Divide FCF by EBITDA and multiply by 100 to get the conversion percentage, choosing either annual or trailing-twelve-month figures and applying that choice consistently.
- Scan for data-quality issues: one-time charges, lease accounting adjustments, and tax timing differences that can distort either side of the equation.
Practitioner benchmark: CFI's guide notes that conversion rates below roughly 50% typically warrant deeper investigation into why operating profit isn't reaching cash.
Companies also disclose their own free cash flow definitions in filings, and those definitions vary. An SEC exhibit on non-GAAP measures shows how reconciliations differ by company, which is exactly why you reconcile any company-provided FCF figure back to GAAP operating cash flow before comparing it to another firm's number.

Choosing a denominator that keeps comparisons honest
EBITDA is the default denominator because it's widely reported and strips out financing and accounting noise. Its weakness is that it ignores CapEx, taxes, and working capital entirely, which can make a capital-intensive business look healthier than its cash flow supports.
- EBIT or net income often works better for asset-heavy firms where depreciation and amortization are large enough to distort EBITDA-based ratios.
- Software and services companies with light fixed-asset bases tend to be well served by EBITDA as the denominator.
- Whichever denominator you pick, apply it consistently across every company and period in your analysis, and document any adjustment you make.
The goal isn't finding the "correct" denominator. It's making sure your comparison isn't secretly comparing two different things.
What counts as a good FCF conversion rate
Practitioner literature commonly cites a rate around 80% as a healthy benchmark, though the right target depends heavily on capital intensity and business model. A manufacturer with heavy ongoing CapEx will naturally run lower than an asset-light software company, so treat 80% as a starting reference point rather than a universal cutoff.
- Rates approaching or exceeding 100% often reflect working capital releases or unusually low CapEx in a given period, not necessarily a structural improvement.
- Rates well below 50% deserve a closer look at receivables growth, inventory buildup, or heavy reinvestment that EBITDA doesn't capture.
- When feeding conversion into valuation or credit work, pair it with the EV/EBITDA multiple you're using, since a low-conversion company trading on a rich multiple is a mismatch worth investigating.
Context beats a fixed threshold every time. A single quarter's number tells you less than a multi-year trend against the same peer set.
Building an EBITDA to FCF bridge to find the real story
A conversion percentage tells you something changed. It doesn't tell you what. Building an EBITDA-to-FCF bridge turns the ratio into a diagnostic tool, as the EBITDA to FCF tutorial from Breaking Into Wall Street lays out.
- Start with EBITDA as reported.
- Subtract cash taxes paid and cash interest paid, both pulled from the cash flow statement or footnotes.
- Add or subtract the period's working capital movement: changes in receivables, inventory, and payables.
- Subtract capital expenditures.
- Note any one-off cash items separately, such as litigation settlements or asset sale proceeds, so they don't get buried in the "normal" conversion story.
The output should land close to your calculated FCF. If it doesn't, you've likely mismatched a definition somewhere.
Pro Tip: When conversion jumps year over year, run the bridge before celebrating: an inventory drawdown that boosted this year's cash won't repeat next year, while a genuine CapEx reduction might.
A worked example of FCF conversion in practice
- Say a company reports cash from operations of $180 million and capital expenditures of $60 million for the year, giving FCF of $120 million.
- Say EBITDA for the same period is $200 million.
- Conversion = ($120 million ÷ $200 million) × 100 = 60%.
- Checking the bridge, suppose working capital released $15 million in cash while cash taxes and interest absorbed $25 million, roughly explaining the gap between EBITDA and FCF beyond CapEx alone.
Statistic callout: A 60% conversion rate falls below the roughly 80% benchmark practitioners often cite, which by itself isn't alarming but should prompt a look at whether CapEx is temporarily elevated for a growth project or represents a structural cost of the business. Readers modeling this figure forward into a valuation can see how it feeds a discounted cash flow analysis.
Levers management can pull to improve conversion
Some improvements are structural and repeatable. Others are one-time and worth flagging as such when you spot them.
- Tightening receivables collection, managing inventory levels, and negotiating longer payables terms all improve the cash conversion cycle without touching the income statement.
- Prioritizing CapEx toward projects with the clearest return, and deferring discretionary spend, raises FCF without necessarily hurting future EBITDA.
- Margin expansion through cost control tends to be sustainable, while a one-time asset sale or a single quarter's working capital swing usually isn't.
Watch which type of improvement is driving the number before assuming it will persist.
Where FCF conversion can mislead you
The ratio is a starting point, not a verdict, and a few common traps can distort it.
- One-time tax benefits, asset sales, or unusually favorable working capital swings can flatter a single period's conversion rate without reflecting the underlying business.
- Companies define free cash flow differently in their own disclosures, so always reconcile a company-provided figure to GAAP operating cash flow, a point SEC filings on non-GAAP measures make clear through varied reconciliation practices.
- Pair conversion with complementary measures like the cash conversion cycle or owner earnings to avoid leaning on one ratio alone.
Using FCF conversion in everyday analyst work
FCF conversion earns its place in a workflow when it's used to validate whether reported EBITDA can be trusted, not as a standalone score. I treat a weak or unusually strong number as a prompt to build the bridge, then check it against the company's own disclosures for context.
The caveat worth remembering: non-GAAP free cash flow definitions vary company to company, so the number only means what you've confirmed it means.
— Matt
This tool helps you compare cash efficiency across companies
Building an EBITDA-to-FCF bridge by hand for one company is manageable. Doing it for a dozen candidates before deciding where to put your money is a different kind of task. The app scores a broad selection of stocks on fundamentals including profitability and financial health, letting you compare companies side by side without rebuilding a spreadsheet for each one.
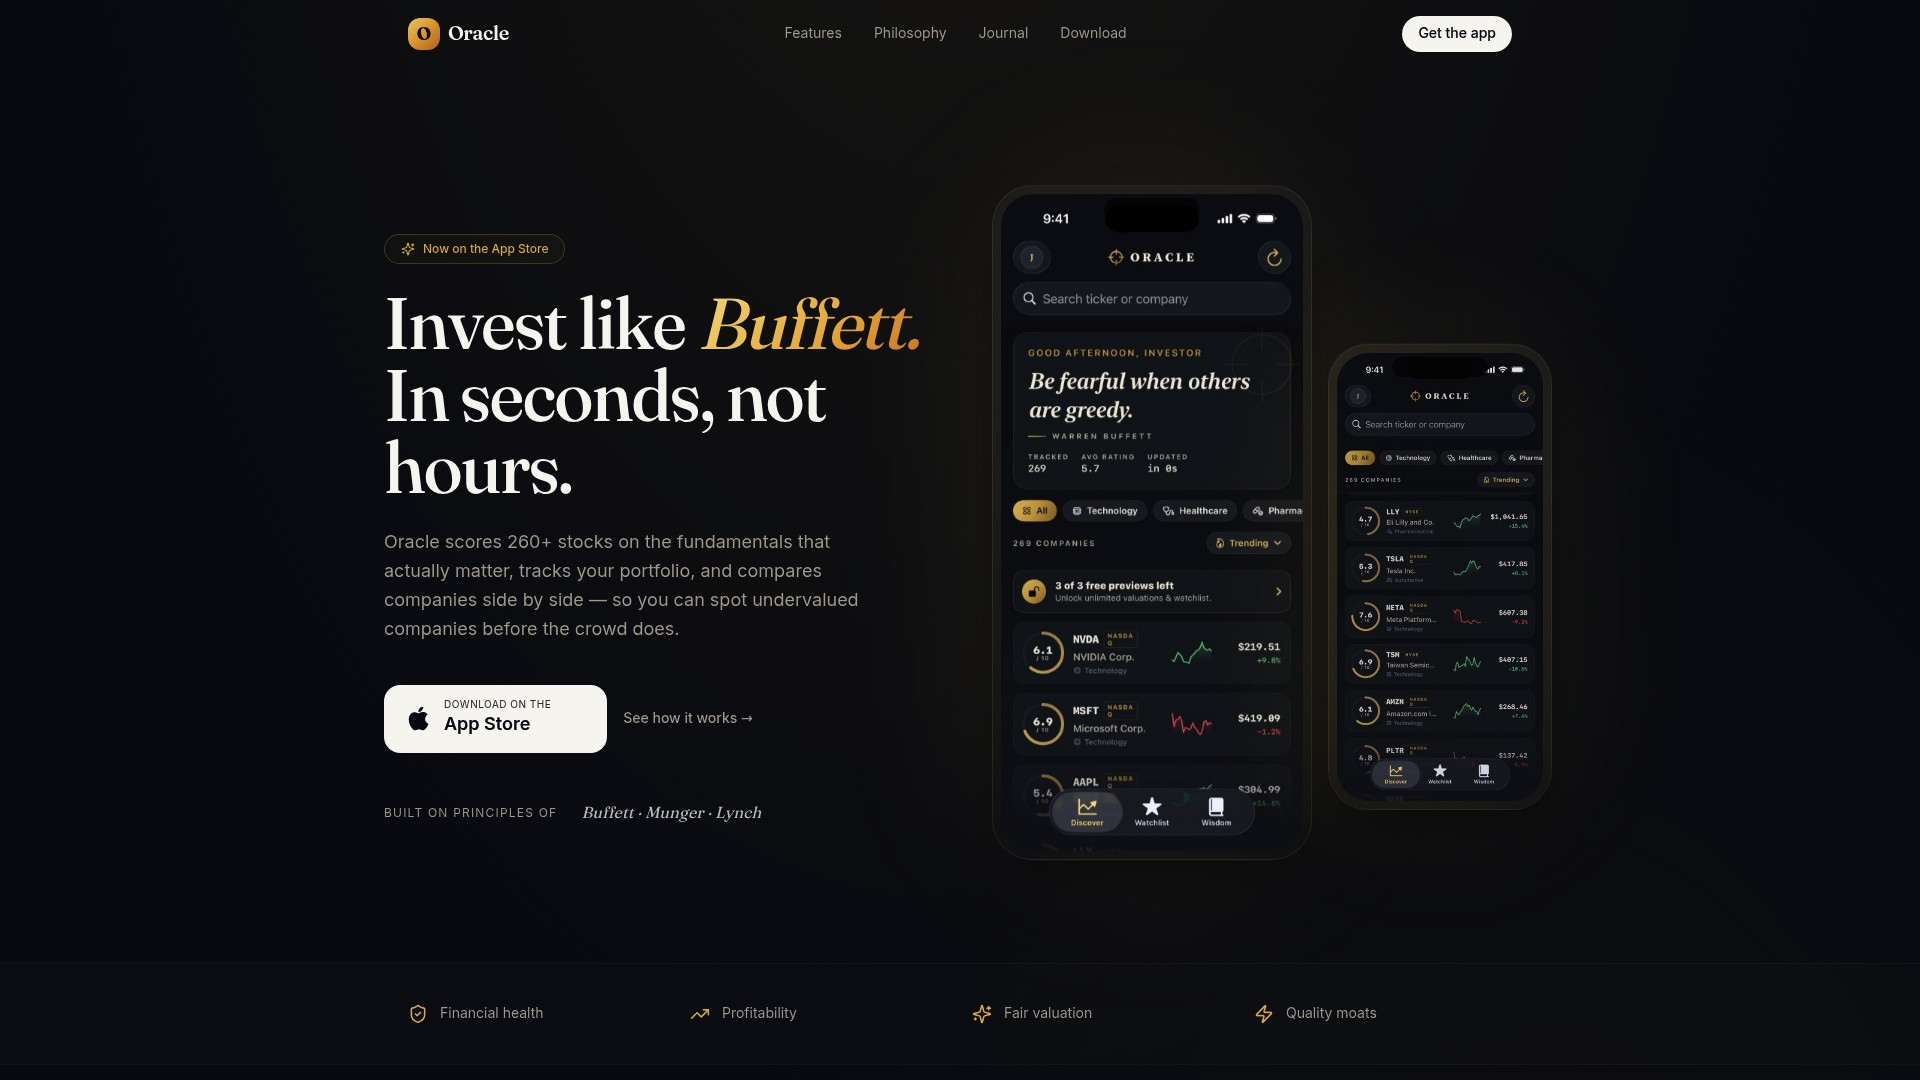
The scoring is rule-based and built on reported fundamentals rather than model-driven guesswork, with inputs shown transparently so you can see what's behind a score. It complements the manual bridge work covered above rather than replacing it: use the app to screen candidates quickly, then apply the bridge method to the ones worth a closer look. The Premium Annual plan unlocks the full comparison and portfolio tracking features for readers who want to move faster.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Free Cash Flow Conversion: Guide to Calculation and Analysis | CFI
- SEC exhibit: company non-GAAP measures (example disclosure)
FAQ
How do you calculate FCF?
Free cash flow equals cash from operations minus capital expenditures, both taken from the cash flow statement. Once you have FCF, dividing it by EBITDA and multiplying by 100 gives the conversion percentage, as outlined in CFI's methodology.
What is a good FCF conversion rate?
Practitioner guides commonly point to around 80% as a healthy benchmark, though capital-intensive industries typically run lower and asset-light businesses often run higher. Context and consistency across the comparison matter more than hitting a single fixed number.
Is FCF conversion the same as FCF margin?
No. FCF conversion compares free cash flow to EBITDA (or another profit measure), while FCF margin compares free cash flow to revenue. Both describe cash efficiency, but they answer different questions and shouldn't be used interchangeably.
Is FCF the same as FCFE?
No. Free cash flow (FCF) generally refers to cash from operations minus capital expenditures, while free cash flow to equity (FCFE) adjusts that figure further for net borrowing, isolating the cash available specifically to equity holders. The two serve different purposes in valuation and shouldn't be substituted for one another.