A company's reinvestment rate is the share of its after-tax operating profit that goes back into the business, through new equipment, facilities and working capital, instead of being available to owners. It tells you how much a company is investing for growth. Whether that investment is worth it depends on the return it earns, which is why the number only makes sense next to return on invested capital (ROIC). This guide gives you the formula, a worked example, where to find each input, and a way to read the result as a value investor.
TL;DR
- Reinvestment rate = (net capital expenditures + change in non-cash working capital) ÷ after-tax operating income. It measures how much a company reinvests.
- ROIC measures how well that money is put to work. Expected growth in operating income is roughly reinvestment rate × ROIC.
- A high reinvestment rate is good only when returns on new investment beat the cost of the capital behind it.
- Do not confuse it with the equity retention ratio, bond reinvestment risk, or the reinvestment assumption inside IRR.
- Oracle scores more than 260 stocks on profitability, valuation and financial health, so you can see the fundamentals behind this number side by side.
Table of Contents
- What the reinvestment rate tells you
- The formula, piece by piece
- A worked example
- Where to find the numbers
- Pairing it with ROIC to estimate growth
- Reading a high or low reinvestment rate
- Not the same as retention ratio, bond reinvestment risk or IRR
- Using it in a stock screen
- Where Oracle fits
- Our perspective
- FAQ
- Sources
What the reinvestment rate tells you
Every profitable company faces the same choice each year: put the profit back into the business, or hand it to shareholders through dividends and buybacks. The reinvestment rate puts a number on the first half of that choice.
Aswath Damodaran of NYU Stern frames it as a pair of questions. The reinvestment rate measures how much a company reinvests, while ROIC measures how well it reinvests. Two companies can both reinvest 40% of their operating profit. One turns that money into steadily rising earnings, and the other turns it into factories that barely pay for themselves. The rate alone cannot tell them apart.
Why should you care? Because growth is not free. Operating income cannot keep growing over time without reinvestment in capital spending, working capital, or both. If a company promises fast growth but reinvests almost nothing, either the growth is coming from somewhere unusual or the promise will not hold.
The formula, piece by piece
The standard version, as defined in Damodaran's data set definitions, is:
Reinvestment rate = (net capital expenditures + change in working capital) ÷ EBIT × (1 − tax rate)
Each piece in plain words:
- EBIT is earnings before interest and taxes, also called operating income. It is the profit the business itself produces, before financing costs.
- EBIT × (1 − tax rate) is after-tax operating income, often abbreviated NOPAT (net operating profit after tax). This is the denominator: the pool of profit available to reinvest.
- Net capital expenditures are capital expenditures minus depreciation. Capital expenditures (capex) are what the company spends on property, plant, equipment and similar long-lived assets. Subtracting depreciation leaves only the spending that adds to the asset base, not the spending that replaces what wore out.
- Change in non-cash working capital is the year-over-year change in operating current assets (such as receivables and inventory) minus operating current liabilities (such as payables), leaving cash out. A growing business usually ties up more money in inventory and customer credit, and that counts as reinvestment.
Two details trip people up. First, the numerator can be negative: a company that spends less on capex than it books in depreciation, or that shrinks its working capital, has a reinvestment rate below zero. That is common in mature or shrinking businesses. Second, acquisitions are real reinvestment too. Many analysts add the cash spent on acquisitions to capex when a company grows by buying other firms, because leaving it out understates how much capital went in.
A worked example
Here is a made-up company, for illustration only. Its latest annual figures, in millions of dollars:
| Item | Amount |
|---|---|
| EBIT (operating income) | 1,000 |
| Tax rate | 25% |
| Capital expenditures | 400 |
| Depreciation | 250 |
| Increase in non-cash working capital | 50 |
Step by step:
- After-tax operating income: 1,000 × (1 − 0.25) = 750.
- Net capex: 400 − 250 = 150.
- Add the working capital change: 150 + 50 = 200.
- Reinvestment rate: 200 ÷ 750 = 26.7%.
The company put about 27 cents of every dollar of after-tax operating profit back into the business. Now suppose its ROIC is 15%. Expected growth in operating income is 26.7% × 15% = 4.0% a year. If ROIC were 25% on the same reinvestment, growth would be about 6.7%. Same effort, very different result.
One more point on the tax rate. Use the rate that reflects the company's normal operating taxes. A single year with an unusual tax benefit or charge can distort the denominator, so when a year looks odd, compare it with the two or three years around it.
Where to find the numbers
Everything you need sits in a company's annual report (Form 10-K for U.S. public companies):
- EBIT: the operating income line on the income statement.
- Tax rate: income tax expense divided by pre-tax income, or the statutory rate if you want a normalized figure.
- Capex and depreciation: capex is on the cash flow statement under investing activities (often labeled purchases of property and equipment). Depreciation and amortization appears in the operating section of the same statement.
- Working capital: the balance sheet. Take operating current assets excluding cash, subtract operating current liabilities excluding short-term debt, and compare with the prior year.
A sensible habit is to calculate the rate for five years, not one. Capital spending is lumpy. A company that builds a plant in one year and spends little the next will swing between a high and a low rate, and the multi-year average tells you more about how it behaves.
One reader's question is worth answering directly: where do I find ROIC to pair with it? It is not on any statement, since it is calculated from them. Our guide to return on invested capital walks through the calculation, and return on capital employed covers a close cousin.
Where the money comes from matters as well. Companies fund reinvestment from retained profits, borrowing or new equity, and capital raising best practices show the same trade-offs in another industry: more invested capital has to earn enough to justify its cost.
Pairing it with ROIC to estimate growth
The link between the two measures is simple:
Expected growth in operating income = reinvestment rate × ROIC
NYU Stern's valuation notes illustrate it with a large pharmaceutical company: a reinvestment rate of 32.21% times a return on capital of 25.15% gives expected growth of 8.10%. The relationship assumes the company can keep earning that return on the new money it invests, which is a big assumption and the one worth testing.
The equation works in both directions. If an analyst forecasts 10% growth and the company has an ROIC of 20%, the business needs to reinvest about half of its after-tax operating income (0.10 ÷ 0.20 = 50%). If its actual reinvestment rate is 10%, the forecast and the fundamentals do not agree, and one of them is wrong. That is the same logic behind a reverse DCF, where you start from the price and ask what growth it implies. Our reverse DCF guide shows how to run that check in a spreadsheet.
Reading a high or low reinvestment rate
There is no universally good number. The answer depends on what the money earns.
Growth adds value only when returns on new investment exceed the cost of the capital used to fund it. Growth that earns only its funding cost creates no excess value. So a high reinvestment rate is desirable when the company earns returns above its cost of capital, and it is a warning sign when it does not. If you need a way to estimate that hurdle, see our piece on three ways to calculate a required rate of return.
Here is a practical way to sort what you find:
| Reinvestment rate | ROIC vs. cost of capital | What it usually means |
|---|---|---|
| High | Well above | A compounder: growth is paying for itself and then some. This is the profile value investors hunt for. |
| High | Near or below | Growth that consumes capital without rewarding owners. Look hard at the next acquisition or expansion. |
| Low | High | A strong business with few places to put new money, or one that prefers to return cash. Growth will be modest, but cash flows to owners. |
| Low or negative | Low | A mature or shrinking business. Check whether depreciation is outrunning spending on the asset base. |
Three habits keep the reading honest:
- Compare within an industry. A software firm needs little physical capital, so its rate may look low even while it grows quickly. A utility or a railroad reinvests heavily just to keep up.
- Watch the trend, not the snapshot. A rate that rises while ROIC holds steady is a good sign. A rate that rises while ROIC falls means each new dollar is earning less than the last.
- Check where the leftover cash goes. What a company does not reinvest, it can return through dividends or buybacks. Our guide to the dividend payout ratio shows how to judge the dividend half of that decision.
Not the same as retention ratio, bond reinvestment risk or IRR
The phrase "reinvestment rate" shows up in several corners of finance, and the search results for it mix them together. Here is how to keep them apart.
Equity retention ratio. This is the share of net income a company keeps instead of paying as dividends. It is an equity-side measure. The reinvestment rate described here is firm-level: Damodaran's answer on this point notes it uses after-tax EBIT and total invested capital, so it should not be swapped mechanically for a retention ratio or for return on equity. Corporate reinvestment of earnings in general means profits kept in the business rather than distributed through dividends or buybacks, and the reinvestment rate is the operating-side way of measuring it.

Bond reinvestment risk. For a bond investor, this is the risk that coupons or principal must be reinvested later at lower interest rates. It describes what happens to your cash, not what a company does with its profit. Different problem, same word.
The reinvestment assumption in IRR and NPV. The internal rate of return is the discount rate that makes an investment's net present value equal to zero. According to CFA Institute commentary, IRR is a true rate of return only if interim distributions are reinvested at the IRR and later investments are financed at that same rate. This is a modeling assumption about project cash flows, which is why a high IRR on paper can overstate what you actually earn.
If you landed here from a real estate or bond query, those are separate topics. The rest of this article is about the stock-analysis meaning.
Using it in a stock screen
A short routine turns the idea into something repeatable:
- Start with profitability. Look for ROIC that is consistently above a reasonable cost of capital. If it is not, a high reinvestment rate is a reason for caution, not excitement.
- Calculate the five-year average reinvestment rate with the steps above.
- Multiply the two to get an implied growth rate, and compare it with what the market seems to expect.
- Test it against price. Growth only helps if you are not overpaying for it. Our intrinsic value guide and the valuation metrics checklist cover that step.
- Check financial health. Reinvestment funded by heavy borrowing is a different animal from reinvestment funded by operating cash.
Doing this for one company in a spreadsheet is a pleasant evening. Doing it for twenty is the point where most people stop.
Where Oracle fits
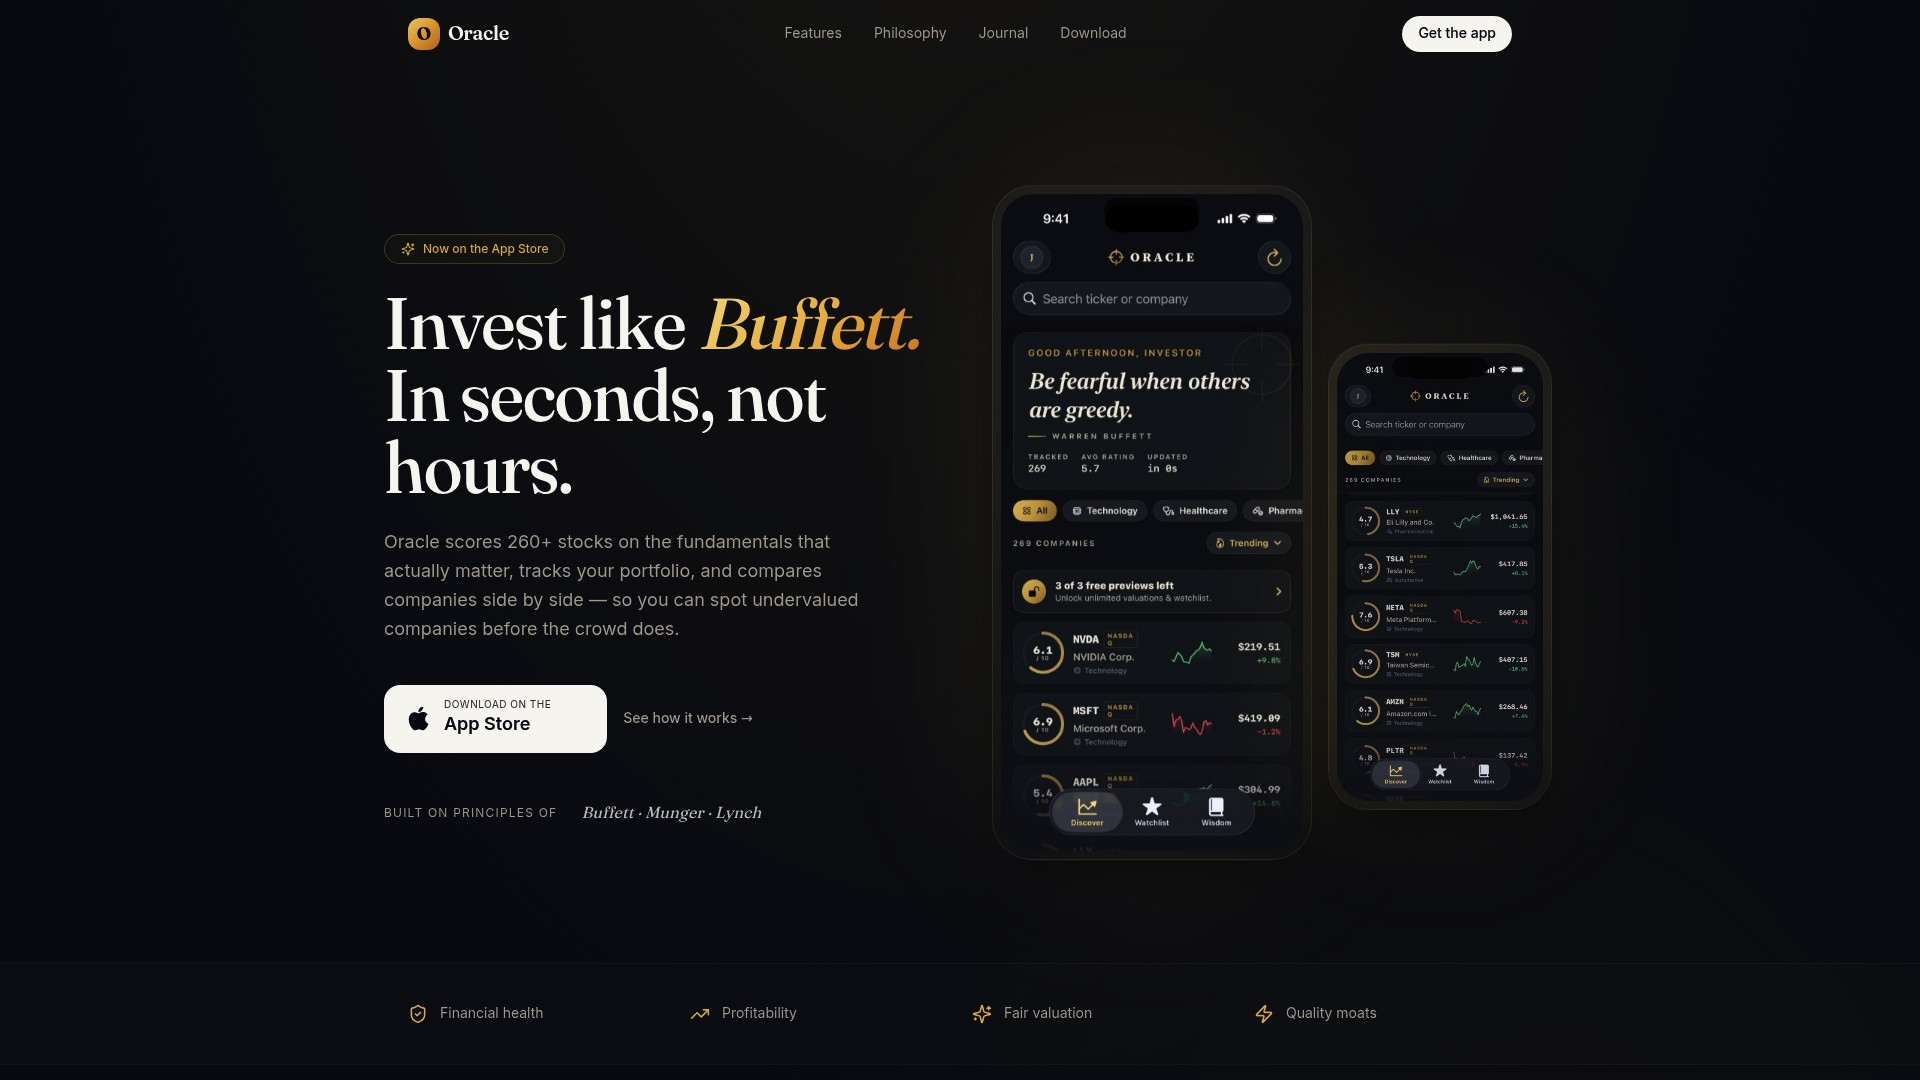
The reinvestment rate is one lens on a company's fundamentals. Oracle Investments scores more than 260 stocks on profitability, valuation and financial health, so you can put companies side by side and see which look undervalued without building a model first. The scores are rule-based and grounded in reported company fundamentals, and the scoring inputs are shown, so you can see what sits behind each rating. The app also includes lessons from value investors such as Warren Buffett, Charlie Munger and Peter Lynch, and tracks your portfolio in real time.
If you want to move from one calculation to a whole list of comparable companies, the Premium Annual plan is where to start.
Our perspective
Most people learn the reinvestment rate as a formula and then stall, because the formula produces a number and not a decision. The decision comes from asking what each reinvested dollar earns.
That is why we pair it with returns every time. A company that reinvests heavily at high returns is doing exactly what a value investor wants an owner of capital to do. A company that reinvests heavily at poor returns is spending your money.
We built Oracle around reported fundamentals and rule-based scores, with the inputs visible, because we think disciplined value investing should be quick and transparent. Buffett, Munger and Lynch all came back to the same idea: understand what the business earns on its capital, then pay a sensible price. Doing that in seconds, without a spreadsheet, is what we want for every investor, from a first-time buyer to someone managing a retirement portfolio.
Matt
FAQ
What is a good reinvestment rate?
There is no single good number. What matters is the return the company earns on the money it reinvests. A rate of 40% with ROIC well above the cost of capital builds value, while the same 40% with weak returns can destroy it. Compare against peers in the same industry and look at the five-year trend.
Can the reinvestment rate be negative?
Yes. If net capital expenditures plus the change in working capital add up to less than zero, for example because depreciation exceeds capex, the rate is negative. That usually signals a mature or shrinking business that is releasing capital instead of investing it. Check whether the asset base is being allowed to wear down.
How is the reinvestment rate different from the retention ratio?
The retention ratio measures the share of net income kept instead of paid as dividends. The reinvestment rate measures net capital spending and working capital changes as a share of after-tax operating income. The first is about equity holders, and the second is about the whole operating business, so they can differ a lot, especially for companies with debt.
How do I estimate growth from the reinvestment rate?
Multiply the reinvestment rate by ROIC. A company reinvesting 30% of after-tax operating income at a 20% return would be expected to grow operating income about 6% a year. The estimate holds only if the company keeps earning that return on new capital, so treat it as a starting point and test it against the company's history.
Sources
- Aswath Damodaran, NYU Stern: return measures paper (2007)
- NYU Stern: Answer to Question 7
- NYU Stern: Variables used in Data Set
- NYU Stern: Valuation in 60 minutes
- CFA Institute: The Equity Advantage: Reinvestment of Earnings (2022)
- CFA Institute: A Reality Check on Private Markets, Part II (2024)