A dividend reinvestment plan, or DRIP, automatically uses the cash dividends a stock pays you to buy more shares of that same stock instead of depositing cash in your account. The main draw is automatic compounding: each reinvested dividend buys shares that can themselves earn future dividends. One catch worth flagging immediately: the IRS still treats those reinvested dividends as taxable income in the year they're paid, even though you never touched the cash.
TL;DR:
- Reinvested dividends are taxed in the year they are paid, despite not receiving the cash directly, which can impact your tax planning.
- Company-sponsored DRIPs may offer discounts and fees, but offer less control over purchase timing compared to brokerage DRIPs, which are more flexible.
- Long-term investors benefit most from reinvesting due to automatic compounding, especially if they do not need dividend cash for immediate expenses.
- Fees, purchase minimums, and record-keeping requirements vary widely across plans, making it crucial to review plan details before enrolling.
- Reinvesting can lead to portfolio imbalance if not periodically rebalanced, as a single stock position can grow disproportionately over time.
Table of Contents
- How dividend reinvestment works: the mechanics and key terms
- Company-sponsored DRIPs vs brokerage (synthetic) DRIPs: practical differences
- Why reinvest dividends: compounding and who benefits most
- Costs, fees and program limits to watch for
- Tax and record-keeping: IRS rules, Form 1099-DIV, and adjusted cost basis
- How to enroll or enable dividend reinvestment: a step-by-step checklist
- When not to reinvest: risks, suitability, and alternatives
- Worked example and calculator guidance to project reinvestment outcomes
- When DRIPs fit a sensible plan
- A closer look at Oracle Investments for reinvestment planning
- FAQ
- Sources
How dividend reinvestment works: the mechanics and key terms
When a company declares a dividend, your reinvestment plan routes the cash toward new shares on or near the payment date, rather than crediting it to your brokerage balance. Most plans support fractional shares, so a $43 dividend might buy 1.37 shares instead of sitting as leftover cash.
A few mechanical details shape how this plays out:
- Purchases typically happen within a day or two of the payment date, not instantly.
- Shares bought through a company plan are often held in book-entry form with a transfer agent, while brokerage-held shares stay as beneficial ownership in your account.
- Many plans let you reinvest only part of a dividend and take the rest as cash, a feature worth checking before you enroll.
Timing matters because you don't control the exact purchase price. You're buying at whatever the plan's execution window delivers, which can differ slightly from the quoted price at the moment the dividend was declared.
Company-sponsored DRIPs vs brokerage (synthetic) DRIPs: practical differences
Investor: company-sponsored plans and brokerage-offered reinvestment, often called synthetic DRIPs. Each has a different cost and convenience profile.
- Company-sponsored DRIPs: enrolled directly through a transfer agent, these sometimes offer small share-price discounts, optional cash purchases, and their own fee schedules and purchase calendars.
- Brokerage DRIPs: set up inside your existing account, these consolidate everything on one statement, cover a broader range of stocks and funds, and usually come without a purchase discount.
- Dividend reinvestment and stock purchase plans, often paired as DRIPs/DSPPs, matter most for investors who want to build a position in one company gradually and don't mind giving up control over exact trade timing.
The trade-off is control versus convenience. A company plan can mean better pricing on paper, but you give up the ability to set a limit price or choose your exact execution moment, something a brokerage account handles more flexibly.
Why reinvest dividends: compounding and who benefits most
Reinvesting turns each dividend into more shares, and those shares generate their own dividends next quarter, a cycle that compounds quietly over years. It also creates a built-in dollar-cost-averaging effect: because dividends arrive on a fixed schedule regardless of price, you end up buying more shares when prices dip and fewer when they climb.
Investor.gov's compound interest calculator lets you model how repeated, regular contributions compound over time, which is effectively what a DRIP does with dividend cash instead of new deposits.

This approach tends to favor investors with a long horizon and no near-term need for the cash. If you're decades from retirement and don't need dividend income to cover living expenses, reinvestment lets compounding do the heavy lifting with no extra effort on your part. Our long-term investing strategy guide covers how buy-and-hold discipline pairs with this kind of automatic compounding.
Costs, fees and program limits to watch for
Reinvestment isn't always free, and the fine print varies by plan. Some company-sponsored DRIPs charge enrollment, purchase, or even sale fees, details usually spelled out in the plan prospectus rather than in marketing material.
- Company plans may charge setup or per-purchase fees that quietly erode the benefit of any share discount.
- Brokerage DRIPs can cap which securities qualify for automatic reinvestment, and fractional-share support varies by broker.
- Execution timing means you can't set a limit price, so you're accepting whatever price the plan's purchase window delivers.
- Dozens of small reinvestment lots over the years create a real record-keeping burden when it's time to calculate gains or losses.
Pro Tip: Before enrolling, read the plan's fee schedule or prospectus language directly rather than relying on a summary, since purchase minimums and fees differ plan to plan.
Tax and record-keeping: IRS rules, Form 1099-DIV, and adjusted cost basis
Reinvested dividends are still dividends in the eyes of the tax code. The IRS requires that they be reported as income in the year paid, regardless of whether you received cash or new shares.
- Your broker or the company's transfer agent issues Form 1099-DIV, which separates ordinary dividends (box 1a) from the qualified portion (box 1b) that often qualifies for lower capital gains tax rates.
- Every reinvestment purchase increases your cost basis in that holding, which reduces the taxable gain (or increases the loss) when you eventually sell.
- If your ordinary dividends exceed $1,500 in a year, the IRS requires you to report them on Schedule B, and large dividend income can also factor into the Net Investment Income Tax or estimated quarterly payments.
- Save every dividend and reinvestment statement, and consider exporting records into a cost-basis tracking tool rather than reconstructing years of small purchases by hand later.
| Tax item | What it means for DRIP investors |
|---|---|
| Form 1099-DIV | Reports ordinary and qualified dividend amounts for the year, even if reinvested |
| Cost basis | Rises with each reinvestment purchase, lowering future taxable gains |
| Schedule B | Required once ordinary dividends exceed $1,500 in a year |
| NIIT / estimated tax | Can apply when dividend income is large enough to trigger additional tax |
How to enroll or enable dividend reinvestment: a step-by-step checklist
Enrolling is usually quick, but the exact path depends on whether your shares are held at a brokerage or registered directly with the company.
- Decide whether you want a brokerage DRIP or a company-sponsored plan, and confirm whether your shares are held in a brokerage account or registered directly with a transfer agent.
- At a broker, go to your account or dividend settings, look for a "dividend reinvestment" toggle, and confirm the position supports fractional shares before switching it on.
- For a company plan, complete the transfer agent's enrollment form, noting the record date that determines which upcoming dividend qualifies for reinvestment, and decide if you'll use optional cash purchases.
- Check your next statement to confirm the reinvestment actually processed, and adjust settings again if the share count didn't change as expected.
Pro Tip: Set a calendar reminder to review your DRIP settings once a year, since brokers occasionally reset automatic reinvestment elections after account transfers or statement changes.
When not to reinvest: risks, suitability, and alternatives
Reinvesting isn't automatically the right move for every dividend payer in your portfolio. A few situations call for taking the cash instead.
- You need the dividend income to cover near-term expenses or short-term goals.
- Reinvesting keeps growing your position in a single stock, raising concentration and sector risk inside your portfolio.
- You're due for a rebalance, or tax and estate planning reasons make holding cash temporarily more useful.
- A partial DRIP, reinvesting only some of each dividend, or periodic manual withdrawals can split the difference between compounding and flexibility.
Retirees in particular should weigh income needs carefully before reinvesting by default; our retiree investing strategy guide walks through that trade-off in more depth.
Worked example and calculator guidance to project reinvestment outcomes
Reinvesting the dividends each quarter means next quarter's payout is calculated on a slightly larger share count, so the position compounds faster than it would if the cash sat uninvested.
To model your own numbers, adjust these variables in a calculator:
- Starting investment amount and current dividend yield.
- Payout frequency (quarterly is most common among US dividend stocks).
- Assumed dividend growth rate and total time horizon.
The VTI DRIP calculator from Evibe lets you plug in your own yield and horizon assumptions to see projected outcomes for a specific fund or stock.
When DRIPs fit a sensible plan
DRIPs reward investors who can leave money alone for years and don't need the income now. The real risk isn't reinvesting itself, it's forgetting to rebalance as one position quietly grows into an outsized chunk of your portfolio. Checking dividend payers side by side in a tool like this makes that kind of portfolio check easier to stay on top of.
— Matt
A closer look at Oracle Investments for reinvestment planning
Running DRIP scenarios by hand across a watchlist of dividend payers gets tedious fast, which is where a comparison tool earns its keep. We built a tool to score stocks on profitability, valuation, and financial health, so you can see which dividend payers are fundamentally sound before committing years of reinvested cash to them.
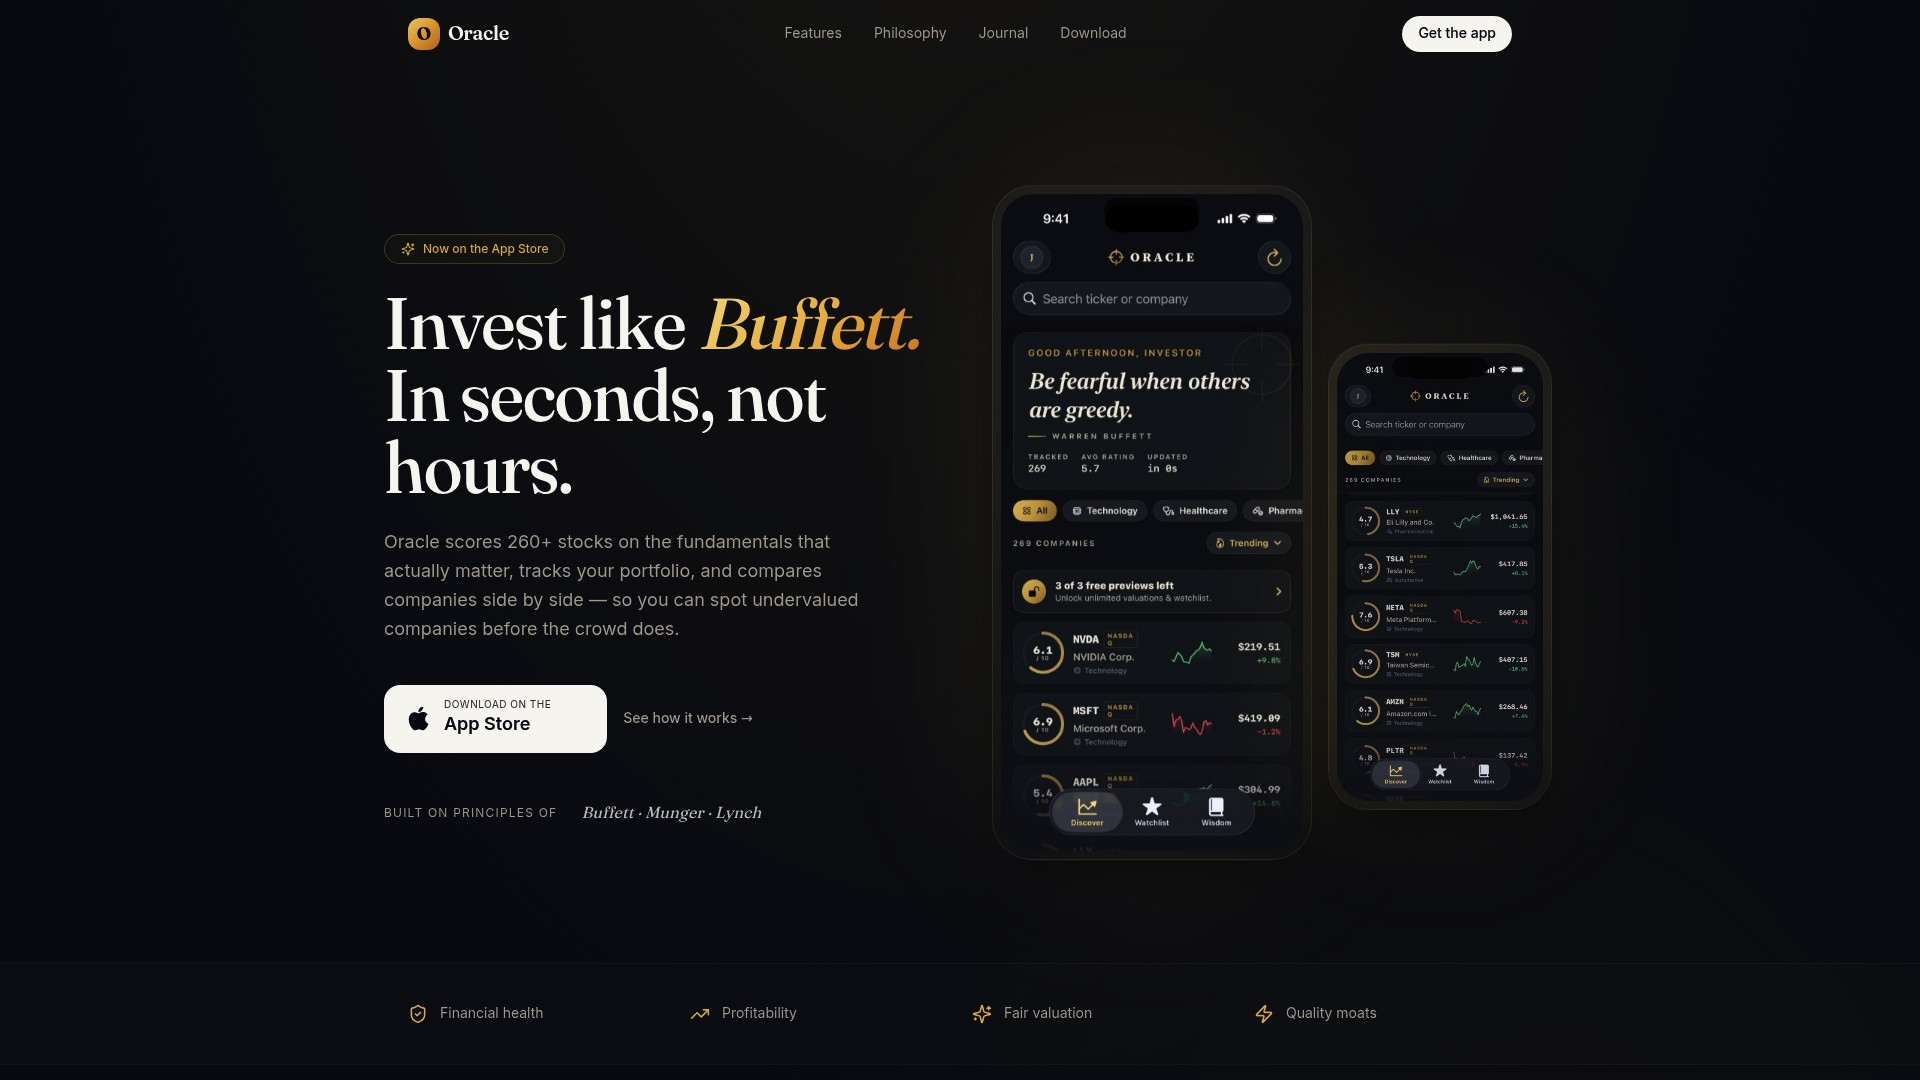
A few features line up directly with the reinvestment decisions covered above:
- Instant side-by-side comparisons help you spot whether a stock you're reinvesting into still stacks up against alternatives.
- Real-time portfolio tracking keeps tabs on how a growing DRIP position shifts your overall allocation.
- Scoring inputs are shown transparently, drawing on value-investing principles from legendary investors, so you can see exactly why a stock rates the way it does.
If you want to check whether your next DRIP candidate holds up on the fundamentals, our Premium Annual plan gives you full access to the scoring and tracking tools.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Is a dividend reinvestment plan a good idea?
A DRIP tends to work well for long-term investors who don't need the cash and want compounding to run automatically. It's less suited to anyone relying on dividend income for near-term expenses or who already has a concentrated position in the stock.
How much does it take to make $1,000 a month in dividends?
The amount needed depends entirely on the dividend yield of the stocks or funds you hold, since a higher-yielding portfolio requires less capital than a lower-yielding one. There's no single dollar figure that applies across all portfolios, so running your own numbers through a dividend or compounding calculator is the most reliable way to estimate it for your specific holdings.
Does Warren Buffett reinvest his dividends?
Berkshire Hathaway's own dividend policy and capital allocation decisions aren't detailed in the sources behind this article, so we can't state a specific answer here. In general, long-term value investors often favor reinvestment when it compounds into companies they already judge to be fundamentally sound.
Is it a good idea to reinvest dividends in retirement?
It depends on whether you need the dividend income to cover living expenses. Retirees who don't need the cash flow yet may still benefit from reinvestment, while those drawing on dividends for income typically take the cash instead.