Position sizing is the decision of how much money goes into each stock, and it usually matters more to your results than which stock you pick. The most dependable approach combines two things: a fixed limit on what any one position can cost you, and a size that scales with how strong the business behind the stock is. This guide gives you the formula, the main methods side by side, and a way to choose one. Along the way it shows where a fundamentals score, such as the ones in our app Oracle Investments, which scores over 260 stocks on profitability, valuation and financial health, fits into the sizing decision.
TL;DR
- Position size is the dollar amount you put into one stock. Set it before you buy, not after the price moves.
- The percent-risk formula is: account size × risk % ÷ (entry price − stop-loss price) = shares to buy.
- Fixed-dollar, equal-weight and percent-risk sizing answer different questions. Pick the one that matches how you hold stocks: long-term investor or active trader.
- Concentration is the real danger. Research on single-stock portfolios shows deep losses become far more likely when one holding dominates.
- Let business quality and valuation decide how big a position can be, and let the risk limit decide the ceiling.
Table of Contents
- What position sizing means for a stock investor
- Why sizing matters more than most investors expect
- The percent-risk formula, step by step
- The main position sizing methods compared
- A note on the 3-5-7 rule
- How to choose a sizing strategy that fits you
- Watch for hidden concentration
- Worked example: sizing a $50,000 portfolio
- Perspective
- Put a score behind your position sizes
- Frequently asked questions
- Sources
What position sizing means for a stock investor
Position sizing answers one question: how many dollars, or what share of your portfolio, goes into this particular stock? It is separate from the question of what to buy. Two investors can own the same stock and have very different outcomes because one put 2% of the portfolio in it and the other put 30%.
The idea has two sides. The first is protection: a sensible size means a single mistake cannot do lasting damage. The second is conviction: a stock you understand well, with strong financials and a reasonable price, deserves more capital than one you are only curious about. Good sizing is how you express both.
It also helps to know that the search results for this topic split into two camps. Active traders size by risk per trade, using a stop-loss price. Long-term investors size by portfolio weight, such as 3%, 5% or 10% per holding. Both are covered below, and most people end up blending them.
Why sizing matters more than most investors expect
Losses and gains are not symmetric. A 50% loss needs a 100% gain to get back to even. The larger the position, the more of your portfolio sits in that arithmetic.
The evidence on concentration is stark. A Cambridge Associates study of concentrated stock portfolios (September 2013) found that replacing a diversified equity allocation with a single stock more than triples the probability of a 25% or larger five-year decline. For a 75% equity, 25% bond portfolio the expected probability was 13%. For the single-stock portfolio it was 41% to 50%. A drop of 50% or more had a 7% to 14% probability, against near zero for the diversified portfolio.

You do not need to hold one stock to feel this. A portfolio of ten stocks where one is 40% of the total behaves a lot like a concentrated bet. Sizing is how you keep that from happening by accident.
It also matters over time. If you are drawing income from a portfolio, an early large loss does more harm than the same loss later. Our guide to sequence of returns risk explains why, and why retirees in particular should treat position limits as a core part of the plan.
The percent-risk formula, step by step
This is the method most traders and many investors use. You decide in advance how much of your account you are willing to lose if you are wrong, then work backward to the number of shares. The steps below follow the Van Tharp Institute position sizing calculator.
- Risk amount = account size × risk percentage. With a $10,000 account and a 1% risk limit, your risk amount is $100.
- Risk per share = entry price − stop-loss price. If you plan to buy at $50 and will exit at $48, you risk $2 per share.
- Position size = risk amount ÷ risk per share. $100 ÷ $2 gives 50 shares.
- Position value = shares × entry price. 50 × $50 is $2,500, or 25% of the account.
Notice what happened. The risk is only 1% of the account, but the position is 25% of it. That is why the formula is useful: the stop-loss distance does the work. A tight stop allows a bigger position. A wide stop forces a smaller one.
Where this method goes wrong
The formula assumes you can actually exit at your stop price. In a fast market, or when a stock gaps down overnight on earnings, the fill can be below your stop, and your loss exceeds the plan. Position value also needs its own cap. A 25% position, as in the example, is a large single-stock exposure, so many people add a rule such as no position above a fixed percentage of the portfolio, whatever the formula says.
The method also fits active trading better than patient investing. A long-term investor who holds a company for years through volatility usually has no precise stop-loss price. For that investor, the better question is how much of the portfolio the business deserves, which brings us to the other methods.
The main position sizing methods compared
These are the approaches you will see most often, with what each is good for.
| Method | How it works | Best suited to | Main weakness |
|---|---|---|---|
| Fixed dollar | Same dollar amount in every position, such as $2,000 | Beginners building a first portfolio | Ignores how risky or how good each stock is |
| Equal weight | Same percentage of portfolio in every holding, such as 5% | Investors holding 15 to 25 stocks | Treats a strong, cheap company the same as a mediocre one |
| Percent risk | Size set by account risk % and stop-loss distance | Active traders and swing traders | Needs a stop price and can understate total exposure |
| Conviction-weighted | Larger positions for stronger, better-priced businesses, within a cap | Value investors and long-term holders | Needs a consistent way to judge quality |
| Kelly-based | Size derived from estimated odds and payoff, then scaled down | Experienced investors comfortable with probability | Inputs are estimates, so results swing widely |
Fixed dollar sizing
You commit the same amount to each purchase. It is simple and removes guesswork, which is why beginners like it. Its limit is that a $2,000 position in a steady, profitable company carries a different risk from $2,000 in a speculative one.
Equal weight
Each holding gets the same slice of the portfolio. With 20 stocks, that is 5% each. It forces diversification and is easy to explain. It does not recognize differences in quality or price, and it drifts as winners grow, so you have to rebalance. Our piece on portfolio drift shows how to spot it and correct it.
Conviction-weighted sizing
This is the method value investors tend to land on. You start with a base weight, say 3% to 5%, and allow a larger weight, up to a hard cap, when a company scores well on profitability and financial health and trades at a reasonable valuation. A weaker business stays at the minimum or does not get bought.
Kelly-based sizing
The Kelly criterion is a formula that turns your estimated odds and payoff into a bet size. Full Kelly is aggressive and very sensitive to errors in your estimates, so practitioners scale it down. We walk through that in Kelly criterion investing for U.S. investors. Treat it as an upper bound that informs your sizing, not a number to follow blindly.
A note on the 3-5-7 rule
You may see "the 3-5-7 rule" mentioned alongside position sizing. It is a popular rule of thumb among traders, not a regulation or a standard, and sources describe the exact percentages differently. If you use it, write down your own version of the numbers: the most you will risk on one position, the most you will have at risk across the whole portfolio, and how you will treat winners. The value is in having limits you set in advance and follow every time.
How to choose a sizing strategy that fits you
Start with how you hold stocks, then with how much a bad outcome would hurt.
If you hold stocks for years. Use conviction-weighted sizing with a hard cap per position. A common structure is a 2% to 3% starter position, a 5% target for stocks you know well, and a 8% to 10% ceiling. Those are example numbers, not a rule: choose a ceiling at which losing the whole position would not change your plans.
If you trade over days or weeks. Use percent-risk sizing with a 0.5% to 1% risk per trade, and add a limit on total open risk across all trades.
If you are in or near retirement. Lower the ceiling per position and prioritize steadier, financially strong companies. Losses early in withdrawals hurt more, so smaller positions and a clear plan for downside matter. Our overview of downside protection strategies covers the options.
If you are a student or beginner. Begin with equal weight. It is easy to run and teaches you how a portfolio behaves before you add judgment about conviction.
Whatever you choose, check the result at the portfolio level. Look at how large your worst plausible loss is across all positions at once, not only per stock. Our portfolio risk assessment workflow is a practical way to do that, and maximum drawdown shows how deep your portfolio has fallen from a peak.

Watch for hidden concentration
Ten positions do not always mean ten independent bets. Five semiconductor stocks, or several companies that depend on the same few customers, tend to fall together. Add up exposure by industry and by theme, not only by ticker.
Customer dependence is a related risk inside a single company. If one customer accounts for a large share of revenue, losing it can hit the stock hard. Our guide to customer concentration risk explains the 10% trigger analysts use and how to read it. A company with that exposure can warrant a smaller position than its valuation alone suggests.
Worked example: sizing a $50,000 portfolio
Say you hold 15 stocks and use conviction-weighted sizing with a 4% base weight and an 8% cap.
| Stock profile | Weight | Dollar amount |
|---|---|---|
| Strong profitability, healthy balance sheet, fair price | 8% | $4,000 |
| Solid business, fully valued | 4% | $2,000 |
| Good business, high debt | 2% | $1,000 |
Suppose you have five stocks in the top group, six in the middle and four in the last. That is 40% + 24% + 8% = 72% invested in those 15, with the remaining 28% in cash or other assets. The cap means the worst single outcome, a full loss on your largest position, costs 8% of the portfolio. You can see the loss and decide in advance whether you can live with it.
Now compare that with the percent-risk approach on the same account. At 1% risk per trade, your risk amount is $500. With a $50 entry and a $45 stop, risk per share is $5, giving 100 shares, or $5,000. That is 10% of the portfolio, above the 8% cap, so the cap wins and you buy 80 shares. Using both rules together, with the stricter one deciding, is a good habit.
Perspective
Most sizing advice is about the math, and the math is the easy part. The hard part is deciding how much a company deserves, and most investors answer that with a feeling.
We built Oracle Investments around a simpler idea. Score companies on reported fundamentals such as profitability, valuation and financial health, show every input, and let the rules produce the rating rather than a model's guess. Once you can see two companies side by side on the same measures, sizing becomes a decision you can explain to yourself: this one earns a full position, that one earns a starter position.
The investors we learn from, Buffett, Munger and Lynch, all treated concentration as a deliberate choice backed by understanding, not as a hunch. Our view is that a clear score gives a beginner the same footing, without spreadsheets or setup.
Matt
Put a score behind your position sizes
Once you have a base weight and a cap, the remaining question is which stocks earn which size. Oracle Investments scores over 260 stocks on profitability, valuation and financial health, lets you compare companies side by side, and tracks your portfolio in real time, so you can see your actual weights next to the scores that justify them. It is a subscription app purchased through the Apple App Store; see the Premium Annual plan for details.
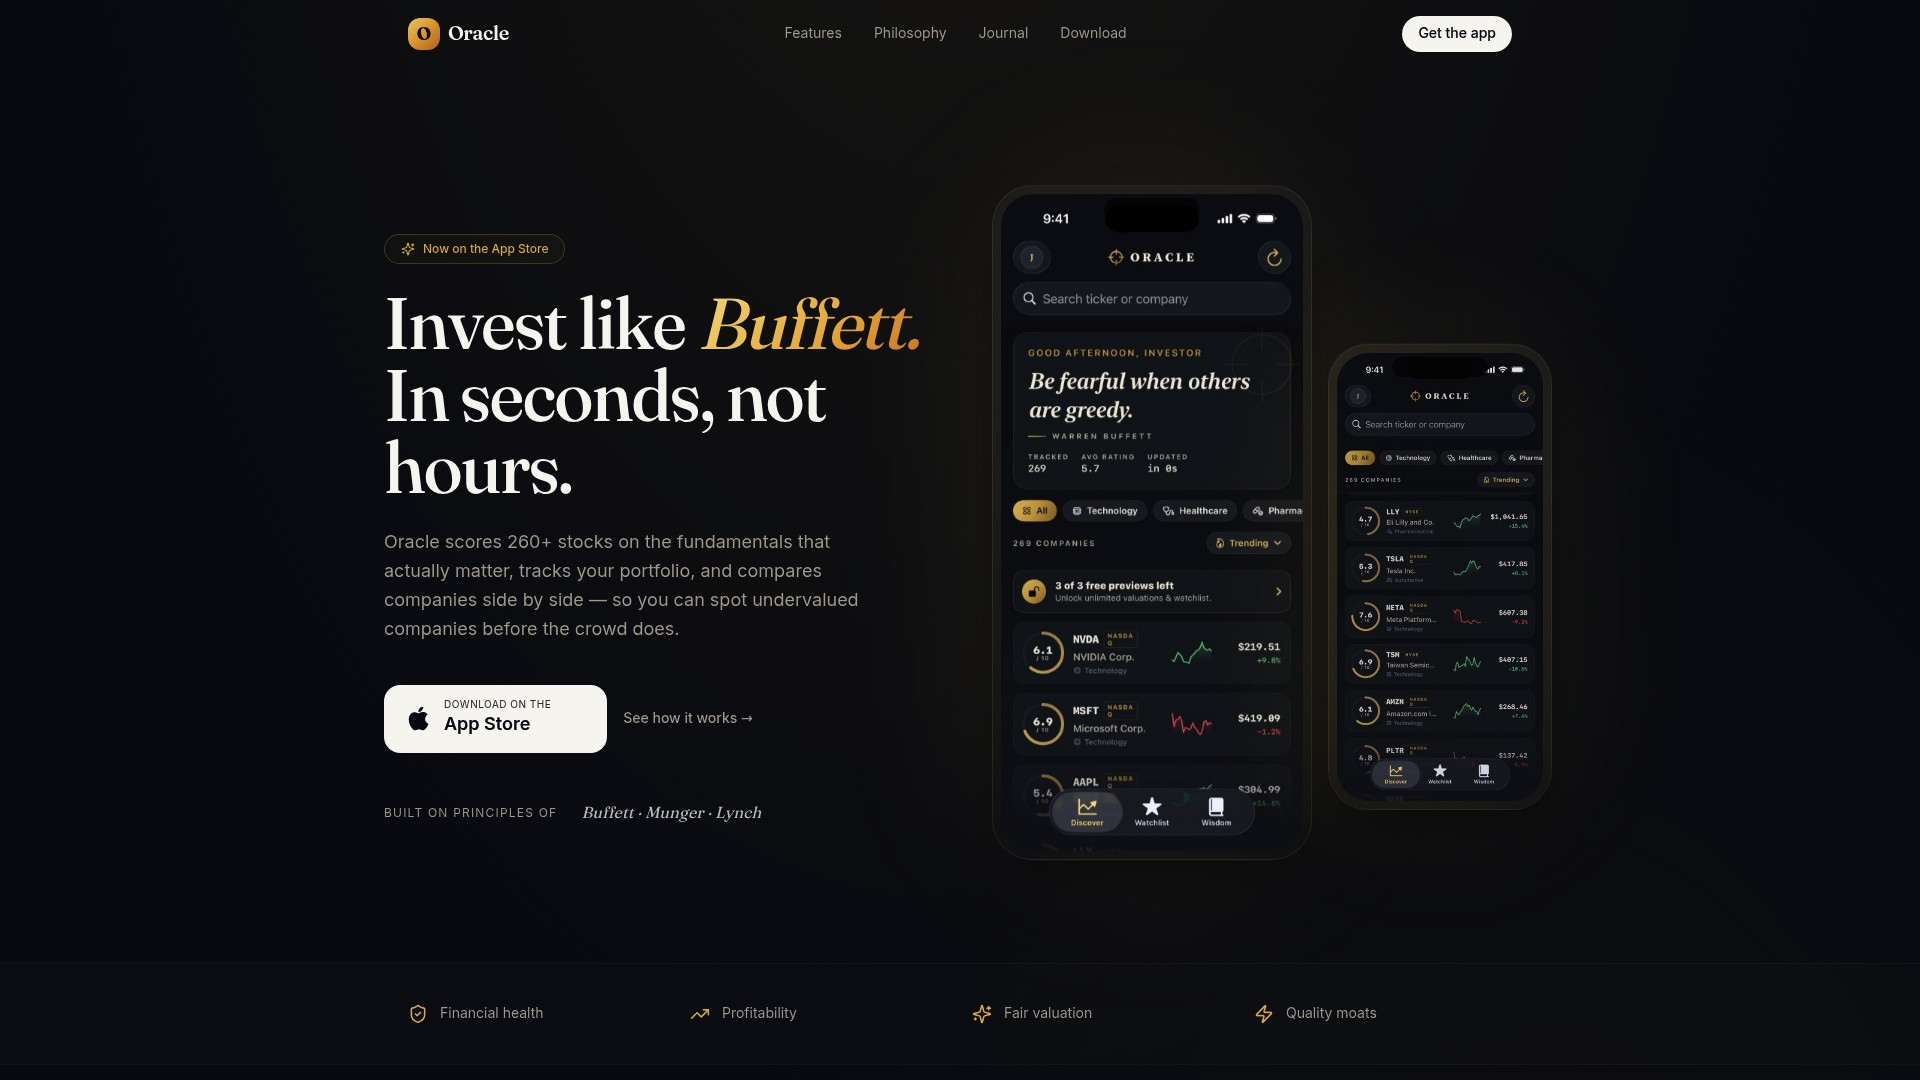
If you also want to see how fast a position size can change as prices move, tracking weights in the app helps you notice when a winner has grown past your cap.
Frequently asked questions
What is the best position sizing strategy?
There is no single best one. Long-term investors do well with conviction-weighted sizing and a hard cap per stock. Active traders usually prefer percent-risk sizing, where a stop-loss sets the share count. Choose the method that matches how long you hold and how much loss you can tolerate.
How do I calculate my position size?
Multiply your account size by the percentage you are willing to risk, then divide by the difference between your entry price and your stop-loss price. With a $10,000 account, 1% risk, a $50 entry and a $48 stop, that is $100 ÷ $2, or 50 shares. Then check that the total position value stays within your cap per stock.
How big should one stock be in a portfolio?
There is no universal number. Many investors use a base of a few percent and a ceiling of roughly 5% to 10% for their strongest ideas. Choose a ceiling where a total loss in one stock would hurt but not change your plans, and consider a lower ceiling if you are drawing income from the portfolio.
Does position sizing work if I only buy and hold?
Yes. Buy-and-hold investors size by portfolio weight instead of stop-loss distance. Set a starting weight, a cap, and a rule to trim when a holding grows past the cap. Reviewing weights periodically keeps one winner from quietly becoming your biggest risk.
Sources
- Concentrated Stock Portfolios, Cambridge Associates (September 2013)
- Free Position Sizing Calculator, Van Tharp Institute