Customer concentration risk is the exposure a business carries when revenue, receivables, or profit depend heavily on one customer or a small group, measured through revenue share and the Herfindahl-Hirschman Index. As a rough trigger, a single customer with about 10% of revenue or a top five with roughly one quarter usually warrant a closer look. The sections below cover measurement, financial impact, and mitigation in that order.
TL;DR:
- Businesses should monitor revenue and receivables concentration separately, especially when a customer’s share exceeds 10% of revenue or 25% of receivables.
- The Herfindahl-Hirschman Index provides a sharper view of concentration, with scores above 2,500 indicating high levels of customer reliance.
- Regular stress testing, such as modeling the loss of a top customer twice a year, helps assess cash flow and valuation impacts effectively.
- Diversification strategies and contractual safeguards are essential for mitigating risks from highly concentrated customer bases.
- Concentration metrics should be integrated into valuation models and reported consistently to ensure timely risk recognition and management action.
Table of Contents
- What customer concentration looks like across a business
- How to measure concentration: share, top-N, and HHI
- Why concentration moves cash flow, valuation, and covenants
- Mitigation playbook for reducing customer concentration
- Monitoring and governance: turning metrics into routine practice
- A worked example you can rebuild in a spreadsheet
- Bringing concentration metrics into a valuation workflow
- When concentration is a problem worth losing sleep over
- Where Oracle Investments fits once you have the numbers
- Sources
- FAQ
What customer concentration looks like across a business
Concentration rarely shows up in just one place. Revenue concentration is the most visible form: a handful of customers generating most of the top line. Accounts receivable concentration is quieter but often more dangerous, since a customer with modest revenue share can still dominate what a company is owed if it pays on long terms. Product, industry, or channel concentration adds another layer: customers that look separate on paper but move together because they sell into the same end market or sit in the same region.
- Revenue concentration: a small number of accounts driving most sales.
- Receivables concentration: a few customers holding most of the outstanding balance.
- Correlated exposure: customers tied to one industry, geography, or distribution channel that can decline together.
Analysts watch all three because each affects cash timing, covenant compliance, and the multiple a buyer will pay, as explained in customer concentration risk.
How to measure concentration: share, top-N, and HHI

Start with percent share: divide each customer's revenue by total revenue for the period. Sum the largest one, three, or five shares to get top-N concentration, the figure most lenders and buyers ask for first.
For a sharper view, calculate the Herfindahl-Hirschman Index. The method comes from antitrust analysis but works just as well on a customer base.
- Convert each customer's revenue into a percentage of total revenue.
- Square each percentage.
- Add the squared values together to get the HHI score.
A business with one customer scores 10,000 on this scale, while a business spread evenly across 100 customers scores 100, according to the Herfindahl-Hirschman Index. The commonly used interpretive bands are below.
| HHI range | Interpretation |
|---|---|
| Below 1,000 | Unconcentrated |
| 1,000 to 2,500 | Moderately concentrated |
| Above 2,500 | Highly concentrated |
Context still matters. A supplier with three large but financially stable customers may carry less practical risk than one with five smaller but volatile accounts. Track revenue share and accounts receivable exposure as two separate numbers rather than assuming they move together.
Why concentration moves cash flow, valuation, and covenants
Losing a large customer rarely just trims revenue. It creates a timing gap, since fixed costs continue while replacement revenue takes time to ramp, and if that customer also carries a large share of accounts receivable, the cash hit lands before the sales loss even shows up on the income statement.
- Cash flow risk: a concentrated customer's slow payment or departure can stall operations faster than the revenue number suggests.
- Valuation impact: buyers and analysts apply multiple compression or a higher discount rate when one account can swing results.
- Covenant risk: lenders may treat a concentrated customer base as a red flag during a borrowing base review.
- Disclosure obligations: public filers often name specific customer percentages, as seen in one SEC filing reporting individual shares between roughly 12% and 25.9%, with cases where two customers made up 40% of gross accounts receivable.
That gap between revenue concentration and receivables concentration is exactly why replacement assumptions need separate modeling for timing and margin.
Mitigation playbook for reducing customer concentration
Fixing concentration takes more than adding logos. The sequence below moves from slower, structural fixes to faster financial backstops.
- Diversify demand sources: target new segments or geographies rather than similar customers in the same risk pool.
- Set contract minimums and termination notice periods so a loss is telegraphed, not sudden.
- Negotiate credit limits on your largest accounts rather than extending terms by default.
- Consider trade-credit insurance or receivables financing to cap the downside on a single account.
- Strengthen the relationship and cross-sell where the account is healthy, since retention is cheaper than replacement.
- Write a contingency plan naming an owner, a trigger level, and the first three actions to take if a top customer leaves.
This mirrors investor-level advice: diversification and periodic rebalancing are the foundational controls against concentration, according to FINRA, and the operating-company version is simply deliberate customer diversification paired with regular review. Mitigation also works best as a combined set of actions rather than any single lever, per guidance from Allianz Trade.
Pro Tip: Model the loss of your largest customer twice a year, once assuming a fast replacement and once assuming a six-month gap, and compare the cash impact.
Monitoring and governance: turning metrics into routine practice
Measurement only helps if someone checks it on a schedule. A workable KPI set includes top-1 and top-5 revenue share, HHI, the percentage of gross accounts receivable tied to your largest customers, and days sales outstanding for those same accounts.
- Run quarterly stress tests simulating the loss of your top one or two customers.
- Set trigger levels, such as top-1 share crossing 10% or HHI rising sharply month over month, each with a named owner.
- Track KPIs monthly and summarize them for the board quarterly.
- Disclose material concentration to lenders or investors before a covenant test or financing round, not after.
A documented portfolio risk assessment workflow helps keep this cadence consistent rather than reactive.
A worked example you can rebuild in a spreadsheet
Here is a simplified twelve-month example using five anonymized customers and $1,000,000 in total revenue.
- List each customer's trailing twelve-month revenue.
- Divide by total revenue to get percent share.
- Square each percentage.
- Sum the squares for the HHI score.
Summing the squared column gives an HHI of 2,300, which falls in the moderately concentrated band. Model receivables separately using the same structure applied to outstanding balances instead of revenue, since a customer with long payment terms can dominate accounts receivable even with a modest revenue share. A simple template with columns for customer name, revenue, percent share, squared share, and a running HHI total covers most of what this exercise needs. For scenario testing, pair it with a fundamental analysis checklist when updating valuation assumptions after a stress test.
Bringing concentration metrics into a valuation workflow
Concentration findings should feed directly into the discount rate and scenario cash flows used in valuation, not sit in a separate risk memo. A business with HHI above 2,500 typically deserves a higher required return and a wider range of downside cash flow scenarios than one with the same revenue but broader distribution.

In practice, that means pulling concentration figures alongside profitability and balance sheet data when scoring a company, then revisiting both after any material customer change. A fundamentals-first scoring approach can be used across many stocks, making it straightforward to re-score a holding after a concentration event and see the valuation shift directly. Reviewing this quarterly, tied to earnings releases, keeps the exercise from going stale.
When concentration is a problem worth losing sleep over
Concentration is tolerable when contracts are multi-year, margins are strong, and a credible replacement pipeline exists. It demands immediate action when a single customer holds outsized accounts receivable, shows signs of nonrenewal, or pushes you near a covenant breach. Triage in that order: check receivables exposure first, confirm contract terms second, and model the cash gap third.
— Matt
Where Oracle Investments fits once you have the numbers
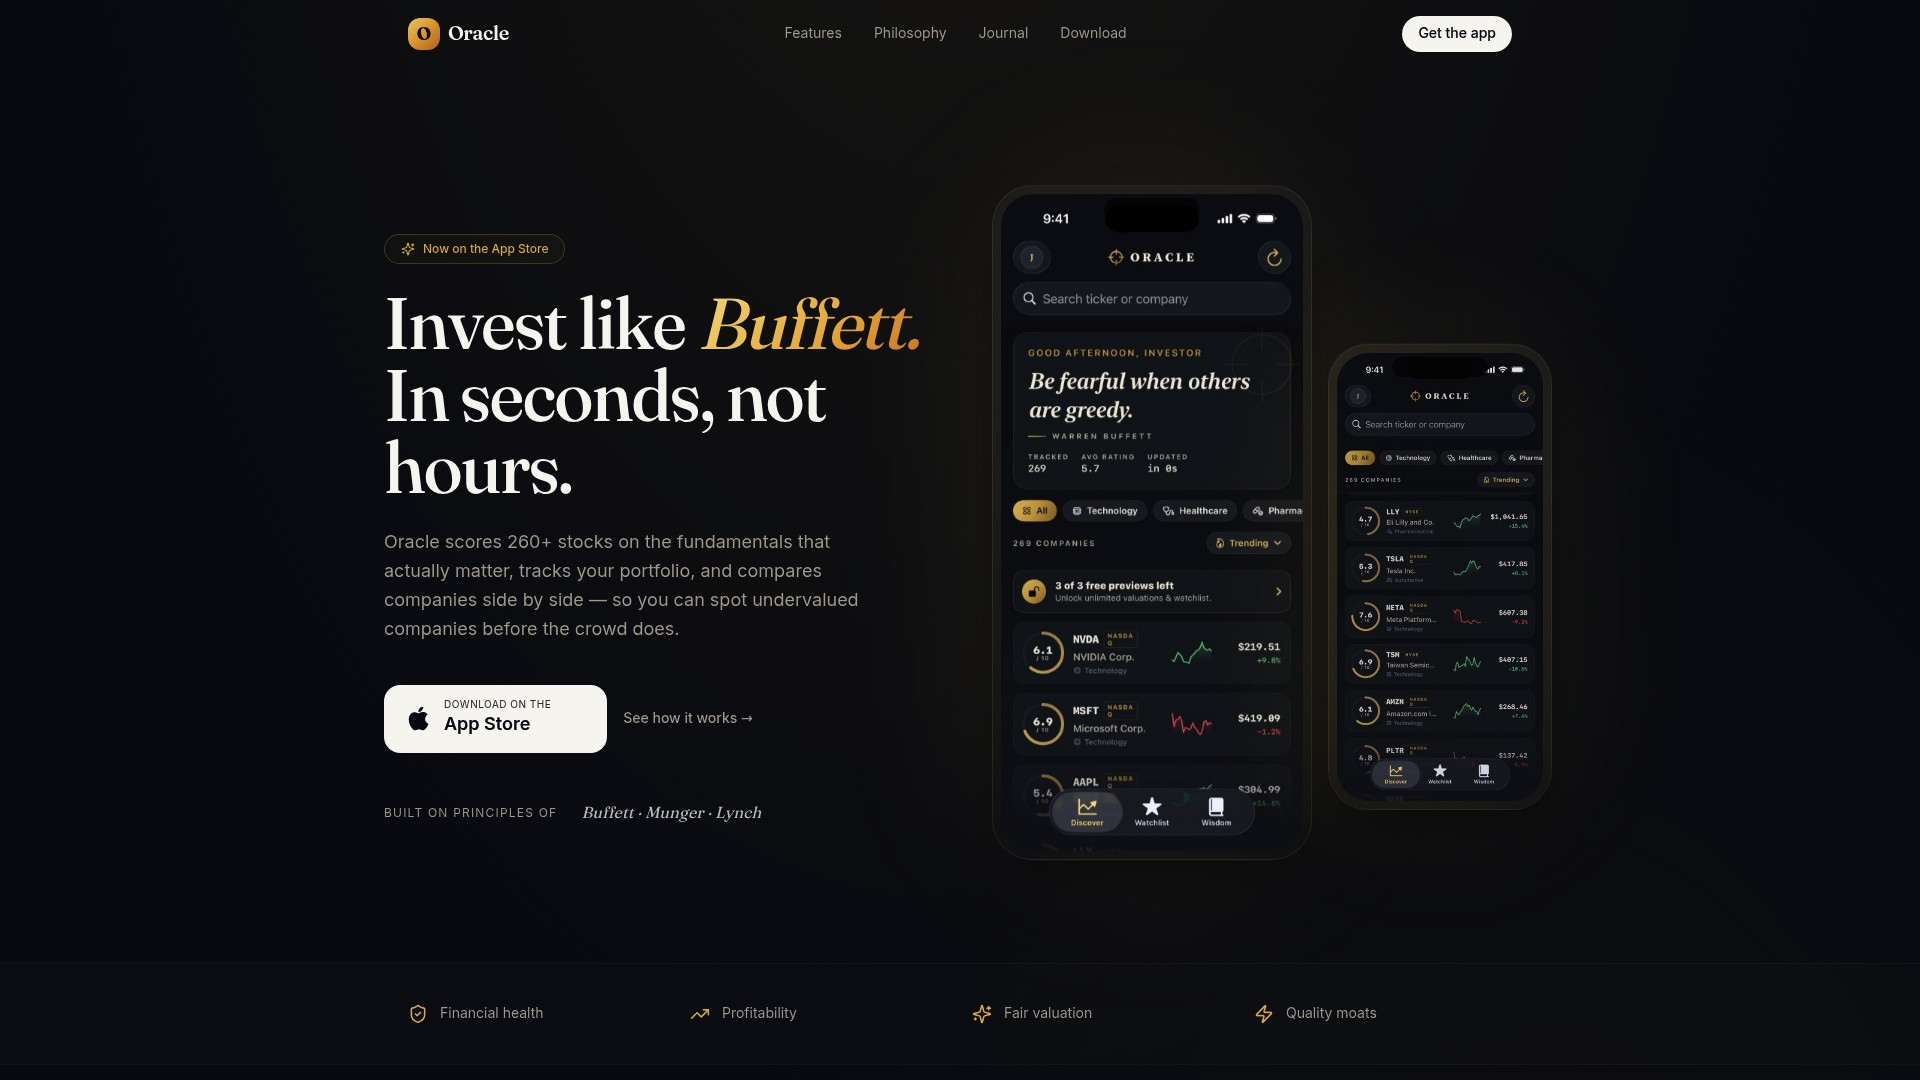
Running the formulas above tells you how concentrated a business is. Oracle Investments helps you watch what that concentration does to the underlying fundamentals over time, with real-time portfolio tracking and instant side-by-side comparisons across more than 260 scored stocks.
- Transparent, rule-based scoring inputs you can trace back to reported fundamentals.
- Side-by-side comparisons to see how a concentration event changes a company's standing against peers.
- Built as an analytics and tracking aid, not a substitute for bespoke advisory work on a specific holding.
Readers who want a faster way to monitor these shifts can check Premium Annual for the full feature set.
Sources
- Customer Concentration: Definition and Risk | CFI
- Herfindahl-Hirschman Index | U.S. Department of Justice Antitrust Division
- SEC filing example: customer concentration note
- Concentration risk guidance | FINRA
FAQ
What is an example of concentration risk?
A common example is a supplier that generates a very large portion of its revenue from one retail chain; if that retailer switches vendors, the supplier loses a significant portion of its sales at once. Another form shows up in SEC filings, where two customers accounted for 40% of a company's gross accounts receivable.
What does concentration risk mean?
Concentration risk means too much exposure, whether revenue, receivables, or reliance, rests with one counterparty or a small cluster of them. The term applies to customers, suppliers, industries, or geographies, and it matters because losing that one source causes outsized damage, per CFI.
What do you mean by customer concentration?
Customer concentration specifically refers to how much of a business's revenue, profit, or receivables comes from its largest customers rather than being spread across many accounts. It is typically measured using percent revenue share, top-N totals, or the Herfindahl-Hirschman Index.
What is concentration risk in simple terms?
In simple terms, it is the danger of relying too heavily on too few sources, whether that is customers, suppliers, or markets. A rule of thumb used by credit and trade groups flags a single customer above 10% of revenue or a top five above 25% as worth a closer look.
How often should a business check its concentration risk?
Most practitioners track revenue share and HHI monthly and summarize the trend for leadership or the board on a quarterly basis. Stress tests simulating the loss of a top customer are typically run quarterly or whenever a major account shows signs of instability.