Maximum drawdown measures the worst peak-to-trough percentage loss a portfolio or investment has suffered over a given period, and it matters because it shows the deepest hole an investor would have had to climb out of. Unlike volatility, it captures a single, real experience of loss rather than an average of ups and downs. You calculate it from a price or net asset value series by tracking the largest decline from any running high point.
TL;DR:
- For return data, compound each period from a base value, track the running high, and take the largest percentage decline; Excel uses three columns.
- In the six month example, the deepest decline was 19.6% from $112 to $90, and the portfolio had not regained its peak by month six.
- Daily data often produces a larger drawdown than monthly data because monthly sampling smooths short lived declines; keep frequency consistent when comparing portfolios.
- No universal acceptable figure exists: risk tolerance, time horizon, and allocation shape the tradeoff between limiting losses and pursuing returns.
- Maximum drawdown depends on the chosen sample and ignores smaller losses, so pair it with recovery time and how often lesser declines occur.
Table of Contents
- What Does Maximum Drawdown Actually Measure?
- How Do You Calculate Maximum Drawdown Step by Step?
- A Worked Example: Calculating Drawdown From Real Numbers
- What Counts as a Good Maximum Drawdown?
- How Do You Actually Compute This for Your Own Portfolio?
- Where Maximum Drawdown Falls Short
- Why Real-Time Drawdown Monitoring Changes the Decision
- Tracking Downside Risk With Oracle Investments
- FAQ
- Sources
What Does Maximum Drawdown Actually Measure?
Maximum drawdown is measured from a running peak, not from a portfolio's all-time high or low. Every time your portfolio hits a new high, that becomes the new reference point for measuring the next decline. This matters because a portfolio can fall sharply from an earlier peak, recover partway, then fall again from a lower peak, and the drawdown calculation needs to track each of those episodes correctly.
Two dimensions define the experience: magnitude and duration.
- Magnitude tells you how deep the decline went, expressed as a percentage drop from peak value.
- Duration tells you how long the portfolio stayed underwater before recovering, which shapes how painful the drawdown actually felt.
This is also why maximum drawdown differs fundamentally from standard deviation. Volatility treats a sharp rally and a sharp decline as symmetrical risks, while drawdown only counts the downside and depends entirely on the order in which gains and losses occurred, a property researchers call path dependence.
How Do You Calculate Maximum Drawdown Step by Step?
The formula is straightforward once you have a price or net asset value series. At each point in time, you track the running peak value, then measure how far the current value has fallen from that peak.
The drawdown at any time t is:
D(t) = (P(t) − V(t)) / P(t)
where P(t) is the highest value reached up to time t, and V(t) is the current value. Maximum drawdown is simply the largest D(t) across the whole series.
To calculate it from a return series rather than prices, follow these steps:
- Convert returns into a cumulative value series by compounding each period's return onto the previous value, starting from an arbitrary base like 100 or 1.
- Track the running maximum of that value series as you move forward in time.
- At each point, calculate the percentage drawdown as (running peak minus current value) divided by running peak.
- Take the maximum of all those drawdown percentages. That number is your maximum drawdown.
This runs in a single pass through the data, which makes it cheap to compute even for long daily histories. In Excel, the same logic becomes three columns: a running MAX of the value series, a drawdown percentage column, and a final MAX of that drawdown column.
Pro Tip: Keep your running peak and drawdown calculations in separate columns rather than nesting them in one formula. It makes errors easy to spot and the sheet easy to reuse for a different holding.
A Worked Example: Calculating Drawdown From Real Numbers
Say a portfolio's value over six months looks like this: $100, $112, $105, $90, $96, $108.
- The running peak starts at $100, rises to $112 in month 2, and stays at $112 through month 5 since no later value exceeds it until month 6.
- Drawdown at month 3 is (112 − 105) / 112, about 6.3%. At month 4 it widens to (112 − 90) / 112, about 19.6%, the deepest point in this series.
- Month 5 at $96 is still a drawdown of about 14.3%, and by month 6 the portfolio hits $108, a new value but still below the $112 peak, so technically the drawdown has not fully recovered within this sample.
In Excel, column B would hold the values, column C a running =MAX($B$2:B2), column D the drawdown as =(C2-B2)/C2, and a single cell =MAX(D2:D7) returns the
What Counts as a Good Maximum Drawdown?
There is no universal benchmark for a good maximum drawdown. What counts as acceptable depends on an investor's risk tolerance, time horizon, and how the portfolio is allocated across asset classes, a point the SEC's guidance on diversification makes directly when discussing how rebalancing and allocation choices trade off risk against return.
Historical market episodes give useful anchors for what "deep" looks like in practice.
The Great Depression produced one of the most severe maximum drawdowns in U.S. equities on record, while the 2007 to 2009 financial crisis and the 2020 pandemic crash were sharp but shallower by comparison. These episodes show why drawdown figures only mean something alongside the time horizon an investor is working with.

How Do You Actually Compute This for Your Own Portfolio?
You do not need specialized software to calculate maximum drawdown. A spreadsheet or a free online calculator both work, as long as you feed in the right data.
- In Excel, build the three-column pattern: a running maximum of your value series, a drawdown percentage for each period, then a single
MAX()formula over the drawdown column. - For free online calculators, paste in your price or net asset value history in chronological order. Most tools then report the peak date, trough date, drawdown percentage, and whether and when recovery occurred.
- Data frequency changes the result: daily price data captures intraday-level swings that monthly data smooths over, so a portfolio's calculated drawdown is often larger when measured daily than when measured monthly, even over the same stretch of time.
If you trade or invest through an account with explicit daily risk rules, the mechanics are similar but mechanical: some funded futures programs, for instance, define a simple end-of-day drawdown limit that does not trail your gains upward, which is one practical way drawdown limits get built directly into account rules rather than just measured after the fact.
Where Maximum Drawdown Falls Short
Maximum drawdown has real limitations that matter for how you use it. It is a single historical episode, not a probability.
- MDD is entirely sample-dependent: extend or shorten the history you examine and the number changes, sometimes substantially.
- It captures only the worst single episode, discarding information about how frequently smaller drawdowns occurred.
- It offers no forward-looking recurrence probability on its own.
Researchers have proposed more complete alternatives. Conditional Expected Drawdown (CED) takes the tail mean of the full distribution of maximum drawdowns rather than a single worst case, and it is built to be convex, which makes it usable directly in portfolio optimization. It also tends to handle serially correlated returns, where losses cluster together, better than volatility-based measures do. For most individual investors, pairing a straightforward maximum drawdown figure with its recovery time and a rough sense of how often smaller drawdowns have occurred gives a fuller picture than the single number alone, even without running a full CED calculation.
Why Real-Time Drawdown Monitoring Changes the Decision
A maximum drawdown calculated once a year tells you what already happened. Checking it regularly, alongside current drawdown from the latest peak and whether the portfolio has recovered, tells you what is happening now and gives you time to act before a small decline becomes a large one.
A useful tracker shows current drawdown percentage, the date of the peak it is measured from, the trough if one has occurred, and recovery status, ideally across several trailing windows rather than just one. We built real-time portfolio tracking with exactly this kind of ongoing visibility in mind, letting you see how your holdings are performing against their own recent highs rather than waiting for a quarterly statement to find out.

Tracking Downside Risk With Oracle Investments
We designed our app around the idea that spotting rising risk early matters more than analyzing it after the fact. Our real-time portfolio tracking shows how each holding is moving relative to its own recent peak, and our instant comparison tools let you line up multiple positions side by side to see where drawdown risk is concentrating.
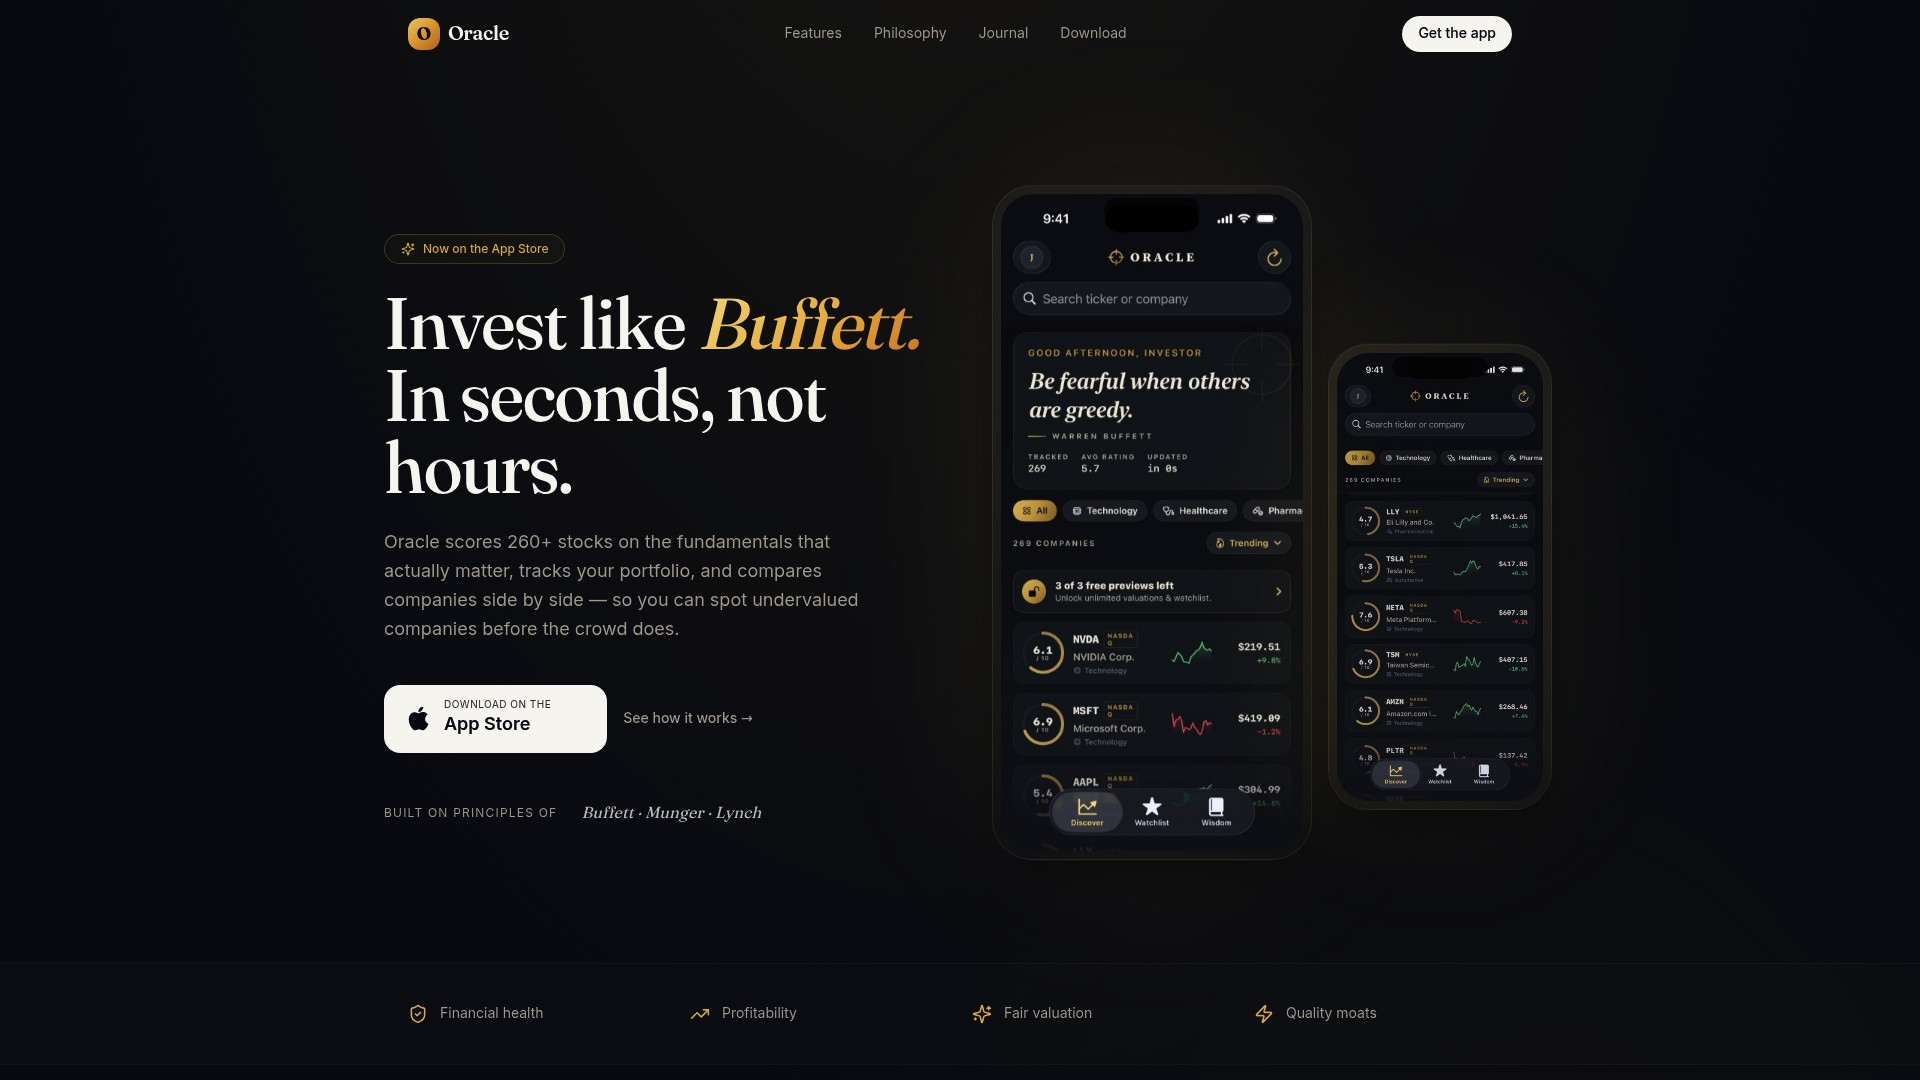
- Real-time tracking surfaces a widening drawdown in a specific holding before it shows up in a monthly statement.
- Instant side-by-side comparisons help you judge whether a declining position still fits your allocation or deserves rebalancing.
- Transparent scoring inputs mean you can see exactly which fundamentals are driving a stock's rating, not just the score itself.
If you want a practical way to watch for rising drawdowns and compare holdings while deciding whether to rebalance, our Premium Annual plan gives you that visibility in one place.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the meaning of maximum drawdown?
Maximum drawdown is the largest percentage decline a portfolio or investment experienced from a previous peak value to its lowest point before recovering. It is measured purely peak to trough, not from an average or a starting value, which makes it a direct gauge of the worst loss an investor actually lived through.
What is a good max drawdown?
There is no single figure that counts as good for every investor. What is acceptable depends on your time horizon, risk tolerance, and asset allocation, and the SEC's guidance on diversification frames this as a direct trade-off between limiting losses and the returns you give up by doing so.
How do you calculate max drawdown?
You track the running peak of a price or value series, then measure the percentage drop from that peak at every later point, and the maximum drawdown is the largest of those percentage drops. In Excel, this is a running MAX column, a drawdown percentage column, and a final MAX formula over that column.
What is the maximum drawdown of the S&P 500?
The S&P 500's deepest historical drawdown occurred during the Great Depression, when it fell by roughly 86% from peak to trough, a far larger decline than the drops seen in the 2007 to 2009 financial crisis or the 2020 pandemic crash. The exact figure depends on the data frequency and period used for the calculation.
Sources
- SEC: Diversifying risk and asset allocation (investor guidance)
- Drawdowns: practical relevance (University researchers)