Spinoff investing means buying shares of a company that a parent has separated into its own publicly traded business, or the parent left behind, because the market may misprice one or both after the split. You find deals through SEC filings and company announcements, and you judge them by reading the registration statement and comparing both companies' financials. The evidence says spin-offs are not a guaranteed edge, so treat each one as a stock you have to earn a view on.
TL;DR
- A spin-off distributes shares of a new public company to the parent's existing shareholders, usually pro rata, and the parent's share price adjusts lower afterward.
- Announcements show up first in press releases, investor relations pages and SEC registration statements (Form 10 or Form 10-12B) on EDGAR.
- Selling pressure from funds whose mandates do not fit the new company can create temporary mispricing, but it can also signal a weak business.
- Research is mixed: one large study of big separations found a median combined excess return of -1.1 percent. Spin-offs are not a predictor of higher returns.
- Read the information statement, compare pro forma debt and returns on capital for both companies, and check the tax treatment before you act.
Table of Contents
- What a spin-off is and how you end up with shares
- Why companies spin off units
- Why spin-offs can be mispriced
- What the evidence says about returns
- How to find spin-offs before and after they trade
- How to analyze a spin-off and the parent left behind
- Taxes: read the language before you sell
- Mistakes that cost spin-off investors money
- A practical checklist
- Our perspective
- Put the fundamentals to work with Oracle
- FAQ
- Sources
What a spin-off is and how you end up with shares
In a spin-off, a publicly traded company separates a business unit into an independent, publicly traded company. It does this by distributing the new company's shares to its own shareholders. According to FINRA's investor guidance on corporate spinoffs, the distribution is typically pro rata: you receive a set number of new shares for each share of the parent you hold.
A simple example makes this concrete. Say a parent announces one new share for every four shares held. If you own 100 parent shares on the record date, you receive 25 shares of the new company. You pay nothing at the time, and your brokerage account simply shows a new position.
Two mechanical points matter on the first day of trading:
- The parent's price drops. FINRA notes that once the spin-off begins trading, the parent's share price is adjusted lower because its valuation no longer includes the separated unit. That is arithmetic, not a loss. Your combined position should be worth roughly what the old one was, before the market starts repricing both.
- Fractional shares become cash. When your ratio does not divide evenly, the distribution agent typically aggregates fractional shares, sells them in the open market and sends the net cash to the eligible holders. An SEC Form 8-K from a January 2025 separation describes exactly this process. That cash can be taxable even when the rest of the distribution is not.
If you hold shares across borders or expect to pass a portfolio to heirs abroad, it is worth knowing how newly distributed positions fit into an estate. For one example of the issues, see this overview of share inheritance in Singapore.
Why companies spin off units
The usual reason is focus. FINRA describes the main strategic rationale as letting the parent's management concentrate on core operations while the new company gets the autonomy to pursue a different growth path. A 2025 spin-off guide from a law firm makes a similar point: spin-offs let companies monetize non-core assets and sharpen the focus of what remains.
For you as an investor, the stated reason is a clue, not a conclusion. Ask three questions:
- Is the unit being separated because it is strong or because it is a drag? A parent that wants to get rid of a slow-growth, debt-heavy business is different from one that wants a high-growth unit to be valued on its own merits.
- Did the unit already run itself? FINRA points out that the transition can be smoother for subsidiaries that already enjoyed substantial autonomy before the spin-off. A division that shared systems, suppliers and management with the parent has more to rebuild.
- Who gets the debt? Parents sometimes load the new company with debt before the separation and take the cash. That shows up in the pro forma balance sheet, which we cover below.
Why spin-offs can be mispriced
The appeal of spinoff investing rests on a plausible mechanism. Shares land in the accounts of people who never chose to own the new company. Investopedia's guide to buying and selling parents and spin-offs explains that institutional investors often sell spin-off shares shortly after distribution when the new company does not fit their mandate, for example because it is a small cap or pays no dividend. An index fund may also have to sell if the new company is not in its index. That selling can push the price down for reasons unrelated to the business.
That is the opening, but it is not a promise. Forced selling ends, and then the price depends on the company's actual prospects. The same source lists the risks that can make spin-offs underperform: volatility, business disruption, lost synergies and a failure to create value at all.
A practical consequence: do not buy on day one just because a price has fallen. Wait until you understand the business, and be prepared to wait through the selling period if the thesis holds.

What the evidence says about returns
The popular claim is that spin-offs beat the market. The research is more cautious.
- A McKinsey analysis of large spin-offs and separations found that 55 percent of large spin-offs had negative weighted-average total shareholder returns for both companies three years after separation. The median combined excess return was -1.1 percent for large corporate spin-offs from 2000 to 2022. It was +5.1 percent in 2000 to 2009 and -4.4 percent since 2010.
- Older academic work points somewhere else for the source of gains. A 1993 study of spin-offs from 1965 to 1988 associated superior long-term performance with takeover activity within three years of the separation. In other words, part of the historical outperformance came from companies that were later acquired.
- Investopedia summarizes the picture as mixed: some studies show long-term underperformance, while others suggest the best separations can substantially increase shareholder value.
The McKinsey piece also says value comes from higher returns on invested capital, through faster growth, better margins and smarter capital allocation. That is a useful filter. A spin-off is only attractive if you can point to one of those three things and explain why the separation makes it more likely.
The takeaway: the category does not do the work for you. Individual selection does.
How to find spin-offs before and after they trade
The people searching for how to find spinoffs usually want a list. There is no single official calendar, but there is a reliable process.
Watch SEC filings on EDGAR
The 2025 spin-off guide referenced above points investors to SEC filings on the EDGAR database, specifically Form 10-12B or Form 10 registration statements, to identify announced deals. A public company issuing new stock through a spin-off files one, and Investopedia's explainer on Form 10-12B notes it includes pro forma financial statements and the new company's industry outlook.

On EDGAR, search by form type and sort by filing date. Amended filings are common as the deal approaches, and each amendment can contain new details on debt, management and the distribution ratio.
Follow press releases and investor relations pages
Corporate press releases and investor relations websites are the other primary source for announcements about upcoming separations. Companies often hint at a review of strategic alternatives in earnings calls well before a formal announcement. If you own a conglomerate or a company with several distinct segments, reading its quarterly segment disclosures tells you which units might be candidates. Our guide to segment reporting analysis shows how to read those tests.
Check your own brokerage account
If you already hold a parent, the broker will notify you of corporate actions, including the record date, distribution date and ratio. Keep those notices for your tax records.
Build a simple tracking routine
A routine that takes 15 minutes a week is enough:
- Search EDGAR for new Form 10 and Form 10-12B filings.
- Scan press releases from companies you follow for words like "separation", "spin-off" and "distribution".
- For each candidate, save the information statement and note the expected timing.
- After trading begins, record the first-week price range and revisit after the first two earnings reports.
How to analyze a spin-off and the parent left behind
Every spin-off creates two investments, and the second one gets overlooked. Investopedia's guidance is to compare the pro forma balance sheets and income statements of both companies, checking debt, other liabilities and return on capital employed, and to assess the reason for the separation.
Read the information statement
The Form 10-12B filing includes an information statement. Read these parts first:
- Reasons for the separation, which tell you what management says it is fixing.
- Pro forma financials, which show what each company would have looked like on a standalone basis.
- Business description and risk factors, which list customer concentration, dependence on the former parent and one-time costs.
- Agreements with the parent, such as transition services, supply contracts and tax-sharing arrangements.
Compare both sides
| What to check | Spin-off | Parent |
|---|---|---|
| Debt after separation | How much was assigned, and at what rate | Whether it kept or shed leverage |
| Return on capital employed | Standalone, not blended | Without the lost unit |
| Growth and margins | Does independence change either | Does focus change either |
| Capital allocation | Dividend, buyback or reinvestment plan | Use of any cash received |
| Management incentives | Equity ownership and pay targets | Same |
Capital allocation deserves special attention. A new company that starts buying back shares or paying a dividend sends a different signal than one that needs cash to survive. Our pieces on share buybacks versus dividends and shareholder yield explain how to weigh those choices. If the spin-off issues stock-based pay or equity to fund itself, check dilution too.
Ask whether the price already reflects the news
Once you have a view on business quality, compare it to price. Our method for owner earnings gives you a conservative cash-based earnings figure you can use to judge what you are paying, rather than relying on reported net income that may include separation costs.
Taxes: read the language before you sell
Many spin-offs are structured to be tax-free to shareholders for U.S. federal income purposes, but that is stated deal by deal. For example, a Vista Outdoor press release said the distribution was expected to be tax-free to its stockholders for U.S. federal income tax purposes, except for cash received in lieu of fractional shares.
The other piece is cost basis. In a 2002 SWS Group filing, stockholders were told their aggregate basis in the old and new shares would be allocated between them in proportion to fair market values on the spin-off date. The exact method differs by deal, so the company's own tax disclosure is the document to follow. If you are unsure how it applies to your lots, ask a CPA or enrolled agent before selling either position.
Mistakes that cost spin-off investors money
- Assuming the label is the edge. The category is not a predictor of higher returns, as the research above shows.
- Ignoring the parent. Sometimes the better investment is the company left behind, now simpler and more profitable.
- Buying into forced selling too early. A falling price after distribution can keep falling. Size the first purchase small.
- Skipping the debt. Check how much the new company owes, and when it comes due.
- Forgetting the exit. Know what would make you sell: a missed target, a dividend cut or a rising debt load.
- Overlooking holding-period risk. If you plan to rely on a position for retirement income, the order of returns matters. See sequence of returns risk.
A practical checklist
- Confirm the ratio, record date and distribution date from the company's announcement or your broker.
- Download the Form 10 or 10-12B and read the information statement.
- Compare both companies' pro forma debt, margins and return on capital.
- Note who is being forced to sell and when that pressure is likely to ease.
- Decide what you would pay for each business on its own.
- Review the tax disclosure and keep your basis records.
- Start small, and revisit after the first two earnings reports.
Our perspective
Spin-offs are a good reminder that investing is a discipline of reading, not guessing. A separation creates two new sets of financial statements, and the answer to whether either company is cheap sits in the numbers: profitability, valuation and financial health.
That is how we built Oracle. Our ratings are rule-based and grounded in reported company fundamentals, and we show every scoring input so you can see exactly why a company scores the way it does. We avoid AI or model-driven guesswork, because when you evaluate a newly separated company you need to trust the logic.
The value investors we learned from, such as Warren Buffett, Charlie Munger and Peter Lynch, all shared one habit: they did the homework before the story. In practice that means scoring a company on its fundamentals and comparing it side by side with its peers. We designed Oracle to make that routine quick, without spreadsheets or setup.
Matt
Put the fundamentals to work with Oracle
Once you have found a spin-off or a parent worth studying, you need a fast way to see whether its fundamentals hold up. Oracle Investments scores over 260 stocks on profitability, valuation and financial health, lets you compare companies side by side and shows the inputs behind each score. You can also track your portfolio in real time, including positions you received in a distribution.
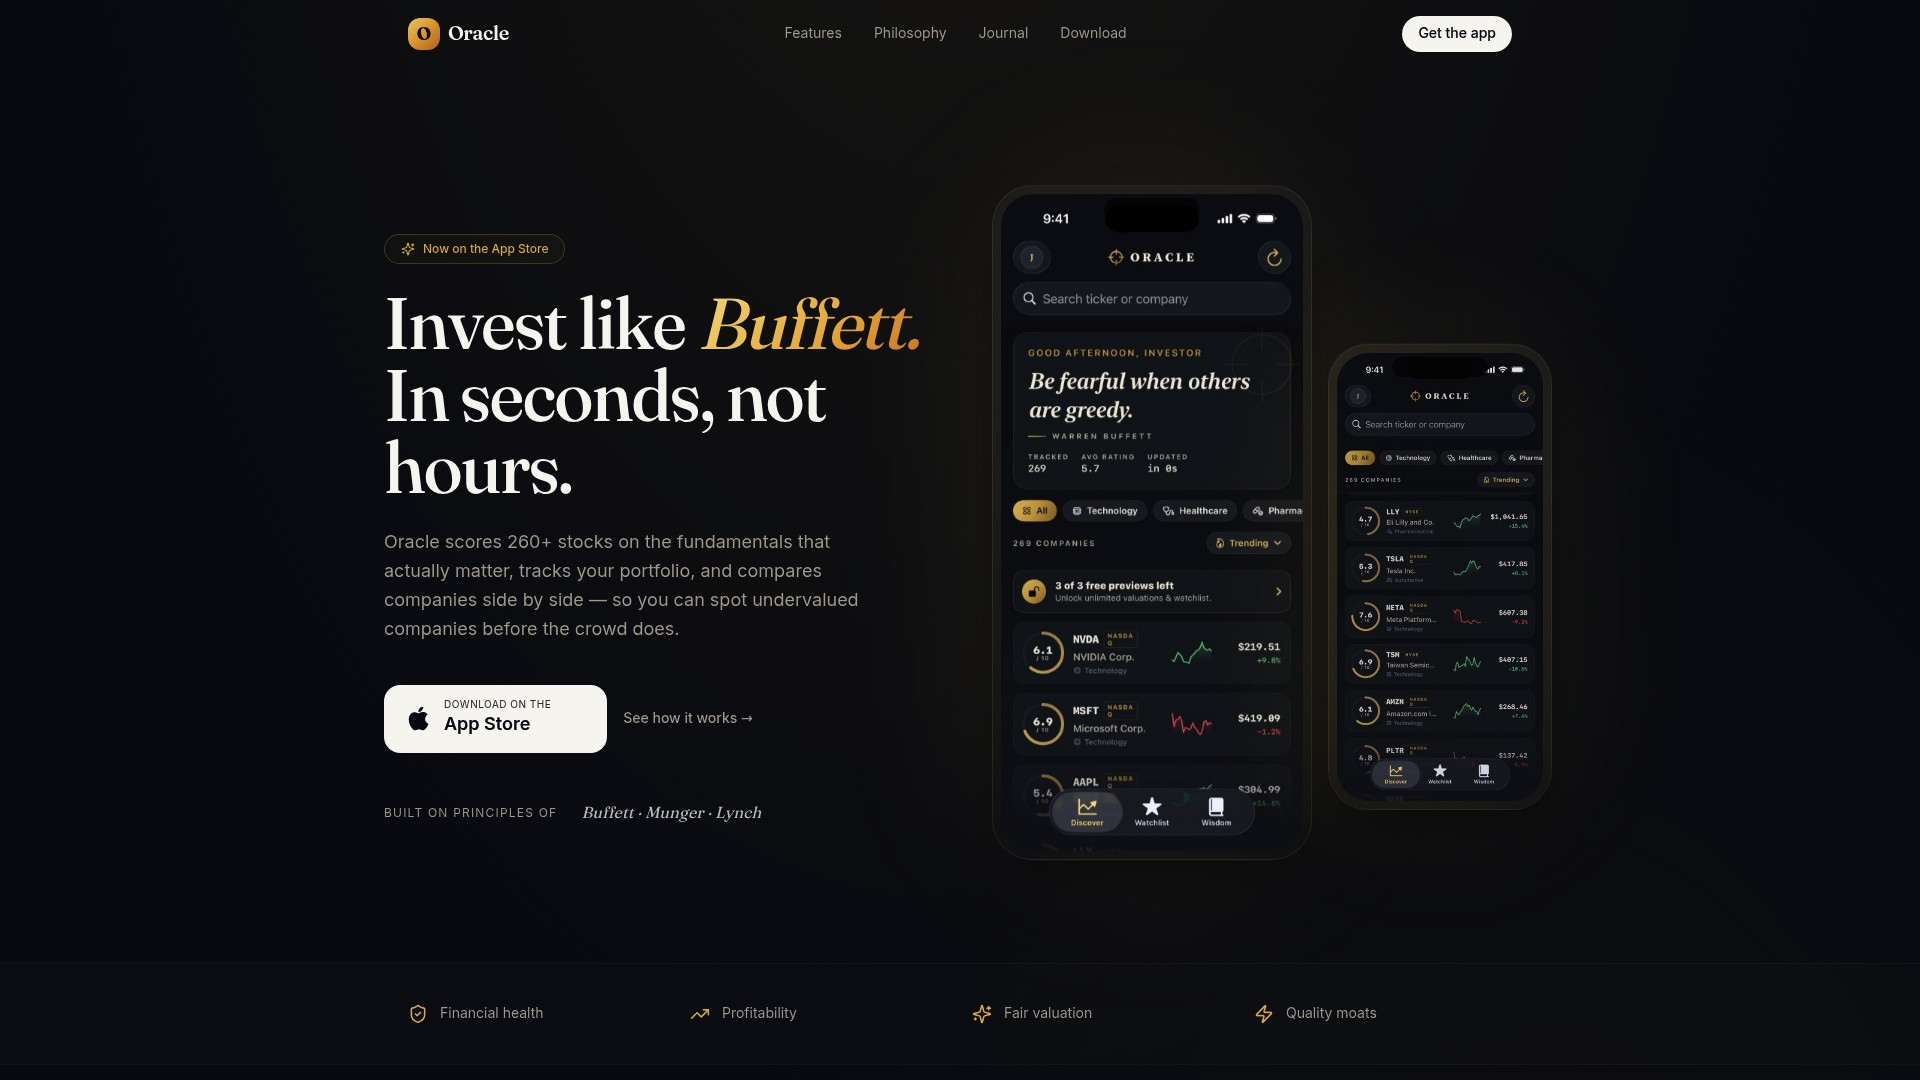
The subscription is available through the Apple App Store as Premium Annual. If you are building a spin-off watchlist, it is a quick way to put each name through the same framework.
FAQ
How do I make money with spinoff investing?
You profit if the market misprices the new company or the parent, and then corrects. The common source of mispricing is forced selling by funds that cannot hold the new shares. But research shows spin-offs do not reliably beat the market, so the gain has to come from your analysis of the individual business.
Where can I find upcoming spin-offs?
Start with EDGAR and search for Form 10 and Form 10-12B registration statements. Then follow corporate press releases and investor relations pages, and watch the corporate action notices from your broker. Together these cover most announced U.S. separations.
Do I owe tax when I receive spin-off shares?
Often not at the time of distribution, because many spin-offs are structured to be tax-free for U.S. federal income tax purposes. Cash received in place of fractional shares can still be taxable. Your company's tax disclosure explains how to split your cost basis, and a CPA can confirm how it applies to you.
Should I keep the parent or the spin-off?
That depends on which business you can value more confidently. Compare debt, return on capital and growth for both, and ask why the separation happened. Many investors keep both at first, then trim whichever no longer fits their thesis.
Is it better to buy on the first day of trading?
Not necessarily. Early trading can be volatile because some holders sell for mandate reasons rather than valuation. Starting with a small position and adding after you have read the filings and early earnings reports is a more careful approach.
Sources
- What Are Corporate Spinoffs and How Do They Impact Investors (FINRA)
- SEC Form 8-K on fractional share handling in a spin-off
- Parents and Spin-offs: When to Buy and When to Sell (Investopedia)
- SEC Form 10-12B: What it Means, How it Works (Investopedia)
- 2025 Spin-Off Guide
- Driving value through M&A spin-offs and separations (McKinsey)
- Restructuring through spin-offs (1993 study)
- Vista Outdoor distribution press release (SEC EX-99.1)
- SWS Group spin-off tax disclosure (SEC)