Loss aversion is the tendency to feel the pain of a loss more strongly than the pleasure of an equal gain. In investing, it quietly pushes you to hold losing stocks too long, sell winners too soon, and check your portfolio so often that you take less risk than your goals call for. You can't switch it off. You can build rules that keep it from making your decisions.
This guide covers where the idea comes from, what the research shows, the examples you are most likely to see in your own account, and a set of practical habits for managing it.
TL;DR
- Loss aversion means losses feel heavier than gains of the same size. In prospect theory, the value curve is steeper for losses than for gains.
- It shows up as the disposition effect: selling winners early and riding losers, often at a tax cost.
- Checking your portfolio constantly makes it worse. Less frequent evaluation is associated with more risk taken and more money earned in experiments.
- Written rules, scheduled rebalancing and fundamentals-based scoring replace gut reactions with a process.
Table of Contents
- What loss aversion actually is
- Where the idea comes from: behavioral finance and prospect theory
- How loss aversion shows up in your portfolio
- Myopic loss aversion: why checking too often hurts
- How to tell if loss aversion is driving your decisions
- Practical ways to manage loss aversion
- A worked example
- Our perspective
- Put a process behind your decisions
- Quick checklist for your next decision
- FAQ
- Sources
What loss aversion actually is
Imagine you are offered a coin flip. Heads you win $100, tails you lose $100. The math says it is a fair bet, yet many people decline it. A loss of $100 feels bigger than a gain of $100 feels good, so the bet doesn't feel even.
That asymmetry is loss aversion. Investopedia's overview describes it as the tendency to feel the pain of losses more strongly than the pleasure of equivalent gains, and notes that it helps explain why investors focus on the downside more than the upside.
It is not the same as being cautious. A cautious investor weighs risk and reward and picks a level of risk that fits their situation. A loss-averse reaction skips the weighing. It is an emotional response that arrives before the analysis does.

Where the idea comes from: behavioral finance and prospect theory
Traditional finance assumed investors treat gains and losses symmetrically and make decisions by cold expected value. Behavioral finance exists because real people don't behave that way.
The foundation is the 1979 paper by Daniel Kahneman and Amos Tversky, Prospect Theory: An Analysis of Decision under Risk. Their value function has two features that matter here:
- Value is measured as change from a reference point (what you paid, or where the account stood yesterday), not as final wealth.
- The curve is steeper for losses than for gains, so the same dollar amount hurts more than it pleases.
The reference point is the quiet troublemaker. Your purchase price means nothing to the market, but it means a great deal to you. A stock that is down 20% from your cost basis feels like a loss to be avoided, even if the best use of that money today is somewhere else.
How loss aversion shows up in your portfolio
Here are the most common examples, roughly in the order most investors meet them.
Holding losers too long
Selling a stock below your purchase price turns a paper loss into a realized one. Many investors avoid that moment and keep the position, hoping it returns to break-even. The question that matters is different: would you buy this stock today, at today's price, with fresh money? If not, the purchase price is the only thing keeping you in.
Selling winners too soon
The flip side feels sensible. A stock is up 25%, and you take the gain before it can disappear. Locking in a win feels safe, but if the business is still healthy and fairly valued, you have cut off the compounding that produces long-term returns.
The disposition effect
Together, these two habits are called the disposition effect. Investopedia notes that fear of loss can cause investors to keep losing stocks too long or sell winners too quickly.
The classic evidence comes from Terrance Odean's study of trading records for 10,000 accounts at a large discount brokerage from 1987 to 1993. Investors showed a strong preference for realizing winners over losers. That preference was not justified by the later performance of the stocks, and in taxable accounts it can lead to lower after-tax returns.
The idea goes back further. Hersh Shefrin and Meir Statman's 1985 paper on selling winners too early and riding losers too long links the pattern to loss realization aversion, mental accounting, regret aversion, self-control and tax considerations. In other words, loss aversion rarely acts alone.
Staying out of stocks entirely
Loss aversion can also keep people from investing at all. In a household study by Dimmock and Kouwenberg, higher loss aversion was associated with a lower probability of participating in equity markets, and it reduced the probability of owning individual stocks more than the probability of owning mutual funds. For a beginner, the fear of seeing red can be what keeps savings in cash for years.
Panic selling in a downturn
When markets fall, the pain of watching a balance shrink can push investors to sell near the bottom. DALBAR's 2023 report found that the average equity fund investor finished 2022 down 21.17%, against 18.11% for the S&P 500, a gap of 306 basis points. That gap reflects the timing of investor cash flows and trades. It is the kind of cost that emotional decisions can add.
Myopic loss aversion: why checking too often hurts
Loss aversion gets worse the more often you look. Stocks go up over long periods but wobble daily, and if you check every day, you see a lot of small losses.
This is called myopic loss aversion. In a 1997 experiment published in the Quarterly Journal of Economics by Thaler, Tversky, Kahneman and Schwartz, participants who got the most frequent feedback took the least risk and earned the least money.
The practical lesson is not to ignore your investments. It is to decide in advance when you will look and what you will look at. If you want to see how a disciplined review works, our guide on how to track portfolio performance like a pro covers what to measure and what to skip. The case for patience is also laid out in time in the market, which looks at how holding periods affect outcomes for individual investors.
How to tell if loss aversion is driving your decisions
These questions help you catch it in the act.
- Is my reason tied to my purchase price? Phrases like "I'll sell when it gets back to what I paid" are a reference-point trap.
- Would I buy this today? If the answer is no, and you are holding anyway, you are paying a fee in attention and opportunity.
- Did I sell because the thesis changed, or because I felt relief? Selling a winner to feel safe is different from selling because the stock has become overvalued.
- How many times did I check my account this week? A rising count often tracks rising anxiety.
- Am I keeping cash I planned to invest? Waiting for a calmer market is a common disguise for loss avoidance.
It is worth keeping a short decision journal. Write down why you bought, what would make you sell, and what you expect the business to do. When emotion hits, you can read what you decided while calm. Our article on mental accounting in investing explains a closely related bias that often travels with loss aversion, such as treating gains as "house money" or one losing position as a separate bet.
Practical ways to manage loss aversion
You can't remove the feeling, so design around it.
1. Set sell rules before you buy
Decide what would make you sell: a deteriorating business, a valuation far above your estimate of worth, or a better use of the money. Writing this down turns a painful moment into an if-then check. Our guide on when to sell stocks gives a framework you can adapt.
2. Judge the company, not your cost basis
The business does not know what you paid. Evaluate it on current fundamentals: profitability, valuation and financial health. Is it earning good returns on capital? Is the balance sheet sound? Is the price reasonable compared with what the business earns? These questions have the same answer whether you are up 30% or down 30%.
3. Rebalance on a schedule
Rebalancing forces you to do the opposite of what loss aversion suggests. The SEC's investor education site explains that rebalancing means bringing a portfolio back to its original asset allocation, which may involve selling from overweight categories and buying underweight ones. After a downturn, that often means buying what has fallen, which feels uncomfortable and is exactly why a calendar rule helps. See how often to rebalance and how to spot and fix portfolio drift.
4. Reduce how often you look
Pick a review rhythm, such as monthly or quarterly, and keep daily price alerts off for long-term holdings. This is a direct response to the myopic loss aversion findings above.
5. Size positions so a loss doesn't hurt
Loss aversion bites hardest when a single position can wreck your month. Spreading money across several holdings means no one loss feels like a catastrophe. If you are close to or in retirement, also read about sequence of returns risk, where the order of gains and losses matters more, and talk to a fiduciary financial adviser or CPA about your own withdrawal plan and tax situation.
6. Compare risk and return, not just return
A painful drawdown is easier to tolerate when you knew what to expect. Looking at risk-adjusted returns helps you set realistic expectations before the market tests them.
7. Know the common beginner mistakes
Loss aversion often hides inside the errors new value investors make. Our list of value investing mistakes beginners make is a good companion to this article.
A worked example
Say you own two stocks, each bought for $5,000.
- Stock A is now worth $6,250, up 25%. Its earnings keep growing and the valuation is still reasonable.
- Stock B is now worth $3,750, down 25%. Its profits have fallen for three quarters and debt is rising.
Loss aversion pulls you to sell A (lock in the win) and hold B (avoid admitting the loss). A disciplined review asks the opposite questions. Does A's business still justify holding? Does B's business still justify owning, at today's price? If A is healthy and B is deteriorating, the habit-driven move is the wrong one.
Taxes add a wrinkle. In a taxable account, realized gains and losses can have different consequences, which is part of why the disposition effect can raise a tax bill, as Odean's work notes. Check the current IRS guidance or ask a CPA before making tax-motivated trades.
Our perspective
We built Oracle Investments around a simple belief: most investing mistakes are emotional before they are analytical. Loss aversion is the clearest case. When a stock drops, the feeling shouts. Fundamentals speak quietly.
That is why our scores are rule-based and grounded in reported company fundamentals, and why we show the inputs behind every score. A score built on profitability, valuation and financial health doesn't care what you paid for the stock. It gives you the same read whether you are up or down, which is the point.
We also put the wisdom of investors like Warren Buffett, Charlie Munger and Peter Lynch inside the app, because their habits are largely about discipline: knowing what you own, buying at sensible prices, and not letting the market's mood decide for you.
Used well, a tool like ours gives you a calm second opinion at the exact moment your instincts are least reliable.
Matt
Put a process behind your decisions
If you want a quick, consistent way to check whether a stock still deserves its place in your portfolio, Oracle Investments scores over 260 stocks on profitability, valuation and financial health, and lets you compare companies side by side. The Premium Annual plan adds real-time portfolio tracking, so you can see your holdings against the fundamentals instead of reacting to price alone. See Premium Annual and review how the scoring works.
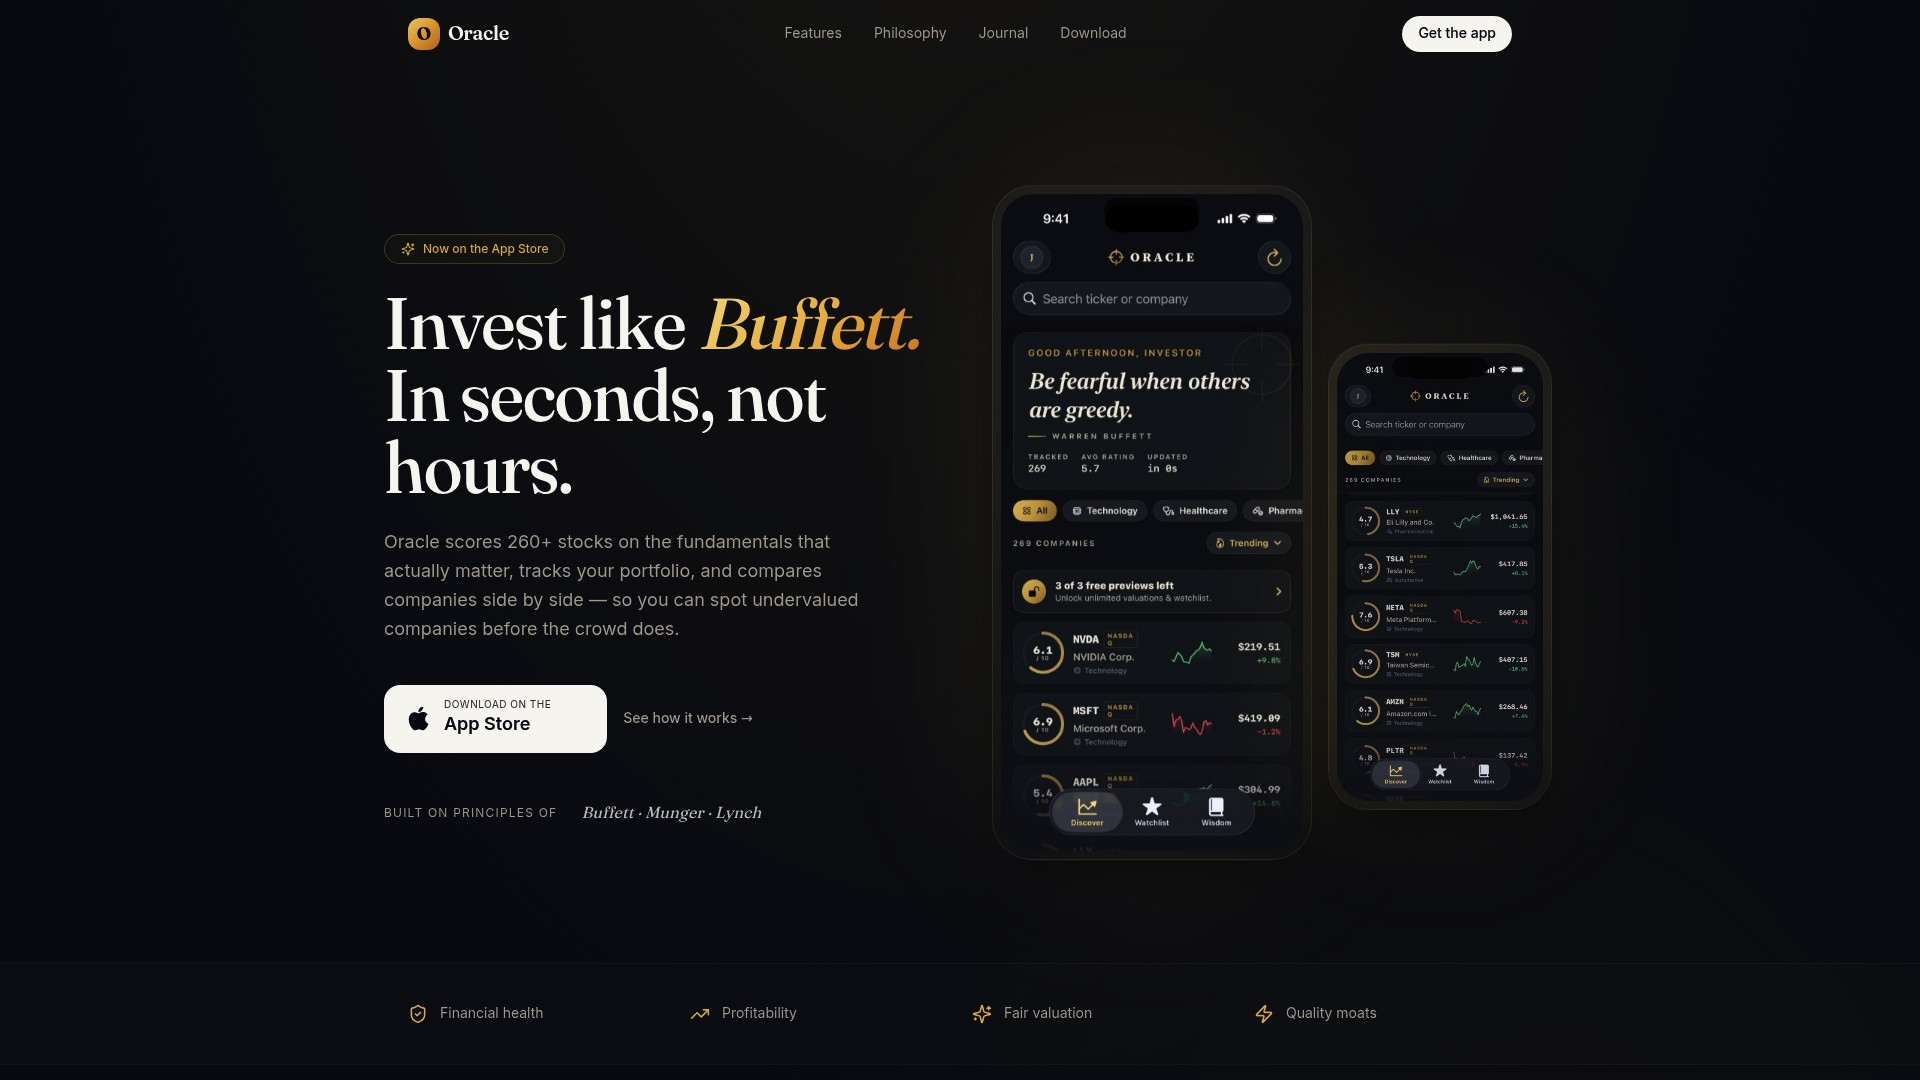
Beginners can use the educational content from legendary value investors to build the habits above. Experienced investors can use the instant comparisons as a check against their own bias.
Quick checklist for your next decision
- Write down why you own the stock, and what would make you sell.
- Ignore your purchase price and ask whether you would buy it today.
- Check the fundamentals: profitability, valuation, financial health.
- Look at the position size relative to your whole portfolio.
- Wait for your scheduled review unless something about the business has changed.
For how to combine fundamentals with timing, see our piece on screening with fundamentals and timing trades with technicals.
FAQ
What is loss aversion in investing?
It is the tendency to feel losses more strongly than equal gains. For investors, that can mean holding losing positions too long, selling winners early and avoiding stocks altogether. It comes from prospect theory, where the value curve is steeper for losses than for gains.
What is the difference between loss aversion and risk aversion?
Risk aversion is a preference for more certain outcomes, and it can be a reasoned choice based on your goals. Loss aversion is about how differently losses and gains are felt relative to a reference point, such as your purchase price. The first can be a plan. The second often works against one.
What are common examples of loss aversion?
The most common are refusing to sell a stock until it returns to your purchase price, selling a winner quickly to lock in a gain, and checking your account so often that normal swings feel alarming. Another is keeping cash on the sidelines because losing money feels worse than missing gains.
Can you overcome loss aversion?
You are unlikely to eliminate the feeling, but you can limit its effect. Set sell rules in advance, review on a schedule, rebalance by calendar and judge each company on current fundamentals instead of cost basis. If your decisions involve large sums or taxes, a fiduciary adviser or CPA can help.
How does checking my portfolio often make it worse?
Frequent checking exposes you to more small losses, which sharpens the pain. In a well-known experiment, participants who got the most frequent feedback took the least risk and earned the least. A fixed review schedule is a simple fix.
Sources
- Understanding Loss Aversion in Trading (Investopedia)
- Prospect Theory: An Analysis of Decision under Risk (Kahneman and Tversky, 1979)
- Are Investors Reluctant to Realize Their Losses? (Odean, 1998)
- The Disposition to Sell Winners Too Early and Ride Losers Too Long (Shefrin and Statman, 1985)
- Loss-aversion and household portfolio choice (Dimmock and Kouwenberg, 2010)
- DALBAR 2023 Quantitative Analysis of Investor Behavior
- Effect of Myopia and Loss Aversion on Risk Taking (Thaler, Tversky, Kahneman, Schwartz, 1997)
- Beginners' Guide to Asset Allocation, Diversification, and Rebalancing (SEC Investor.gov)