For most investors with a diversified stock and bond portfolio, reviewing once or twice a year and trading only when an asset class sits about 5 percentage points away from its target is a sound answer. Research finds no single optimal frequency or threshold, and the schedule you will actually keep matters more than the one that looks best on paper. Below you will find the evidence, how calendar and threshold methods differ, what rebalancing costs in a taxable account, and a plan you can set up in an afternoon.
TL;DR
- Annual or semiannual reviews, with a trade only when an asset class is about 5 points off target, balance risk control and cost for most diversified portfolios.
- Monthly, quarterly and annual rebalancing produced similar risk-adjusted returns in one analysis, but more frequent rebalancing means more trades and more costs.
- Never rebalancing is the real risk: a 60/40 portfolio left alone drifted to an average stock allocation above 84% in that same analysis.
- In taxable accounts, new contributions, dividends and withdrawals are your cheapest rebalancing tools. Selling winners can create a tax bill.
- Pick a schedule you can maintain. A plan you skip is worse than a slightly imperfect plan you follow.
Table of Contents
- Why frequency matters less than most people think
- What the research says about each schedule
- Calendar vs. threshold rebalancing
- Costs and taxes: the hidden side of rebalancing often
- How to set up a rebalancing plan in five steps
- When your situation changes the answer
- Perspective
- Make the review faster with Oracle
- FAQ
- Sources
Why frequency matters less than most people think
Rebalancing means bringing your holdings back to the mix you chose, for example 60% stocks and 40% bonds, after markets have pushed them apart. It is a risk tool first. Stocks that outrun bonds quietly turn a moderate portfolio into an aggressive one, and you find out during the next drawdown.
The frequency question gets a lot of attention, yet the numbers are forgiving. An AAII write-up of Vanguard Investment Strategy Group research found that monthly, quarterly and annual rebalancing produced meaningfully similar risk-adjusted returns, while rebalancing events and their costs rose as frequency increased. The same piece reports that a never-rebalanced 60/40 portfolio drifted to an average equity allocation above 84%, with higher average volatility.
The lesson is not that frequency is irrelevant. The gap between sensible schedules is small, and the gap between a sensible schedule and no schedule is large. The Texas State Securities Board puts it plainly: there is no official timetable for rebalancing, and the further you are from retirement, the less critical frequent rebalancing is likely to be.

What the research says about each schedule
Here is how the common options compare, based on the evidence we reviewed.
| Schedule | Effort | Trading and tax cost | What the evidence suggests |
|---|---|---|---|
| Monthly or weekly | High | Highest | Weekly rebalancing is overly expensive in taxable gains and transaction costs. Daily or monthly may also weaken results in drawdowns, because you keep buying into declining assets. |
| Quarterly | Medium | Moderate | Experts generally describe quarterly or yearly assessments as reasonable. |
| Semiannual | Low | Low | Fits the six-month review that Investor.gov describes as one common approach. |
| Annual | Lowest | Lowest | The most common choice among long-term investors, and in the analysis above it did about as well as more frequent options on a risk-adjusted basis. |
| Every few years or never | Minimal | Low trading cost | Too much drift. Waiting more than a year leaves too much time for allocations to wander. |
Vanguard research from 2022 reached a similar conclusion from the other side: calendar strategies that are too frequent, such as daily, or too infrequent, such as never or every 2.5 years, are inefficient on risk, return and cost. The sweet spot is a broad middle.
The AAII summary of that research lands on a practical rule: for most broadly diversified stock and bond portfolios, annual or semiannual monitoring with rebalancing at 5% thresholds is likely to balance risk control and cost.
Calendar vs. threshold rebalancing
There are two ways to decide when to trade.
Calendar-based rebalancing resets the portfolio at fixed intervals, such as every January or every January and July. Vanguard describes it as resetting at set intervals, with reviews that can be quarterly or yearly. It is simple and predictable. You do not need to watch the market at all.
Threshold-based rebalancing triggers a trade only when an asset class drifts past a preset limit, for example 5 percentage points. It keeps allocation tighter than a calendar does, but it needs monitoring. Vanguard's research notes that threshold strategies require daily monitoring of asset weights to catch a breach, which makes them more intensive than a set schedule. Its 2022 analysis added that smaller thresholds reduce tracking error but raise transaction costs, which is why daily monitoring is impractical for many individual investors.

A hybrid that fits real life
You do not have to choose one. A practical blend: put a review on the calendar once or twice a year, and on that day rebalance only the holdings that are past your threshold. You get the simplicity of a calendar and the cost discipline of a threshold, without watching prices daily.
Two refinements are worth knowing:
- Rebalance to the band, not the bullseye. CFA Montreal notes that returning to a tolerance band instead of the exact target helps reduce turnover and costs. Vanguard researchers suggest that setting the destination slightly closer to the threshold can reduce trade sizes and lower costs while still controlling drift.
- Use relative thinking for small positions. A 5-point band suits a 40% bond sleeve. For a 5% emerging-markets slice, a band of one or two points is more sensible than five.
Active traders who work under hard loss limits will recognize the logic of rules that fire at a fixed line. This explanation of risk limits in trading challenges shows the same idea applied to short-term accounts: the rule removes the need for in-the-moment judgment.
Costs and taxes: the hidden side of rebalancing often
Every trade has a price. According to AAII, U.S. investors should weigh capital-gains taxes on appreciated assets sold in taxable accounts, brokerage commissions, mutual fund fees and their own time. Trading restrictions in certain accounts can also limit how often you can realistically trade.
A 2007 study in the FPA Journal found that in taxable accounts, techniques that generate many trades, and therefore more capital gains, are at a disadvantage compared with those that trade less. That is a strong argument for the lower end of the frequency range in a brokerage account.
Ways to rebalance without selling
Before you sell anything, try these in order:
- Direct new money to the underweight asset. AAII notes that redirecting cash flows or contributions to underweighted assets can reduce trading costs.
- Reinvest dividends and interest into the laggard rather than back into the winner.
- Take withdrawals from the overweight asset if you are drawing income.
- Do the heavy trading inside tax-advantaged accounts, such as an IRA or 401(k), where a sale does not create a taxable event. Check your plan's trading rules first.
- Sell in the taxable account last, and only as much as needed to get back inside your band.
If you do have to realize gains, pairing them with losses can soften the bill. Our guide to tax-loss harvesting for U.S. investors explains how to do it without tripping the 30-day wash sale rule. For a tax question specific to your situation, a CPA or fee-only financial planner is the person to ask.
Turnover is the other cost to watch. If you want to see how frequent trading quietly eats returns, our portfolio turnover rate example and checklist walks through it with numbers.
How to set up a rebalancing plan in five steps
- Set a target allocation. Base it on your time horizon and risk tolerance. Investor.gov describes this as the starting point: choose the mix first, then maintain it.
- Write down your rule. For example: "Review every January and July. Rebalance any asset class more than 5 points off target." Put the dates in your calendar.
- Measure current weights. Add up each asset class across every account, not each account alone. This is where many people go wrong. Our guide on how to track portfolio performance covers a clean way to see the whole picture.
- Fix drift with the cheapest tool first. Use contributions and dividends, then tax-advantaged accounts, then taxable sales.
- Log what you did and why. A two-line note keeps you from second-guessing yourself next time.
If drift is the part that confuses you, this walkthrough of portfolio drift shows how to spot it and correct it quickly.
When your situation changes the answer
Early in your career. Regular contributions do most of the work. The Texas securities regulator notes frequent rebalancing is less critical the further you are from retirement, so once a year is plenty.
Near or in retirement. Withdrawals give you a natural rebalancing lever, and a portfolio that has drifted toward stocks is more exposed to a bad early market. Our pieces on sequence of returns risk and an income-first retiree strategy explain why drift matters more when you are drawing money out.
During a market panic. Rebalancing is a rules-based way to avoid emotional decisions. Morningstar analysts emphasize that it keeps risk aligned with the investor's original comfort zone. If you feel tempted to skip a scheduled rebalance because markets look scary, that is usually the moment the plan is working. Our guide to downside protection strategies covers the wider toolkit.
When you hold individual stocks. Rebalancing a stock sleeve is different from rebalancing funds, because one winner can grow into an outsized position. The same bands apply: decide the maximum weight any single position can reach, and review it on your normal schedule. Mental shortcuts can get in the way here, as we explain in how mental accounting hurts your portfolio.
Perspective
Most of the rebalancing debate is about the calendar, but the harder problem is knowing what you own and why. When you rebalance a stock sleeve, you are making a choice about each company, not only about a percentage. Trimming a winner is easy to justify when its price has run far ahead of its fundamentals. Adding to a laggard is only wise if the business is still sound.
That is why we built Oracle Investments around rule-based scores. Our ratings are grounded in reported company fundamentals such as profitability, valuation and financial health, and the scoring inputs are visible, so you can see what drives a number instead of trusting a black box. Our scores are designed to help you compare companies side by side before you decide which position to trim and which to add to.
We also built in the lessons of value investors like Warren Buffett, Charlie Munger and Peter Lynch, because discipline is what makes any rebalancing rule work. Our view: choose a simple schedule, write it down, and let the fundamentals, not the headlines, tell you where to put the next dollar.
Matt
Make the review faster with Oracle
A rebalancing day goes quicker when you can see your holdings and how each company scores in one place. Oracle Investments scores over 260 stocks on profitability, valuation and financial health, lets you compare companies side by side, and includes portfolio tracking so you can see your current weights at a glance. It runs without setup or spreadsheets, and the app is available through the Apple App Store.
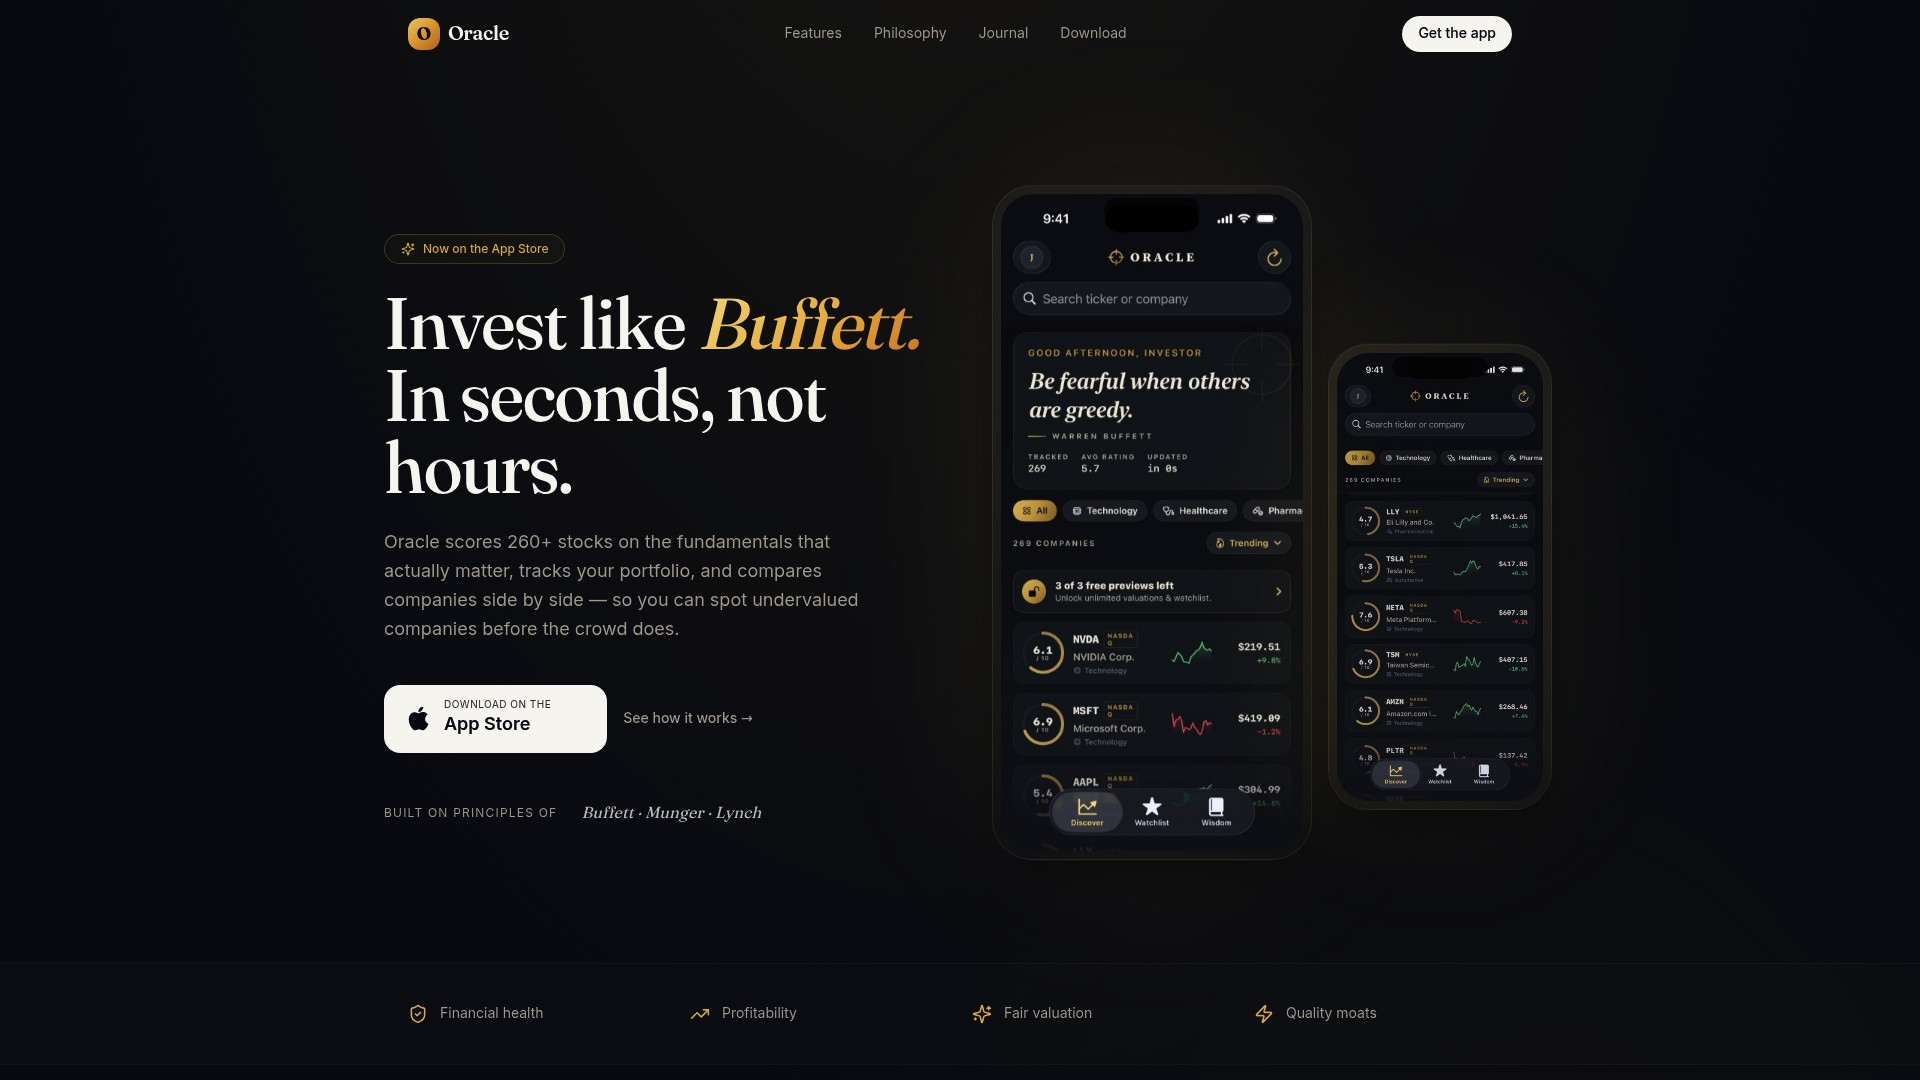
If your next review is coming up, try Oracle Investments and check the fundamentals behind each position before you trade.
FAQ
How often should a portfolio be rebalanced?
For most diversified stock and bond portfolios, once or twice a year is enough. Research summarized by AAII found no optimal frequency, and it described annual or semiannual monitoring with 5% thresholds as a likely balance of risk control and cost. Choose the schedule you will actually follow.
Is it better to rebalance on a schedule or when allocations drift?
Both work. A schedule is simpler, while drift-based rules give tighter control but need continuous monitoring and more operational effort. A hybrid, reviewing on set dates and trading only when a holding is past your band, suits most individual investors.
Can rebalancing too often hurt returns?
It can raise costs without improving risk-adjusted results. More frequent rebalancing means more trades, and in taxable accounts those trades can create capital gains. Morningstar also notes that daily or monthly rebalancing may weaken performance in drawdowns by repeatedly buying declining assets.
How do I rebalance without paying extra taxes?
Start by directing new contributions and dividends to the underweight asset, and take withdrawals from the overweight one. Do larger trades inside tax-advantaged accounts where possible. For gains you must realize in a taxable account, ask a CPA or fee-only planner about your own tax position.
Should I rebalance during a market crash?
If your rule says to, yes. Rebalancing is designed to keep your risk level where you set it, which often means buying the asset that has fallen. If the idea feels uncomfortable, a threshold that triggers fewer trades can make the process easier to stick to.
Sources
- Best Practices for Portfolio Rebalancing, AAII
- Rebalancing Your Portfolio, Texas State Securities Board
- Types of Rebalancing Strategies, Investopedia
- You Probably Need to Rebalance, Morningstar
- Beginners' Guide to Asset Allocation, Diversification, and Rebalancing, Investor.gov
- Rational rebalancing: An analytical approach to multiasset portfolios, Vanguard
- Rebalancing your portfolio: How to rebalance, Vanguard
- The rebalancing edge: Optimizing target-date fund rebalancing, Vanguard
- How to Rebalance, CFA Montreal
- Rebalancing for Taxable Accounts, FPA Journal
- Rebalancing a multi-asset portfolio, Wellington
- Risk Management in Prop Firm Challenges Explained