A dividend safety score is a single number or grade that estimates how likely a company is to keep paying its dividend. It rolls several financial checks into one figure: how much of earnings and cash the payout uses, how heavy the debt is, and how steady the business has been. The score is only as good as the inputs behind it. The most useful version is one where you can see every input and the rule that turns it into a grade. That is how we built Oracle Investments, which scores over 260 stocks on profitability, valuation and financial health from reported fundamentals.
This guide explains what goes into a safety score, how to interpret one, and how to run the same analysis on any dividend stock in about ten minutes.
TL;DR
- A dividend safety score summarizes whether a company can afford its payout from earnings, cash flow and its balance sheet.
- The core inputs are the payout ratio, free cash flow coverage, debt load and the stability of earnings.
- A high yield is not a sign of safety. It often means the market expects a cut.
- Scores from different providers use different rules, so compare the inputs, not just the numbers.
- Rule-based scores with visible inputs let you check the reasoning instead of taking a grade on faith.
Table of Contents
- What a dividend safety score actually tells you
- The four inputs behind almost every safety score
- How a score combines the inputs
- How to interpret the number
- Warning signs that a dividend may be cut
- A ten-minute dividend safety check you can run yourself
- What a score cannot see
- Putting scores to work in a portfolio
- Perspective
- See the inputs for 260+ stocks in one place
- FAQ
- Sources
What a dividend safety score actually tells you
A dividend is a choice the board makes each quarter. Nothing forces a company to keep paying it. The score answers one question: given what this company earns, owes and generates in cash, how comfortable is the payout?
A score does not predict the future. It reads the past and present financials and asks whether the dividend sits on solid ground. A company with a low payout ratio, plenty of cash and modest debt can absorb a bad year. A company paying out nearly everything it earns, with heavy debt, has no cushion.
This matters because dividends are treated by managers as close to a promise. Aswath Damodaran of NYU's Stern School of Business describes U.S. dividends as "sticky": firms are reluctant to cut even when earnings fall, and dividends follow a smoother path than earnings. That stickiness is why a cut tends to be a late signal. By the time a board gives up on the payout, the strain has usually been visible in the numbers for a while. A safety score is meant to catch that strain early.
The four inputs behind almost every safety score
Providers differ in weighting and presentation, but nearly all of them lean on the same four families of evidence.
1. Payout ratio
The payout ratio is dividends divided by net income, or dividends per share divided by earnings per share. It shows what slice of profit goes to shareholders. A company paying 40 cents of every dollar it earns has room to maneuver. One paying 95 cents does not.
For context, Damodaran's analysis of Value Line data (January 2009) found a median payout ratio of about 35% among dividend-paying U.S. stocks, with an average near 40%, and a median yield of about 3%. That is a historical snapshot, not a modern benchmark, but it shows that a typical payer keeps most of its earnings.
We cover the threshold we use in detail in our guide on using a 75% cutoff to judge dividend payout ratios. The short version: the closer the ratio gets to 100%, the less margin for a down year, and above 100% the company is paying out more than it earns.
A payout ratio has a blind spot. Earnings include accounting items that are not cash, and one-time gains or write-downs can distort a single year. Look at several years, not one.

2. Free cash flow coverage
Dividends are paid in cash, not in accounting profit. Free cash flow is the cash a business generates after the spending needed to maintain and grow its operations. Coverage is free cash flow divided by total dividends paid. A figure above 1 means the business funded the dividend from its own operations. A figure below 1 means the gap came from somewhere else: cash reserves, asset sales or borrowing.
This is the check that exposes the difference between a company that looks fine on earnings and one that is quietly stretched. Capital-heavy businesses such as utilities, telecoms and pipelines often show reasonable earnings but thin free cash flow because they spend so much on equipment and networks.
3. Debt and the balance sheet
A company that borrows to pay shareholders is on borrowed time. The research behind the Dividend Trap Score study (2024) names high debt-to-equity, suggesting debt is financing dividends, as one of its core warning components, alongside a payout ratio approaching or exceeding 100%.
Debt also carries fixed obligations. Interest and principal come due whether or not business is good, and they rank ahead of shareholders. When cash gets tight, the dividend is the discretionary item. Our explainer on the debt to equity ratio shows how to calculate it and why industry context changes what counts as high.
4. Earnings stability and dividend history
The same study lists significant earnings declines and sharp fluctuations as warning signs. A steady business can sustain a high payout. A cyclical business with swinging profits cannot, because the dividend that looked comfortable at the peak becomes a burden in the trough.
Dividend history adds a second view. A long record of maintained or rising payments suggests management treats the dividend seriously. It does not guarantee the next payment, but a company that kept paying through a recession has shown how it behaves under stress. Our piece on recession-resistant stocks looks at which kinds of businesses tend to hold up.
How a score combines the inputs
Providers typically turn these inputs into a scale. Some use 1 to 100, some use letter grades, some use five-point ratings. The mechanics are usually one of two kinds:
| Approach | How it works | What to check |
|---|---|---|
| Rule-based | Each metric is compared with a fixed threshold and earns points or a pass/fail | Are the thresholds shown? Do they fit the industry? |
| Model-based | A statistical or machine-learning model weights the inputs, often as a black box | Can you see why a stock scored as it did? |
A rule-based score has an advantage for an individual investor: you can read the rule, check it against the filing and disagree with it. If the score says a payout is stretched, you can see the payout ratio, the coverage and the debt that produced the verdict.
That is the approach Oracle takes. Our ratings are rule-based and grounded in reported company fundamentals, and we show the scoring inputs rather than hiding them behind a model.
How to interpret the number
A score is a starting point for a decision, not the decision itself. Here is how to read one sensibly.
Read the direction, not just the level. A score that falls over several quarters tells you more than one fixed number. A payout ratio creeping from 50% to 70% to 85% is a trend worth acting on even if each reading looks acceptable.
Match the score to the business type. A payout ratio that is alarming for a software company may be ordinary for a real estate or utility company, whose earnings are shaped by depreciation and heavy investment. Compare a company with its peers.
Be wary of yield as a signal. Yield is the annual dividend divided by the share price. When the price falls sharply, yield rises mechanically. A very high yield can be the market pricing in a cut, which is the situation the dividend trap research describes. Safety and yield often pull in opposite directions.
Do not compare numbers across providers. A 70 from one source and a 70 from another are not the same measurement. One may weight cash flow heavily and another may emphasize dividend streaks. Compare the inputs, or stick to one consistent method across every stock you evaluate so the numbers are comparable with each other.

Warning signs that a dividend may be cut
Whether or not you use a score, these signals deserve attention. The 2024 Dividend Trap Score research identifies several of them, and the rest follow from the mechanics above.
- A payout ratio at or above 100%. The company pays out more than it earns.
- Free cash flow that does not cover the dividend. The shortfall is being funded by reserves or borrowing.
- Rising debt alongside a flat or rising dividend. Borrowing is supporting the payout.
- Falling or erratic earnings. Volatility makes any fixed payout harder to sustain.
- Dividend growth that outpaces earnings growth. The payout ratio is drifting higher year after year.
Damodaran notes that the biggest peril when firms raise dividends is being unable to sustain them through volatile earnings. That is why a recent big dividend increase from a company with unsteady profits deserves a closer look rather than applause.
A ten-minute dividend safety check you can run yourself
You do not need a spreadsheet. Pull the last three to five years of figures from the company's annual reports and work through these steps.
- Calculate the payout ratio each year. Divide dividends per share by earnings per share. Note the trend.
- Calculate free cash flow coverage. Take operating cash flow minus capital spending, then divide by total dividends paid. Do it for every year you have.
- Check debt. Look at debt to equity and at how much of operating income goes to interest. Compare with peers in the same industry.
- Look at earnings stability. Did profits drop sharply in any recent year? How did the dividend behave then?
- Check the dividend record. Has it been held or raised through the last downturn?
- Look at the whole shareholder return. Some companies return cash through buybacks as well as dividends. Our guide to shareholder yield and the comparison of share buybacks vs dividends explain how to count both.
A worked example
Imagine a company that earns $4.00 per share and pays $1.60 in dividends. The payout ratio is 40%. Its free cash flow is $3.20 per share, so coverage is 2.0 times. Debt is moderate and earnings have stayed within a narrow range for five years. Every input points to a comfortable dividend.
Now take a second company that earns $2.00 per share and pays $1.90. Its payout ratio is 95%. Free cash flow is $1.40 per share, so coverage is about 0.74 times, meaning part of the dividend is funded by cash reserves or debt. Debt has risen for three years. Even if its yield is twice as high as the first company's, the second dividend has far less protection.
The figures are illustrative, not real companies. The point is how the same four inputs separate a safe payout from a stretched one.
What a score cannot see
Numbers come from reported results, so they describe where a company has been. Events that change the picture quickly, such as a major acquisition, a new debt issue, a lost customer or a regulatory change, show up in the numbers only after the next report. Read the company's latest earnings release and the notes on its capital plans alongside any score.
Market price adds another layer. A safe dividend can still sit on a stock that is overpriced, and a stock's price can fall while the dividend holds. Dividend safety and valuation are separate questions. Pairing the score with a look at the price-to-earnings ratio or earnings yield gives a fuller view of whether you are paying a sensible price for the income.
If you are planning retirement income that depends on dividends, consider talking with a licensed financial adviser about how much of your spending should rest on any single payout.
Putting scores to work in a portfolio
Different readers use a safety check differently.
Beginners can use it as a filter. Screen out companies with payout ratios near or above 100% and weak cash coverage, then study what is left.
Retirees and income investors care about reliability most. Spread income across sectors so that one business's cut does not hit your cash flow hard, and watch the trend in each holding.
Active investors can use scores to compare candidates side by side and to flag holdings whose fundamentals are deteriorating before the market notices.
Students can use the inputs as a framework: each one maps to a concept from corporate finance, and calculating them by hand builds intuition that lasts.
If you reinvest your dividends, the safety of each payer matters even more because the compounding depends on payments continuing. Our guide to dividend reinvestment plans covers the tax rules and enrollment.
Perspective
We built Oracle because most investors do not have the time to pull five years of filings for every stock they look at, and they should not have to trust a number they cannot inspect.
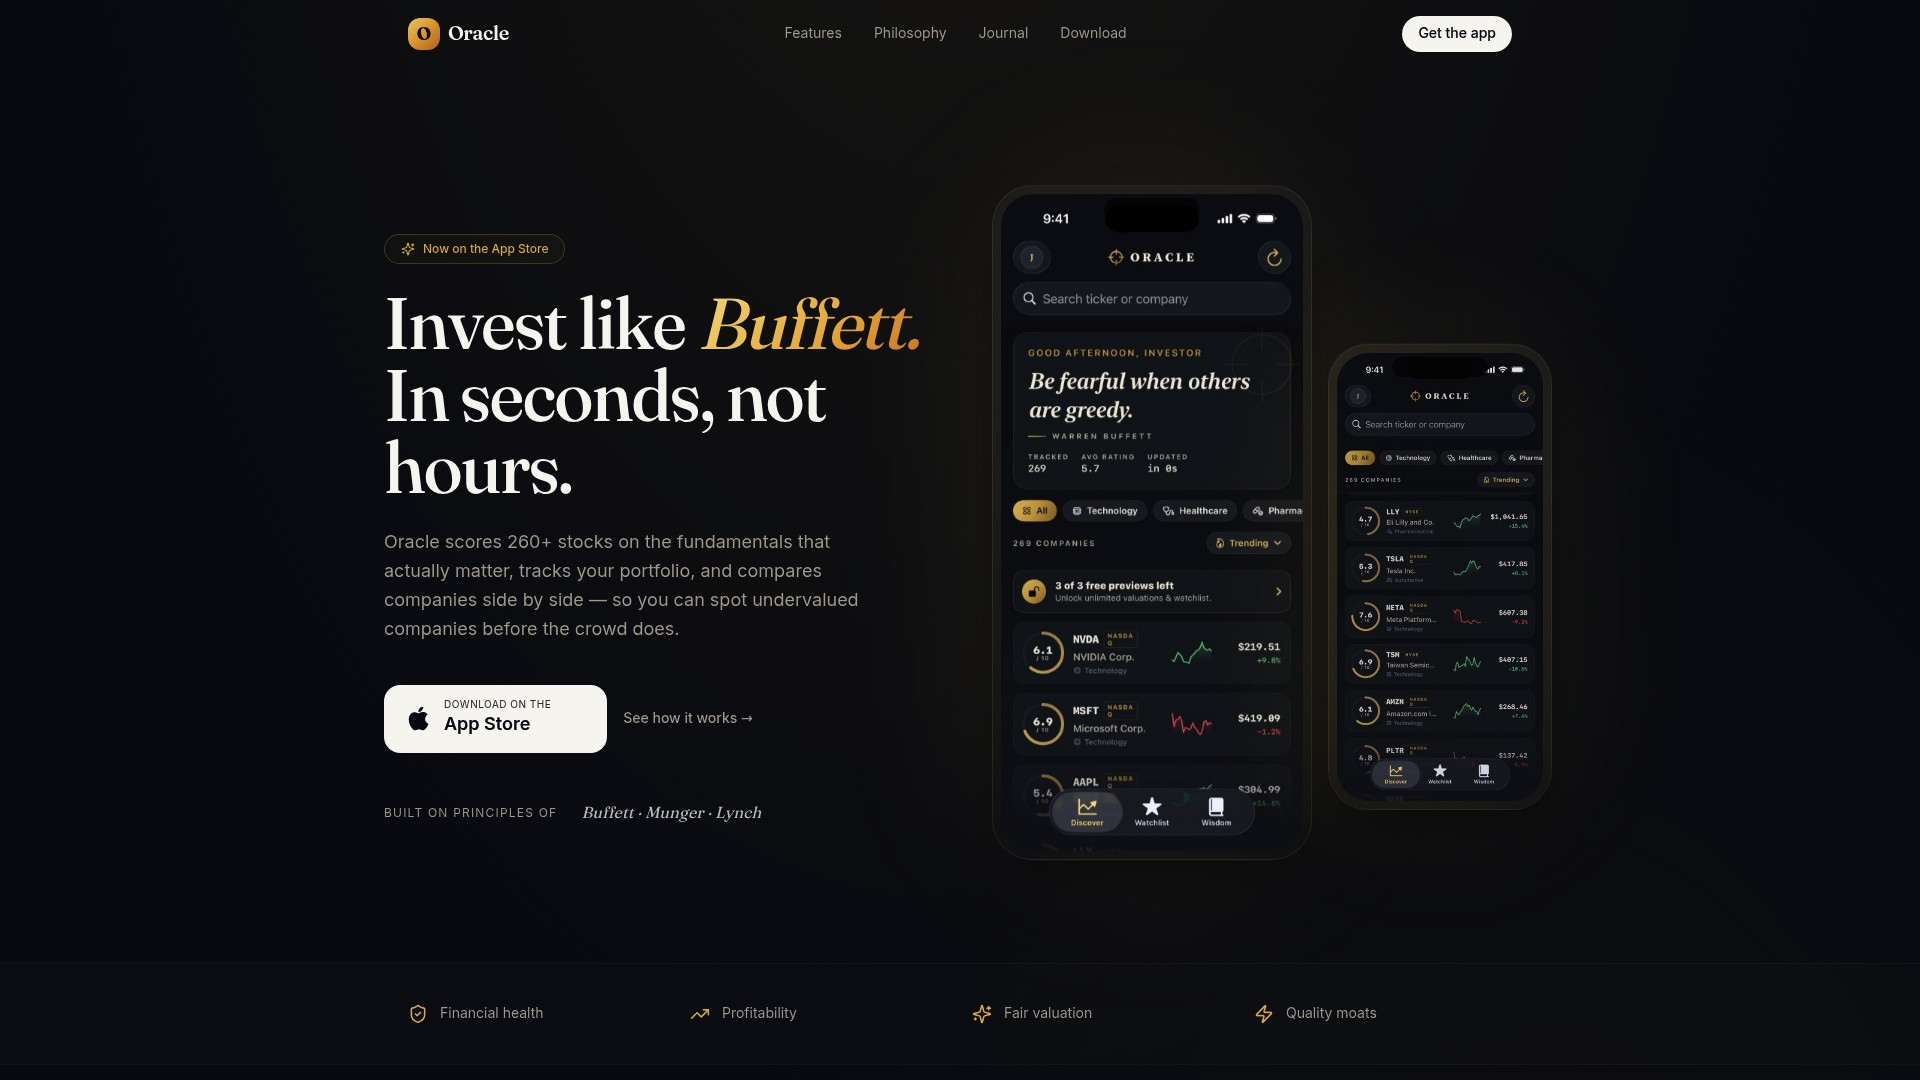
Our ratings are rule-based and grounded in reported company fundamentals. We avoid AI or model-driven guesswork, and we show the scoring inputs so you can see what moved a grade. For dividends, that means the things that actually decide whether a payout holds: profitability, financial health and valuation, laid out so you can compare companies side by side.
We also draw on the thinking of investors like Warren Buffett, Charlie Munger and Peter Lynch, because a score is most useful when you understand the principle behind it. Disciplined value investing should be usable in seconds, without a spreadsheet and without setup.
Matt
See the inputs for 260+ stocks in one place
Oracle scores over 260 stocks on profitability, valuation and financial health, so you can compare companies side by side and spot potentially undervalued names. It also tracks your portfolio in real time and includes educational content from legendary value investors. The Premium Annual plan is available through the Apple App Store, and you can see the details on the Oracle Investments site.
FAQ
What is a good dividend safety score?
It depends on the scale the provider uses, so read the definition first. In general, a good score means a modest payout ratio, free cash flow that comfortably covers the dividend, manageable debt and steady earnings. Judge any score by the inputs that produced it.
Is a high dividend yield a sign of a safe dividend?
No. Yield rises when a share price falls, so a very high yield can reflect market doubt about the payout. Safety rests on whether earnings and cash flow cover the dividend, which you check with the payout ratio, coverage and debt.
Can I compare safety scores from different providers?
Not directly. Each provider chooses its own inputs, weights and scale, so the same company can score differently. Compare the underlying metrics, or use one consistent method for every stock you evaluate.
How often should I recheck a dividend's safety?
Recheck after each quarterly earnings report, and sooner after a large acquisition, a new debt issue or a sharp earnings change. Watch the trend in the payout ratio and cash coverage rather than a single reading.
Sources
- Dividend Policy, Aswath Damodaran, NYU Stern (January 2009)
- The Dividend Trap Score Formulation: a Practical Approach (2024)