Unit economics measures whether a single customer, subscription, or order generates more gross profit than it costs to acquire and serve. For unit economics investing, the verdict is simple: if contribution margin stays positive and the LTV to CAC ratio holds near 3:1 with a reasonable payback window, growth compounds value. If it doesn't, scaling just multiplies the loss.
TL;DR:
- The correct unit must be defined carefully, such as per account for SaaS or per transaction for a marketplace, to ensure accurate economics modeling.
- Contribution margin should include only variable costs like processing fees and support, not fixed costs, since negative margins cannot be fixed through scaling.
- LTV must be based on gross profit and churn assumptions, with the ratio ideally near 3:1; sensitivity to churn assumptions can significantly impact the ratio.
- Investors require detailed cohort retention data, channel-specific CAC, and a trend of payback periods over multiple quarters to validate unit economics.
- Founders should produce a reproducible data pack with clear data joins, documented assumptions, and ongoing updates to maintain credibility during diligence.
Table of Contents
- What Is Unit Economics and Why Investors Track It
- Core Metrics and the Exact Formulas That Matter
- How Do You Calculate Unit Economics Step by Step?
- How Investors Read Unit Economics Investing Signals
- Data Integrity Rules That Keep Your Numbers Defensible
- Turning the Numbers Into Priorities and a Pitch
- Building a Reproducible Workflow Founders Can Actually Maintain
- Your Next Move on Unit Economics Investing
- The Gap Between Spreadsheet Math and an Investor-Ready Pack
- Sources
- FAQ
What Is Unit Economics and Why Investors Track It
Unit economics analysis starts with picking the right unit. That's the first decision founders get wrong, and it skews everything downstream. A subscription SaaS company should model per paying account. A marketplace should model per completed transaction, since the buyer and seller sides have different cost structures. A D2C brand should model per order, because repeat-purchase behavior varies wildly by product category.
Once you've locked in the unit, understanding unit economics comes down to answering one question for that unit: does it produce more gross profit than it costs to create? Everything else, including the LTV:CAC ratio, the payback period, and the contribution margin, is just a different lens on that same question.
Investors care because this is the fastest financial health assessment available before a full diligence process. A company can show impressive top-line revenue growth while destroying capital on every new customer it signs. Weak unit economics is a leading reason investors pass on deals during fundraising, and the pattern shows up almost every time growth outruns profitability at the unit level. That's not a coincidence. It's a structural warning sign that shows up in the math before it shows up in the bank balance.
Core Metrics and the Exact Formulas That Matter
Contribution margin is the foundation. It's revenue per unit minus the variable costs tied directly to that unit, things like payment processing fees, hosting or infrastructure costs, customer support hours, fulfillment and shipping, and any third-party licensing tied to usage. Fixed costs, like your office lease or your VP of Engineering's salary, don't belong in this calculation. If contribution margin is negative, no amount of scale fixes the business. You're paying to lose money faster.
Lifetime value (LTV) is where most founders miscalculate. LTV should be built on gross profit, not revenue. CRV's guidance on LTV/CAC is blunt about this: calculating LTV on revenue alone ignores the real cost of delivering and supporting that customer, and it inflates the ratio investors are using to judge you. The formula:
- LTV (cohort method): sum of monthly gross-margin contribution across the customer's actual lifespan, tracked cohort by cohort.
- LTV (formula method): (ARPU × gross margin %) ÷ monthly churn rate.
- CAC: total sales and marketing spend for a period ÷ new customers acquired in that period. Calculate it both blended (all channels) and by individual channel, since blended CAC hides which channels are actually profitable.
- LTV:CAC ratio: LTV ÷ CAC. This tells you how many dollars of gross profit you generate per dollar spent acquiring the customer.
- Payback period: CAC ÷ monthly gross margin per unit. This tells you how many months it takes to recover what you spent to acquire that customer.
Pro Tip: Always calculate CAC at the channel level before you calculate it blended. A blended CAC of $80 can hide a paid-search channel running at $220 and an organic-referral channel running at $12. Averaging them tells you nothing actionable.
An LTV:CAC ratio near 3:1 is the benchmark most investors reference when they open a data room, though the number alone doesn't tell the full story, which the next section covers.
How Do You Calculate Unit Economics Step by Step?
Here's a worked example using a hypothetical B2B SaaS company, "Cohort A," a group of 100 customers who signed up in the same month.
Step 1: Define the unit, window, and data sources. The unit is a paying account. The window is trailing 12 months. Data comes from three places: the billing export (revenue collected), the usage export (support tickets and infrastructure consumption tied to that account), and the marketing spend ledger (channel-level acquisition cost for that cohort).
Step 2: Gather the raw inputs.
| Metric | Value |
|---|---|
| Customers in cohort | 100 |
| Average revenue per account per month | $500 |
| Gross margin (after hosting, support, payment fees) | 0.75 |
| Monthly churn rate | 3% |
| Total CAC spend for cohort acquisition | $40,000 |
Step 3: Run the math.
- Monthly gross-margin contribution per account: $500 × 0.75 = $375.
- LTV using the formula method: $375 ÷ 0.03 = $12,500 per customer.
- CAC per customer: $40,000 ÷ 100 = $400.
- LTV:CAC ratio: $12,500 ÷ $400 = 31.25:1.
- Payback period: $400 ÷ $375 = 1.07 months.
That ratio looks almost too good, and in a real diligence conversation, an investor would ask why. Usually the answer is an unrealistic churn assumption, so test it.
LTV drops to $375 ÷ 0.06 = $6,250, and the ratio falls to 15.6:1. Still healthy, but the swing shows how sensitive LTV is to a churn assumption that's often estimated from thin early data.
Assumptions to disclose alongside any number like this: gross margin percentage and what's included in it, the churn rate basis (logo churn versus revenue churn), and which acquisition channels the CAC figure covers. Leave any of those out and the number is not defensible in front of a diligence team.
How Investors Read Unit Economics Investing Signals
Investors don't just check whether the ratio clears 3:1. They read the trend line and the coverage behind it.
Benchmarks shift by stage and model. Seed-stage companies get more slack on absolute numbers because sample sizes are small, but Series A investors expect payback under 12 to 18 months for most SaaS businesses, with marketplaces judged more on contribution margin per transaction than customer-level LTV, since marketplace retention behaves differently on the buyer and seller sides. A D2C brand gets judged on repeat-purchase rate feeding directly into LTV, since a single-purchase customer has a fundamentally different economic profile than a subscriber.
A high LTV:CAC ratio paired with a long payback period is a specific red flag experienced investors watch for. A 24-month payback period demands heavy external financing to fund the gap between spending on acquisition and collecting the margin back, even when the eventual ratio looks strong on paper. Growth that requires that much runway just to break even on each cohort is fragile the moment fundraising conditions tighten.
Trajectory usually matters more than any single snapshot at the early stage. A cohort with a 2:1 ratio that's improving quarter over quarter often earns more investor confidence than a static 4:1 that hasn't moved. What investors actually want to see in a data room:
- Cohort retention charts broken out by signup month, not a single blended curve.
- Channel-level CAC, not one blended number covering every acquisition source.
- A payback trend across the last four to six quarters, showing direction.
- Explicit disclosure of what percentage of customers or spend the CAC coverage.
Data Integrity Rules That Keep Your Numbers Defensible
Founders lose credibility in diligence not because their unit economics are bad, but because the numbers can't be reproduced when an investor asks a follow-up question. Unit economics functions like an audit: every figure needs to trace back to a specific, joinable data source, or it collapses under scrutiny.
A few operational rules make the difference between a defensible pack and a shaky one:
- Lock the unit, the measurement window, and the CAC definition in writing before you calculate anything, and use the same definitions every time you recalculate.
- Publish the exact variable-cost stack behind your contribution margin, line by line, so no one has to guess what's included.
- Never join billing data to usage data at mismatched grains. Spreading an annual invoice evenly across twelve months when usage was front-loaded will distort your monthly contribution figures.
- Join refunds and credits back to the original customer key. A refund that isn't linked back to its cohort quietly inflates that cohort's apparent LTV.
- Report your unmatched rate, meaning the percentage of billing rows that couldn't be joined to a usage row, rather than hiding it.
Pro Tip: *Get a finance-signed reconciliation note before you headline your payback period to investors.
Understanding these joins matters just as much as understanding the profitability ratios that feed into contribution margin in the first place. Get the inputs wrong and every formula downstream inherits the error.
Turning the Numbers Into Priorities and a Pitch
Once you know where your unit economics stand, three levers move them: increase LTV, decrease CAC, or shorten payback. Increasing LTV usually means reducing churn, building an upsell path, or testing price increases on new cohorts before touching existing ones. Decreasing CAC means optimizing conversion rates on your highest-volume channel or shifting spend toward channels with a lower blended cost. Shortening payback often comes down to pushing customers toward annual plans, which collects the cash faster, or speeding up onboarding so customers reach full usage sooner.
Sequencing matters more than most founders think:
- If your LTV:CAC ratio sits below 3:1 or your payback exceeds your stage's benchmark, fix the underlying model before you spend another dollar on acquisition volume. Scaling a broken unit just multiplies the loss.
- Bootstrapped companies without a deep capital cushion should prioritize payback compression over LTV maximization, since a long payback period is what actually kills cash flow.
- Venture-backed companies with runway can tolerate a longer payback if the LTV:CAC trajectory is visibly improving cohort over cohort.
For board packs and fundraising decks, investors expect five specific deliverables: the LTV:CAC ratio with its underlying assumptions stated, a cohort retention chart, CAC broken out by channel, a payback trend across recent quarters, and a sensitivity analysis showing how the numbers move under a worse churn or CAC assumption. A DuPont-style breakdown of the drivers behind your margins can strengthen that pack further, since it connects unit-level economics to the return metrics investors ultimately care about at the company level.
Building a Reproducible Workflow Founders Can Actually Maintain
The minimum evidence pack is smaller than most founders assume: a billing export, a usage extract, a documented variable-cost stack, and a written CAC definition covering which channels and spend periods it includes. Starting from CSV exports works fine before you've built a full data warehouse. The join logic matters more than the tooling.
Version each pack by quarter so investors can see the trend line, not just a single snapshot. That version history is often what separates a credible fundraising conversation from a defensive one.
For comparing how unit economics stack up against other financial signals across public companies, a standardized scoring tool speeds up the sanity check. A standardized scoring tool that rates companies on profitability and financial health fundamentals side by side can give founders and early-stage investors a fast reference point for how contribution-margin discipline shows up further along a company's life cycle, without replacing the reconciled source rows a real diligence process demands.
Your Next Move on Unit Economics Investing
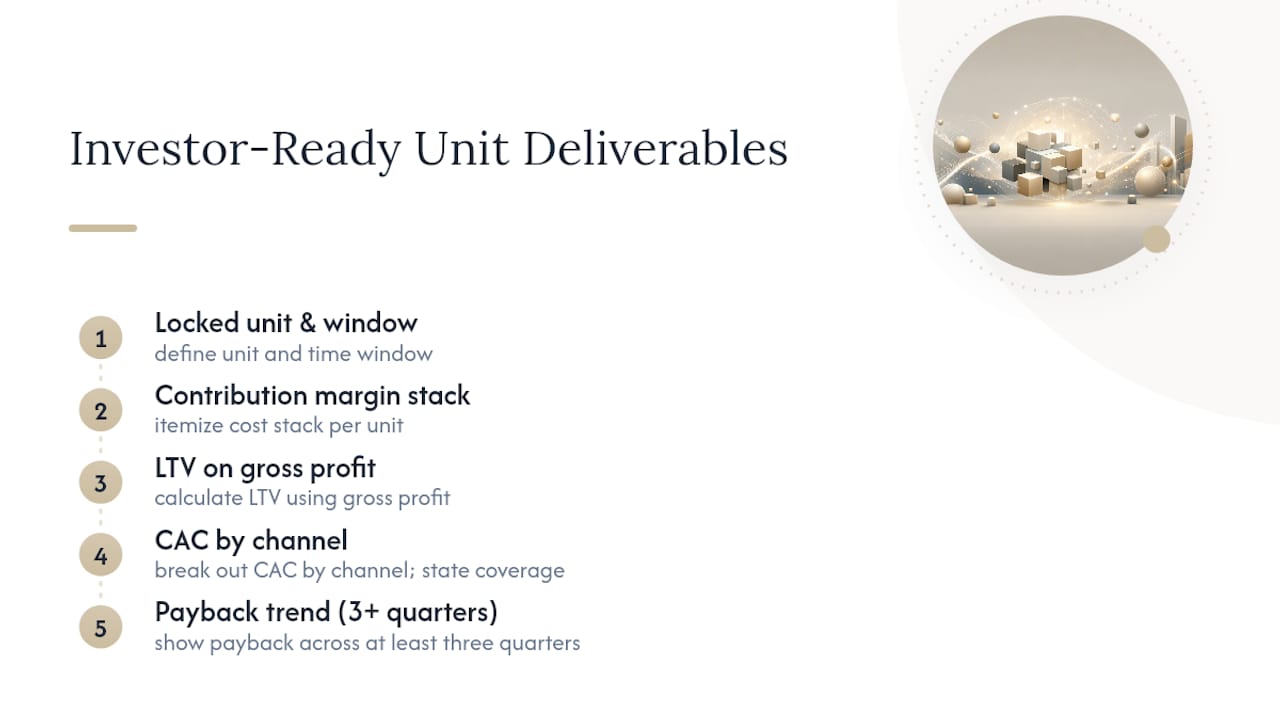
Before you take this to investors, deliver five things: a locked unit and window definition, contribution margin with its cost stack itemized, LTV calculated on gross profit, CAC broken out by channel with coverage stated, and a payback trend across at least three quarters. Investors will use these artifacts to check your math independently, not just accept your ratio at face value. Recalculate every quarter, or immediately after any pricing, channel, or major retention change, since a number that's six months stale is worth less than an honest current estimate.
If you want a faster way to sanity-check your company's fundamentals against public comparables while you build that pack, Oracle Investments' Premium Annual plan gives you side-by-side scoring across profitability, valuation, and financial health, drawing on investing principles from Warren Buffett, Charlie Munger, and Peter Lynch. It won't replace your reconciled billing rows, but it's a useful gut check while you're building the real thing.
The Gap Between Spreadsheet Math and an Investor-Ready Pack
Most unit economics content stops at the formulas, as if getting the math right is the hard part. It isn't. The hard part is making the number survive a follow-up question, and that's where most founders get caught flat.
The conventional advice tells founders to hit a 3:1 LTV:CAC ratio and call it done. That's incomplete advice. It's a fragile one wearing a strong number's clothes. Investors who've sat through enough diligence calls know the difference immediately, and they'll ask for the cohort chart and the channel breakdown before they trust the headline ratio.
If you take one thing from this, prioritize the reconciliation over the ratio. Build the billing-to-usage join first, disclose your unmatched rate honestly, and get a finance-signed cost stack before you obsess over whether your number is 2.8 or 3.2. A defensible 2.8 beats an indefensible 4.0 in every diligence conversation that matters.
— Matt
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- LTV/CAC guidance — CRV
- Understanding unit economics & why it matters — Mercury
- Unit Economics for Fundraising Explained — Qubit Capital
- Unit Economics Analytics: 2026 Field Guide — Infinisynapse
FAQ
What Is an Example of Unit Economics?
If that customer cost $400 to acquire, the payback period is just over one month, and the unit economics are strong.
What Are the Main Types of Investment Metrics Used in Startup Analysis?
Founders and investors typically track contribution margin, customer lifetime value (LTV), customer acquisition cost (CAC), the LTV:CAC ratio, payback period, gross margin, and churn rate. These seven metrics together form the core unit economics analysis investors expect in a data room.
What Does "Unit Economics" Mean in the Context of a Business Pitch Like Shark Tank?
On pitch shows, founders are often pressed on the profit or loss from selling one unit of their product after accounting for materials, packaging, and shipping. That's the same contribution-margin logic institutional investors apply, just at a consumer-product scale instead of a subscription or transaction scale.
How Do I Calculate Unit Economics for My Company?
Pick your unit (customer, subscription, or order), calculate contribution margin by subtracting variable costs from revenue per unit, then build LTV on gross profit divided by churn rate, and divide CAC by monthly gross margin per unit to get your payback period. Recalculate quarterly or whenever pricing, channels, or retention shift materially.