The Shiller CAPE ratio divides a stock index's current real price by the average of its last ten years of inflation-adjusted earnings, smoothing out business-cycle noise to reveal how expensive the market really is. It works as a long-horizon valuation gauge, not a short-term timing signal, and the canonical version comes from Robert Shiller's Yale dataset, though several refined variants now compete for attention.
TL;DR:
- To reproduce a figure, use month end prices, ten years of inflation adjusted earnings, and a consistent CPI series; average earnings arithmetically.
- CAPE forecasts real returns more reliably over ten to twenty years than over one or two, so use it to set expectations, not time trades.
- Before comparing a reading with history, check whether it uses reported or adjusted earnings, price only or total returns, and which CPI series.
- Pair CAPE with bond yields or free cash flow yield, and use it to guide allocation adjustments rather than all in or all out moves.
Table of Contents
- How to calculate the Shiller CAPE ratio step by step
- What does the research say about CAPE's forecasting power?
- Criticisms and improved CAPE variants worth knowing
- How to apply CAPE in your own portfolio decisions
- Where to find and reproduce Shiller's CAPE dataset
- Alternative valuation models that build on or replace CAPE
- What macroeconomic forces push CAPE up and down
- How CAPE behaved through major market cycles and recessions
- Real-world examples of CAPE shaping investment thinking
- Limitations and misconceptions about using CAPE to time the market
- CAPE compared with the standard P/E ratio and other valuation gauges
- A straight read on where CAPE fits today
- How Oracle Investments helps you apply CAPE and other valuation metrics
- FAQ
- Sources
How to calculate the Shiller CAPE ratio step by step
Reproducing CAPE from scratch takes three data series: the index's monthly price, ten years of reported earnings for that index, and a consumer price index to strip out inflation. Each one needs to span the same calendar window or the math falls apart.
- Collect monthly price data for the index along with trailing earnings for each of the past ten years.
- Convert each year's nominal earnings into today's dollars using the CPI series, so a 2016 earnings figure gets adjusted to current purchasing power.
- Average those ten CPI-adjusted earnings figures using a simple arithmetic mean, not a weighted one.
- Divide the current real price by that ten-year real earnings average to get the CAPE value.
Analysts typically use month-end closing prices rather than intraday figures, matching the convention Shiller's own series follows. Earnings data before 1926 gets interpolated from annual figures since monthly reports did not exist yet, a detail that matters if you are reconstructing the series by hand rather than pulling it from Shiller's maintained file. The choice of CPI vintage also matters: revised CPI figures differ slightly from the originally published numbers, and Shiller's dataset uses a spliced series to keep the history consistent across methodology changes at the Bureau of Labor Statistics.
What does the research say about CAPE's forecasting power?
The core finding behind CAPE traces back to Campbell and Shiller's original work and its later extensions through NBER research: a high starting CAPE tends to coincide with lower real returns over the following decade, and a low starting CAPE tends to coincide with higher ones. That relationship holds up statistically, but its strength depends entirely on the time horizon you are testing.
Academic work documents a negative relationship between starting CAPE levels and subsequent 10-year real returns, with NBER research showing meaningfully higher explanatory power at that horizon than at one or two years out. Over a single year, CAPE tells you almost nothing useful about what the market will do next. Stretch the window to ten or twenty years and the relationship firms up considerably, which is exactly why Shiller designed the metric around a decade of smoothed earnings rather than a single trailing year.
That horizon dependence is the single most important thing to internalize about CAPE. A reading of 30 does not mean a crash is imminent, and a reading of 15 does not mean a rally starts tomorrow. It means the probability-weighted expectation for returns over the next decade or two tilts lower or higher than average, nothing more precise than that.
Researchers also test for structural breaks, periods where the relationship between CAPE and future returns seems to shift. Accounting rule changes since the 1990s, different payout behavior from companies favoring buybacks over dividends, and shifts in how earnings get reported all raise the question of whether today's CAPE readings mean the same thing they did a century ago. That concern is legitimate enough that it has spawned an entire literature of adjusted variants, which the next section covers.

Criticisms and improved CAPE variants worth knowing
Jeremy Siegel's critique, summarized in CFA Institute research, argues that GAAP accounting changes since the 1990s, including mark-to-market rules adopted after major write-downs, can understate reported earnings relative to older accounting standards. If the earnings denominator is artificially depressed, CAPE looks artificially high, which could make the market seem more overvalued than it really is. Siegel's proposed fix uses more consistent earnings definitions, sometimes drawn from national accounts data, to correct for this.
A second major adjustment is total-return CAPE, which reinvests dividends back into the price series rather than letting them flow out. This matters because payout ratios have fallen over the decades as companies shifted toward buybacks, and a standard price-only CAPE can look more expensive over time purely because less cash leaves the company as dividends.
Payout-adjusted CAPE, sometimes called P-CAPE, addresses the same underlying issue from a different angle by scaling earnings for changes in payout policy directly.
Before trusting any published CAPE figure, confirm:
- Which earnings definition it uses (reported GAAP, operating, or a smoothed alternative).
- Whether it is price-only or a total-return variant.
- Which CPI vintage and splice method adjusted the earnings for inflation.
Pro Tip: Always check the data vintage and earnings definition behind a quoted CAPE number before comparing it to a historical average; mixing vendors or methodologies produces numbers that look comparable but are not.
How to apply CAPE in your own portfolio decisions
CAPE earns its place in a strategic allocation conversation, not a trading terminal. A high reading relative to history suggests tempering expected equity returns over the next decade and potentially leaning toward diversification; a low reading suggests the opposite. Neither justifies an all-in or all-out move based on this single number.
The metric works best alongside other signals rather than alone. Its inverse, the cyclically adjusted earnings yield, converts CAPE into a percentage that compares more naturally against the risk-free rate on government bonds, giving you a rough equity risk premium estimate. Pairing CAPE with free cash flow yield adds a check grounded in actual cash generation rather than accounting earnings alone.
Before acting on any CAPE reading, work through these questions:
- What horizon am I actually investing for, and does it match the 10-to-20-year window where CAPE has real evidence behind it?
- Which CAPE variant am I looking at, standard, total-return, or payout-adjusted, and does that choice change the signal?
- How old is the data vintage behind this number, and has the underlying earnings or CPI series been revised since?
- Am I using this to set return expectations and allocation tilts, or am I tempted to use it as a timing trigger it was never built for?
Running through that checklist turns a single ratio into a reasoned input rather than an excuse for a snap decision.
Where to find and reproduce Shiller's CAPE dataset
Shiller's Yale data page remains the canonical source: a maintained spreadsheet with monthly S&P price, dividends, earnings, and CPI stretching back to 1871. Anyone reproducing CAPE from scratch should start here rather than piecing together separate vendor feeds.
A few reproduction pitfalls come up often:
- Pre-1926 earnings are interpolated from annual data since monthly figures were not reported that far back.
- CPI series get spliced across methodology changes at the Bureau of Labor Statistics, so matching Shiller's exact splice points matters for consistency.
- The file gets revised periodically as new monthly data arrives, so a CAPE value calculated last year may shift slightly when earnings get restated.
When citing a CAPE figure in research or analysis, note the dataset vintage, the download date, alongside the number itself. A CAPE of 32 calculated from 2024 data and one calculated from a 2026 revision are not guaranteed to be identical readings.
Alternative valuation models that build on or replace CAPE
CAPE is not the only cyclically adjusted metric in circulation, and several alternatives address its specific blind spots. Cyclically adjusted EBITDA multiples apply the same smoothing logic to earnings before interest, taxes, depreciation, and amortization rather than net income, which sidesteps some of the accounting and leverage distortions that affect reported earnings. This approach tends to appeal to analysts comparing companies or sectors with very different capital structures, since EBITDA strips out financing decisions that net income does not.
Relative CAPE measures compare a sector's or country's CAPE against its own long-run history or against other sectors, rather than against an absolute threshold. This sidesteps the question of whether today's "normal" CAPE level matches the level from a century ago, a debate the structural-break concerns around Siegel's critique make relevant.
Combining CAPE-style metrics with free cash flow yield offers another path, since cash flow is harder to manipulate through accounting choices than reported earnings. A free cash flow based valuation lens often gets used precisely because it corrects for some of the same payout and accounting concerns that total-return CAPE and P-CAPE attempt to address from the earnings side.
None of these alternatives replaces CAPE outright. Each trades one set of assumptions for another, and the right choice depends on whether you are comparing single companies, whole sectors, or broad markets across different eras. The common thread across all of them is the same discipline CAPE introduced: smooth the denominator, strip out inflation, and judge valuation against a long enough window to matter.

What macroeconomic forces push CAPE up and down
CAPE moves with a combination of earnings trends, interest rates, and inflation expectations rather than any single driver. Falling real interest rates tend to coincide with rising CAPE readings, since lower discount rates on future cash flows support higher prices relative to current earnings. The opposite holds when rates climb and investors demand a bigger cushion for the same earnings stream.
Inflation itself plays a double role. Because CAPE's earnings component is already inflation-adjusted, moderate and predictable inflation does not distort the ratio much on its own. Sharp or unexpected inflation spikes, though, tend to compress price-to-earnings multiples broadly as investors reprice future cash flows at higher discount rates, which shows up in CAPE readings too.
Corporate profit margins matter as well. A multi-decade rise in margins, driven by globalization, lower corporate tax rates, and technology-driven productivity gains, has lifted the earnings side of the CAPE equation over recent decades. When margins compress during a recession or a shift in trade or tax policy, the earnings average takes years to reflect that change fully, which is part of why CAPE moves slowly compared to a simple trailing P/E.
Monetary policy cycles add another layer. Periods of aggressive rate cuts tend to coincide with multiple expansion across the market, pushing CAPE higher even when earnings growth stays modest. Investors budgeting around inflation and rate shifts in their own household finances face a related challenge, matching spending plans to a changing cost environment, which the inflation budgeting guidance from financial coaching resources addresses from the personal finance side rather than the market valuation side.
How CAPE behaved through major market cycles and recessions
CAPE's history includes some of the most studied valuation extremes in market history. The late 1990s dot-com period pushed CAPE to levels far above its long-run average, driven by surging technology earnings expectations that did not fully materialize once the smoothing window caught up with reality. The subsequent decade delivered real returns well below the market's historical norm, consistent with the negative relationship NBER research documents between high starting CAPE and lower subsequent 10-year returns.
The 2008 financial crisis compressed CAPE sharply as both prices and trailing earnings fell, though the ten-year averaging smoothed some of the earnings collapse compared to a simple trailing P/E, which spiked briefly as earnings cratered faster than prices.
The recovery that followed produced one of the more debated CAPE episodes, a prolonged period of readings above historical medians through much of the 2010s and into the 2020s. Whether that reflects a genuine valuation regime shift, tied to the structural changes Siegel's critique raises, or a simple overvaluation that eventually corrects, remains an open question among researchers rather than a settled one.
Each cycle reinforces the same lesson: CAPE describes starting conditions, not timing. High readings preceded long stretches of weaker returns in some periods and preceded further gains for years in others, which is exactly what a horizon-dependent, probabilistic signal should look like rather than a precise forecast.
Real-world examples of CAPE shaping investment thinking
Robert Shiller himself referenced elevated CAPE readings in warnings about the dot-com market in the late 1990s, well before the subsequent correction, an episode often cited as an early validation of the metric's long-horizon value. The ratio's climb into unusually high territory did not predict exactly when the market would turn, but it flagged that starting valuations were stretched relative to a century of history.
Institutional allocators have used CAPE-style thinking to inform strategic rather than tactical decisions, adjusting long-run capital market return assumptions based on where current CAPE sits relative to its historical range. A pension fund or endowment setting a 10-year return assumption, for example, might lower its expected equity return when CAPE sits well above its long-run median, without attempting to time an exit from equities altogether.
Individual investors have applied the same logic at a smaller scale, using elevated CAPE readings as a prompt to rebalance toward target allocations rather than chase recent gains, or to size new contributions with more caution during apparent valuation extremes. The discipline works the same way for a retiree checking whether retirement income projections still hold given today's starting valuation as it does for an endowment committee.
The common thread across these examples is restraint: CAPE informs the size and pacing of decisions already grounded in a plan, rather than triggering decisions on its own.
Limitations and misconceptions about using CAPE to time the market
The single most common misuse of CAPE treats it as a market-timing trigger, buying when it is low and selling when it is high over short windows. The evidence does not support that use. Short-horizon predictive power is weak, and investors who exited equities the first time CAPE crossed an arbitrary threshold in past decades often missed years of subsequent gains before any correction arrived.
A second misconception treats historical CAPE averages as a fixed, permanent benchmark. Siegel's accounting critique and the shift toward buybacks over dividends both suggest that the "normal" CAPE level may have shifted over the past several decades, which is part of why total-return and payout-adjusted variants exist in the first place.
A third misconception ignores the variant problem entirely, comparing today's standard CAPE against a historical average calculated under different earnings or payout assumptions. That comparison looks precise but is not actually apples to apples.
Finally, some investors expect CAPE to explain near-term volatility, interest rate surprises, or geopolitical shocks. It was never built to do that.
CAPE compared with the standard P/E ratio and other valuation gauges
A standard P/E ratio divides price by a single year's trailing or forward earnings, which makes it far more sensitive to short-term earnings swings than CAPE. During a recession, trailing P/E can spike as earnings collapse faster than prices, producing a misleadingly high reading at the exact moment stocks may be cheap on a longer view. CAPE's ten-year averaging smooths that distortion out, trading responsiveness for stability.
Forward P/E solves part of the earnings-collapse problem by using analyst estimates instead of trailing figures, but it introduces a different weakness: it depends on forecasts that can be overly optimistic or miss turning points entirely.
Price-to-book and price-to-sales ratios sidestep earnings volatility altogether by comparing price to balance sheet or revenue figures, which can be useful for cyclical or unprofitable companies where earnings-based ratios break down. Neither corrects for inflation the way CAPE does, though, which limits their usefulness for multi-decade historical comparisons.
Free cash flow yield offers a cash-based alternative that is harder to distort through accounting choices than net income, making it a useful complement rather than a replacement for CAPE-style analysis. The right approach for most investors blends several of these lenses rather than leaning on any single ratio, which is the same logic behind a broader valuation metrics checklist worth running through before acting on any one number.
A straight read on where CAPE fits today
CAPE earns its reputation as a long-run orientation tool, not because it predicts next year's returns but because a decade of smoothed, inflation-adjusted earnings filters out exactly the noise that makes shorter ratios unreliable. The variant matters as much as the number: a standard CAPE and a total-return CAPE can tell different stories about the same market, so checking which one sits behind a historical median before comparing today's reading against it is not optional. We approach valuation signals favoring rule-based, transparent inputs over black-box scores, because a number you cannot audit is a number you cannot really trust.
— Matt
How Oracle Investments helps you apply CAPE and other valuation metrics
Reading a single ratio in isolation only gets you so far. Our app scores stocks on the fundamentals that actually drive long-run value, profitability, valuation, and financial health, so you can see where a company sits on a rule-based valuation scale without building a spreadsheet from scratch.
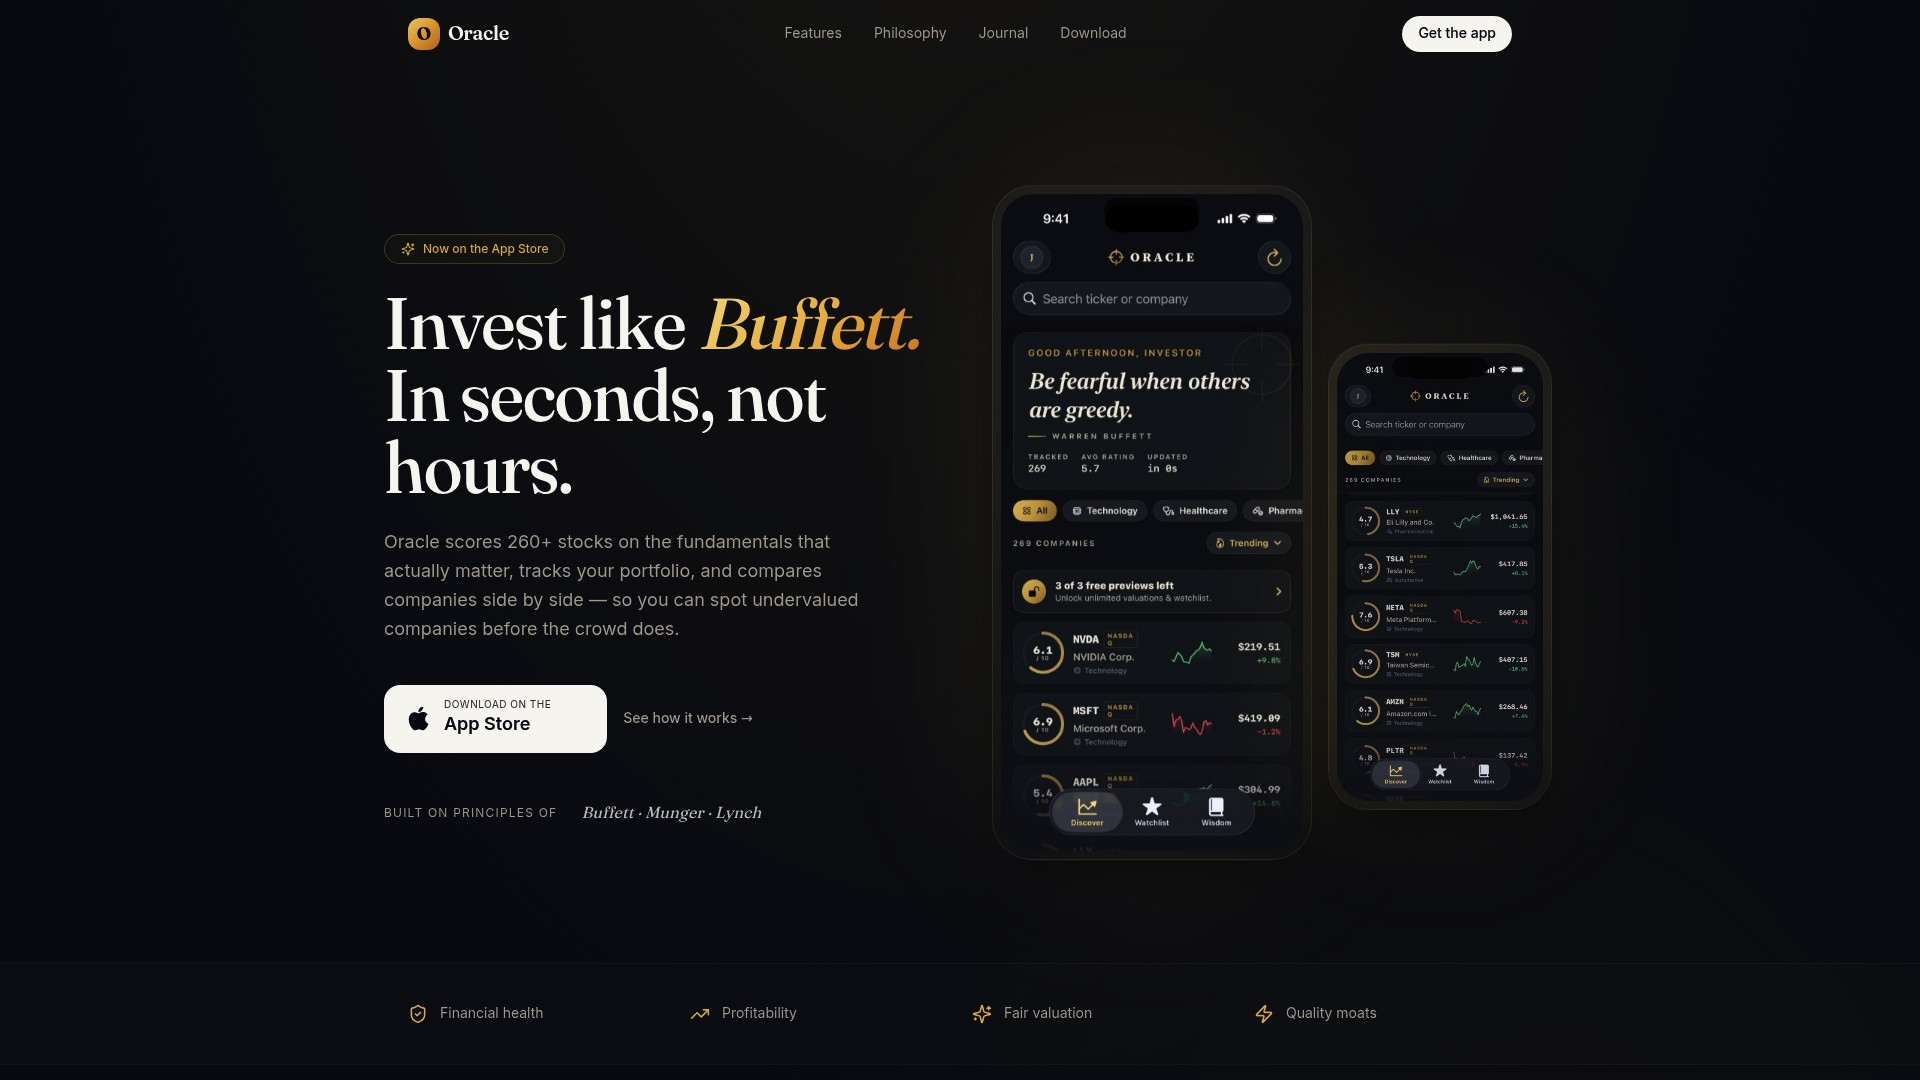
- Compare valuation signals across companies side by side instead of checking one ticker at a time.
- See the inputs behind every score.
- Track your portfolio alongside the same fundamentals that inform long-horizon CAPE-style thinking.
| What you get | Why it matters |
|---|---|
| Scores across stocks | Faster comparison than building ratios manually |
| Transparent scoring inputs | You see what drives each rating |
| Portfolio tracking | Keep valuation context alongside your holdings |
Pro Tip: Pair a long-run valuation view like CAPE with company-level fundamentals before deciding where new contributions go; the market-level signal tells you the climate, the company-level score tells you the specific opportunity.
Our Premium Annual plan unlocks the full comparison and tracking toolkit if you want to put this thinking into practice today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the CAPE ratio for each country?
Researchers have extended CAPE-style analysis beyond the US to other countries and sectors by applying the same ten-year real-earnings averaging to local market indexes, and some NBER research constructs comparable sector and relative valuation series. Country-level CAPE values are not standardized across a single provider, so figures vary depending on the earnings and CPI data used for each market.
What is a good price to earnings P/E ratio?
There is no single universal "good" P/E, since fair value depends on growth expectations, interest rates, and the sector in question. A standard P/E explainer is a better starting point than a fixed number, since comparing a company's P/E to its own history and to close peers tells you more than any isolated threshold.
What is a good market capitalization?
Market capitalization size does not have a universal "good" level either, since it depends on your goals: larger companies tend to offer more stability and liquidity, while smaller ones can offer more growth potential alongside more volatility. The right size mix depends on your own risk tolerance and time horizon rather than any fixed cutoff.
What does Warren Buffett say about PE ratio?
Warren Buffett has emphasized looking past a single P/E snapshot toward a company's durable earnings power, competitive position, and the price you pay relative to that long-run earning capacity. That philosophy lines up with the same principle behind CAPE: smoothing out short-term earnings noise reveals a clearer picture of what you are actually paying for.