Insurance float is the money an insurer holds between collecting premiums and paying claims, and it can be invested in the meantime. Float investing is therefore a way of describing how an insurer earns money on other people's money, and the quality of that float depends on one thing: whether the insurer's underwriting loses money or earns it. As a stock investor, you judge the insurer by the cost of its float and by what it does with the cash. Oracle Investments is built for that kind of fundamentals-first check: scored profitability, valuation and financial health for over 260 stocks, side by side.
TL;DR
- Float is money held for policyholders before claims are paid. Insurers invest it and keep the returns.
- Float is not free. Its cost is the underwriting loss (or gain) measured against the float. A gain makes the float cost less than nothing.
- U.S. insurers hold most of their portfolio in bonds, with a smaller share in stocks and loans.
- Berkshire Hathaway made float famous: its float reached about $171 billion at the end of 2024.
- To judge an insurer, look at underwriting results over many years, float growth, and the quality of its investments, not at float size alone.
Table of Contents
- What insurance float is, in plain terms
- Why float is not free money
- How insurers invest their float
- The Berkshire Hathaway example
- How to evaluate float when you analyze an insurer's stock
- Float versus borrowing to invest
- Where float fits in a value-investing approach
- Our perspective
- Put the checks into practice
- FAQ
- Sources
What insurance float is, in plain terms
An insurance company sells a promise: if something bad happens, it pays. The customer pays for that promise up front, in premiums. The claims come later, sometimes months later, sometimes years later, as with a liability lawsuit or a major accident that takes a long time to settle.
That gap is the float. An academic paper on property and casualty (P&C) insurers defines float as the money an insurer holds between receiving funds from policyholders and paying claims or letting policies expire. The same paper breaks it into its parts: unpaid claims (both reported and incurred-but-not-reported) and unearned premiums, less premiums still owed to the insurer, agents' balances and reinsurance recoverables. Reinsurance is insurance that insurers buy from other insurers to share big risks.
Two balance-sheet items matter most, and the National Association of Insurance Commissioners (NAIC), the U.S. state regulators' standard-setting body, defines both in its glossary:
- Loss reserves: the amount set aside for claims that have already happened but have not been paid yet.
- Premiums: the money charged for coverage, based on the expected loss.
In the P&C data the researchers studied for 1996 to 2022, unpaid losses were the main driver, making up roughly 81% to 89% of float, with unearned premiums adding about 25% to 30% (the parts exceed 100% because some items are subtracted). Float as a share of annual premiums fell from about 155% in 1996 to about 140% in 2022, according to the same study.
A simple worked example
Say an insurer collects $100 million in premiums on January 1 for policies covering the year. It expects to pay claims of $70 million, and those claims are paid on average 18 months later. For that stretch of time the insurer holds the cash and invests it. If the portfolio earns 4% a year, the insurer earns about $4 million a year on $100 million, before any claims are paid. The numbers are illustrative, not from a real company, but the mechanism is the one that drives real insurers.

Why float is not free money
It is tempting to read float as a loan with no interest. That is only true when the insurer prices risk well. Float comes with an obligation: the money must be there when claims come due.
The cost of float is measured by underwriting results. Underwriting is the core insurance business of taking in premiums and paying claims and expenses. If an insurer collects $100 million in premiums and pays out $95 million in claims and expenses, it has a $5 million underwriting profit. Its float cost less than nothing, because it was paid to hold the money. If it pays out $105 million, it has a $5 million underwriting loss, and that loss is the price it paid for the use of the float. Whether the float was worth having depends on whether the investment return on it exceeds that price.
Berkshire Hathaway's filings use exactly this logic. In its 2008 annual report, the company measured the cost of float as the ratio of underwriting gain or loss to average float, and reported that it was negative for three straight years because underwriting produced gains. A negative cost means the insurer was paid to hold the funds.

How insurers invest their float
Insurers invest premiums and reserves, along with their own capital, in a portfolio that mirrors the kind of promises they have made. The NAIC's year-end 2025 report says U.S. insurers held $9.6 trillion in cash and invested assets, up 6.7% for the year and the largest annual increase in four years. The mix, at book (adjusted carrying) value:
| Asset type | Amount | Share of portfolio |
|---|---|---|
| Bonds | $5.7 trillion | 59.8% |
| Common stocks | $1.3 trillion | 13.6% |
| Mortgage loans | $868 billion | 9.1% |
| Other long-term investments (Schedule BA) | $639 billion | 6.7% |
| Cash and short-term investments | 6.2% |
The NAIC notes that bonds fell below 60% of the portfolio for the first time, while common stocks grew 11.2% over the year. These figures cover the whole U.S. industry, life insurers included, so they are a backdrop and not a template for any one company.
Why the mix differs between insurers
The liability profile drives the portfolio. Insurance Europe explains that predictable, long-term obligations such as annuities can be matched with less liquid, higher-yielding assets, while shorter-term, less predictable P&C liabilities call for more liquid and flexible portfolios. That is why a car insurer tends to hold safer, shorter bonds than an annuity writer, and why an insurer that holds a lot of stocks is making a deliberate choice about risk.
When the hunt for yield goes too far
Low interest rates push insurers to reach for return. A risk-regulator market briefing for the first quarter of 2026 notes that many U.S. insurers stretched for yield during the low-rate years by moving into less liquid, more complicated assets and longer-duration bonds. The same briefing urges regulators to check whether insurers' liquidity policies and stress testing kept pace with the market volatility of 2025. For you, the takeaway is simple: when you read an insurer's investment note, ask how easily the assets could be sold if claims spiked.
The Berkshire Hathaway example
The name most tied to float investing is Warren Buffett's Berkshire Hathaway. Berkshire's 2024 Form 10-K reports float growing from roughly $129 billion at the end of 2019 to roughly $171 billion at the end of 2024. In its 2024 shareholder letter, the company says its float has grown from $46 billion to $171 billion over the period it discusses, and says that with intelligent underwriting the float has a reasonable prospect of being costless. The same letter reports insurance underwriting earnings of $9,020 million in 2024 against $5,428 million in 2023.
The lesson is not that float alone makes a great business. Berkshire's version works because underwriting has generally been disciplined enough that the money is not expensive, and because the proceeds are invested for the long run. If you want to study how a company with a large float trades over time, you can look at Berkshire Hathaway historical stock data alongside the company's filings.
How to evaluate float when you analyze an insurer's stock
Float belongs in your analysis of an insurer, but it is one input among several. A practical checklist for a beginner:
- Check underwriting over a full cycle. One good year proves little, because catastrophe losses are lumpy. Look at five to ten years of underwriting profit or loss. Consistent profits suggest cheap or free float.
- Compare underwriting results to float. An underwriting loss of 2% of float is a cost of 2%. Ask whether the investment portfolio can reasonably earn more than that over time.
- Watch float growth. Growing float with stable underwriting means the insurer is writing more business without letting quality slip. Rapid growth with worsening results is a warning sign.
- Read the reserve notes. Unpaid-claim reserves are estimates. If past reserves keep turning out too low, the float was overstated and the cost is higher than it looked.
- Look at the asset mix. Compare bonds, stocks, mortgage loans and other long-term investments to the industry picture above. Heavy exposure to illiquid assets deserves a closer look.
- Then do the ordinary fundamentals. Profitability, valuation and financial health still decide whether the stock is worth buying at its price. A good float does not rescue an overpriced stock.
The steps for each insurer are done the same way, so comparing two or three side by side is the fastest way to see which one runs its float better. Oracle Investments is built around that kind of comparison: it scores over 260 stocks on profitability, valuation and financial health, and shows the inputs behind each score. Its ratings are rule-based and grounded in reported company fundamentals, not in AI guesses, so you can see why a company scored the way it did and judge the float-related numbers against the rest of the picture.
Float versus borrowing to invest
A common confusion is to treat float as leverage, like a margin loan. The two differ in important ways. A margin loan has a stated interest rate and a lender who can demand repayment when prices fall. Float has no stated interest, but its cost is hidden in the underwriting result, and it is not callable in the same way: the insurer pays claims as they come due. The risk is also different. Margin risk comes from market prices. Float risk comes from underwriting mistakes and from having to sell assets at a bad moment to pay claims.
That difference is why float works as a long-term source of investable money only for an insurer that prices risk carefully and keeps its portfolio liquid enough to meet claims. It is also why you, as an individual investor, cannot copy it. You can only own a share of a company that does it well.
Where float fits in a value-investing approach
Value investors like float businesses because the model is understandable: a company collects cash now, pays later and invests the difference. It also fits the checks that Buffett-style investors run before buying anything: durable earnings, sensible management and a fair price. If you are new to those checks, our Buffett investing rules piece walks through ten of them. For market-wide valuation context, the Buffett Indicator guide shows how to adjust your portfolio when the market looks stretched.
If you already own an insurer, think about how much of your portfolio it represents. A large insurance position carries catastrophe and interest-rate risk that you may not see in a headline earnings number. The portfolio risk assessment workflow is a practical way to check that, and the downside protection strategies piece covers what to do about it. Retirees leaning on dividend-paying insurers for income can pair this with the income-first retiree plan.
Our perspective
Float is a good idea to learn from because it forces you to ask a better question than "is this company growing?" It makes you ask what the growth costs and who is really funding it.
We built Oracle Investments around the same discipline. Our scores are rule-based and drawn from reported company fundamentals, and every input is shown, so you can see exactly why a company ranks where it does. There is no model guessing behind the number and no spreadsheet to build.
For an insurer, that means you can put the profitability, valuation and financial-health picture next to the float story and decide for yourself. We also bring in the thinking of Buffett, Munger and Lynch in the app, because understanding why a business model works matters as much as the number.
Matt
Put the checks into practice
Once you know what to look for in an insurer, the work is comparing candidates quickly. Oracle Investments scores over 260 stocks on profitability, valuation and financial health and lets you compare companies side by side, with real-time portfolio tracking for what you already own. The app is a subscription, purchased through the Apple App Store. Premium Annual is available on our site.
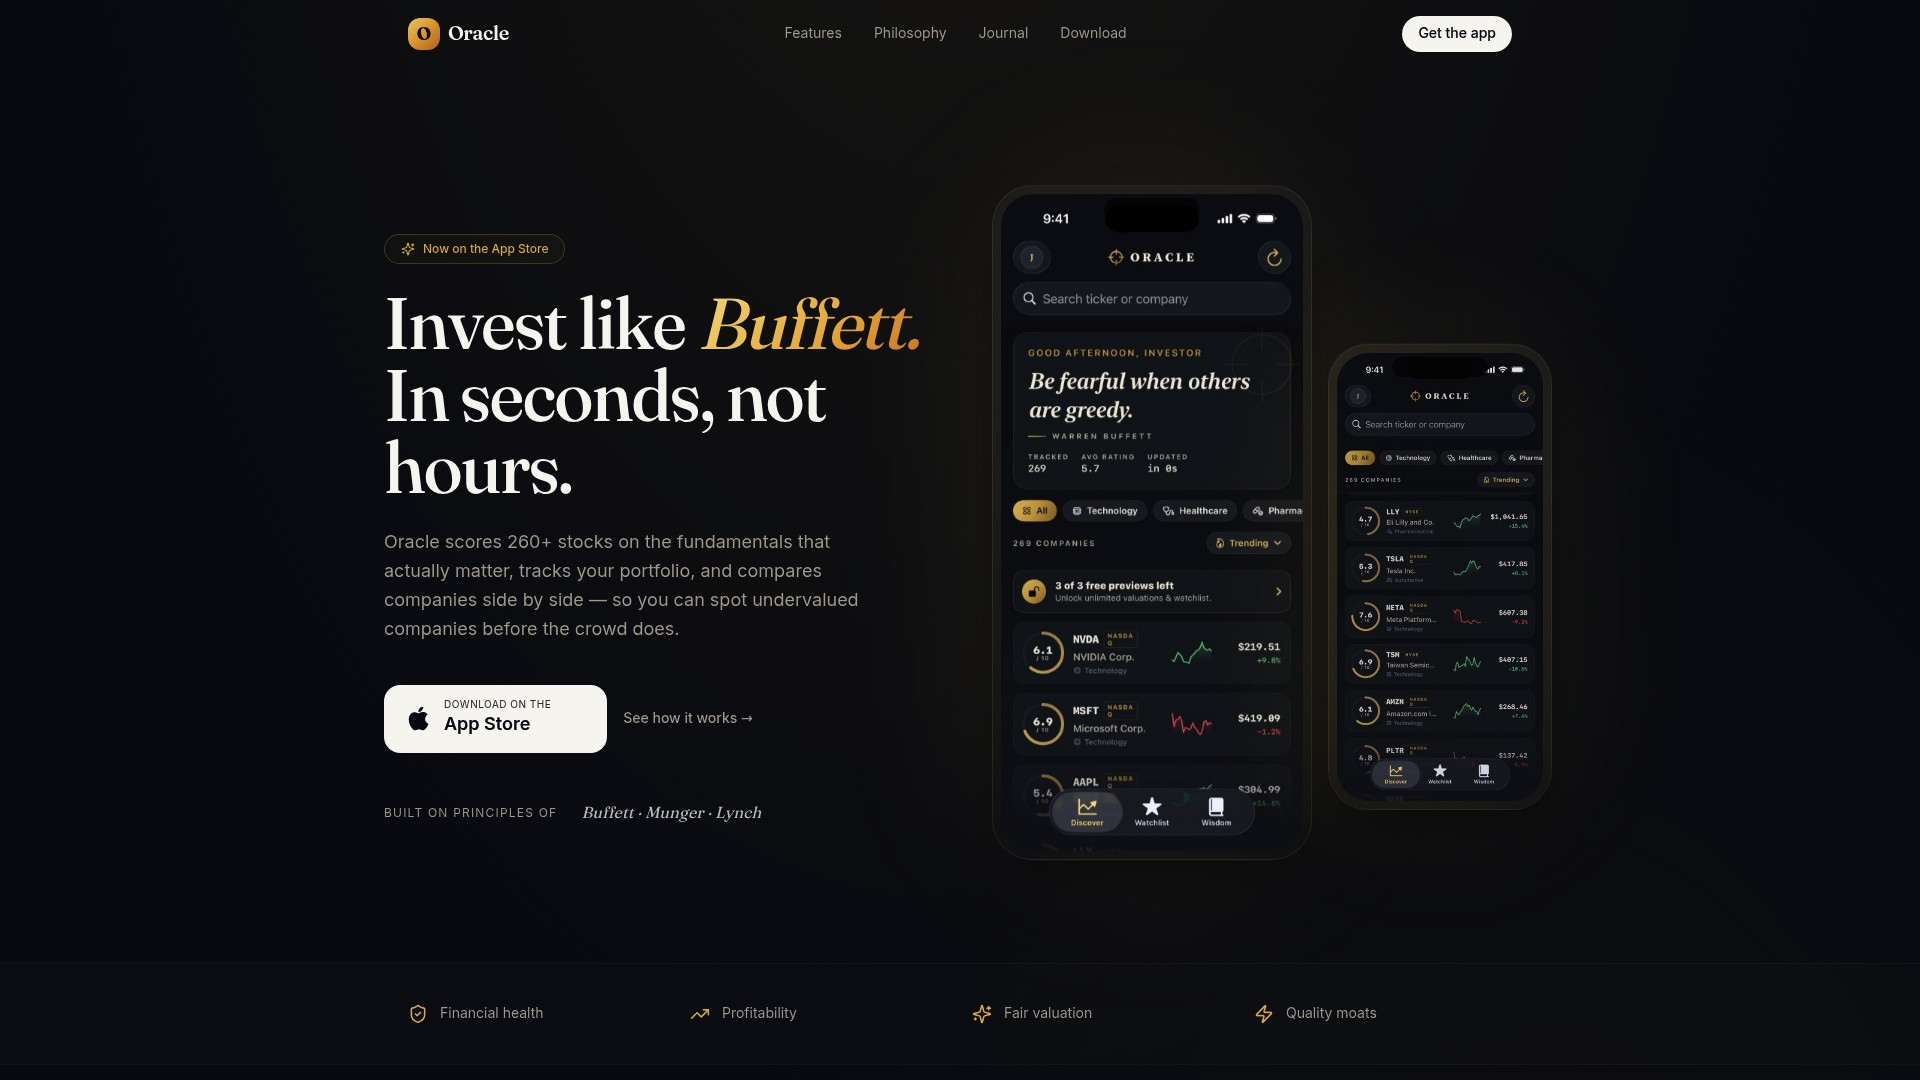
Beginners can start with the fundamentals and the value-investing lessons built into the app, and experienced investors can use the side-by-side view to check an insurer against its peers in seconds.
FAQ
What is insurance float?
Insurance float is the money an insurer holds after collecting premiums but before paying claims or letting policies expire. It is made up mainly of unpaid claim reserves and unearned premiums. The insurer invests it and keeps the returns, but it must have the money ready when claims come due.
Is insurance float free money for the insurer?
Not automatically. Its cost equals the insurer's underwriting loss, measured against the float. If the insurer earns an underwriting profit, the float costs less than nothing. If it pays out more than it collects, the loss is the price of using the float.
Where do insurance companies invest their money?
Mostly in bonds. The NAIC's year-end 2025 report puts bonds at 59.8% of U.S. insurers' $9.6 trillion in cash and invested assets, with common stocks at 13.6%, mortgage loans at 9.1% and other long-term investments at 6.7%. The exact mix depends on the type of insurance and how soon claims are expected.
Can individual investors use float to invest?
Not directly, because float belongs to insurers. You can own shares of an insurer that manages it well. Judge it by multi-year underwriting results, float growth, reserve quality and the investment portfolio, then compare it with other stocks on the usual fundamentals.
Sources
- Evidence from Property and Casualty Insurance (afajof.org)
- NAIC glossary of insurance terms
- NAIC year-end 2025 cash and invested assets report
- Insurance Europe: Investing from insurers' perspective
- Market Briefing, Q1 2026
- Berkshire Hathaway 2024 Form 10-K
- Berkshire Hathaway 2024 shareholder letter
- Berkshire Hathaway FY2008 Form 10-K (SEC)