Days to cover equals short interest divided by average daily trading volume, and it estimates how many trading days short sellers would need to buy back their positions. A higher reading points to greater short-squeeze risk and thinner liquidity, while a lower reading means short sellers could exit quickly without moving the price much; for more on managing these risks, see our guide to crypto loan liquidation mechanisms. FINRA publishes the short interest figures behind this ratio for U.S. equities.
TL;DR:
- Days to cover can overstate risk in stocks with very low average trading volume or recent trading anomalies.
- The ratio is updated twice monthly with some lag, so recent news or volume spikes may not be reflected in published figures.
- Interpreting high days-to-cover values requires considering float size, recent volume changes, and upcoming catalysts, not relying on a fixed threshold.
- Extreme or inflated ratios in OTC or thinly traded stocks may result from low denominator values rather than genuine short-seller distress.
- Combining short interest data with fundamental analysis provides a clearer picture and reduces the risk of acting on misleading short squeeze signals.
Table of Contents
- How days to cover is calculated and displayed
- Where the data comes from and how often it's updated
- How to interpret days to cover without overreacting
- Where this metric breaks down and what regulation has to do with it
- Putting days to cover to work inside Oracle Investments
- Why days to cover is a signal, not a verdict
- Track short interest alongside real fundamentals with Oracle
- FAQ
- Sources
How days to cover is calculated and displayed
The formula is straightforward: days to cover = current short interest ÷ average daily share volume. Short interest is the total number of shares sold short and not yet closed out, and the denominator is typically a 30-trading-day average volume, a convention Investopedia describes as the common practice among analysts. The look-back window matters because a stock that just had an unusually heavy trading day will show a temporarily lower days-to-cover figure, even though nothing about the short position actually changed.

Say a stock has 4 million shares sold short and its 30-day average volume is 2 million shares. Days to cover would be 4,000,000 ÷ 2,000,000, or 2.00: short sellers would need about two average trading days to unwind their entire position.
Published data sources follow specific display conventions rather than showing raw division results:
- Values at or below 1.00 are displayed as 1.00, never as a smaller decimal.
- When average daily volume is zero, the field shows N/A instead of an error or a blank.
- Figures are drawn from a fixed snapshot date, rather than a rolling real-time calculation.
These display rules exist because a near-zero denominator can produce a wildly misleading ratio, and capping or flagging it keeps the output usable.
Where the data comes from and how often it's updated
Short interest numbers don't update continuously. Under FINRA Rule 4560, member firms report their short positions twice a month, and FINRA aggregates and publishes the results on a set settlement-based schedule. That cadence, confirmed in FINRA Regulatory Notice 21-19, means every days-to-cover figure you see is already somewhat dated by the time it reaches a screener or app.
A few mechanics shape how that data reaches you:
- Exchanges handle processing and publication for listed securities, while FINRA separately compiles aggregated files for OTC names.
- Reporting firms file by a set deadline tied to the settlement date, then FINRA releases the compiled figures several days later.
- Short sale volume files, which track daily shorting activity, are a different dataset from the periodic short interest snapshot and shouldn't be confused with it.
Because of that lag, treat any days-to-cover reading as a recent estimate rather than a live number. If a stock has had a major news event or a volume surge since the last reporting date, assume the published ratio no longer reflects the current situation, and weight more recent volume and price action more heavily in your read.
How to interpret days to cover without overreacting
There's no universal cutoff where a stock suddenly becomes "squeeze territory." A days-to-cover reading that would be unremarkable for a heavily traded large-cap could be a serious liquidity warning for a thinly traded small-cap, so Corporate Finance Institute frames the ratio as an indicator of sentiment and potential squeeze pressure rather than a fixed threshold. A rising multi-day reading alongside other bearish positioning deserves more attention than a static number held flat for months.
Days to cover means more when you combine it with:
- Float percentage, since a high short interest against a small float concentrates the pressure if buying accelerates.
- Recent volume change, because a sudden spike can shrink the ratio even while short interest itself stays elevated.
- Upcoming catalysts like earnings or regulatory news, which can trigger exactly the buying pressure that forces shorts to cover.
Pro Tip: Check the reporting date on any short interest figure before acting on it; a number from two settlement cycles ago may already be stale.
When days to cover looks unusually high, work through this before reacting:
- Confirm the reporting date and cross-check it against any recent news or volume spikes.
- Look up the float percentage to see how concentrated the short position really is.
- Review recent price action for signs sellers or buyers are already moving.
- Check company fundamentals rather than trading solely on sentiment data.
- Decide whether the setup fits your own risk tolerance, not just the headline ratio.
Where this metric breaks down and what regulation has to do with it
Days to cover is a snapshot, not a live feed, and that snapshot nature causes most of its practical problems. FINRA's guidance draws a clear line between short interest data and daily short-sale volume files, warning that conflating the two leads to faulty squeeze predictions.
Edge cases distort the ratio further:
- OTC securities can show extreme percentage swings between reporting periods when average volume is very low, sometimes producing placeholder-like outputs rather than meaningful figures.
- Thinly traded stocks of any kind can generate inflated ratios from a tiny denominator, not genuine short-seller distress.
- Synthetic or indirect short exposure through derivatives doesn't always show up in the reported short interest figure at all.
Regulatory mechanics add another layer. SEC Regulation SHO and its Rule 203(b)(3) buy-in requirements force action on fails to deliver that stay open too long, which can change shorting behavior and indirectly shift days-to-cover figures in affected securities. None of this makes the ratio useless, but it does mean a single extreme reading deserves scrutiny before it drives a decision.
Putting days to cover to work inside Oracle Investments
Short interest context pairs naturally with the fundamentals we score inside the app. Our short interest explainer walks through the underlying input, and our interest coverage ratio guide covers a related balance-sheet metric worth checking alongside it.
A practical workflow looks like this:
- Verify the days-to-cover figure and its reporting date before anything else.
- Check recent volume and float percentage for context on concentration.
- Confirm fundamentals using our profitability and valuation scores rather than trading on sentiment alone.
- Decide whether the stock belongs on your watchlist, gets trimmed, or warrants a closer look using our stock comparison checklist.
Subscribers can set alerts on watchlisted names and run instant side-by-side comparisons once a short-interest signal shows up.
Why days to cover is a signal, not a verdict
Days to cover tells you about positioning and liquidity, not about whether a business is actually worth owning. I'd treat it as an overlay: useful for flagging where sentiment is stretched, useless for deciding whether a company deserves your capital. Check the fundamentals first using our scoring inputs, then track how the ratio moves across reporting periods rather than reacting to one reading in isolation.
— Matt
Track short interest alongside real fundamentals with Oracle
Spotting an elevated days-to-cover reading is only half the job. The other half is confirming whether the underlying business actually holds up, and that's where our scoring tools come in.
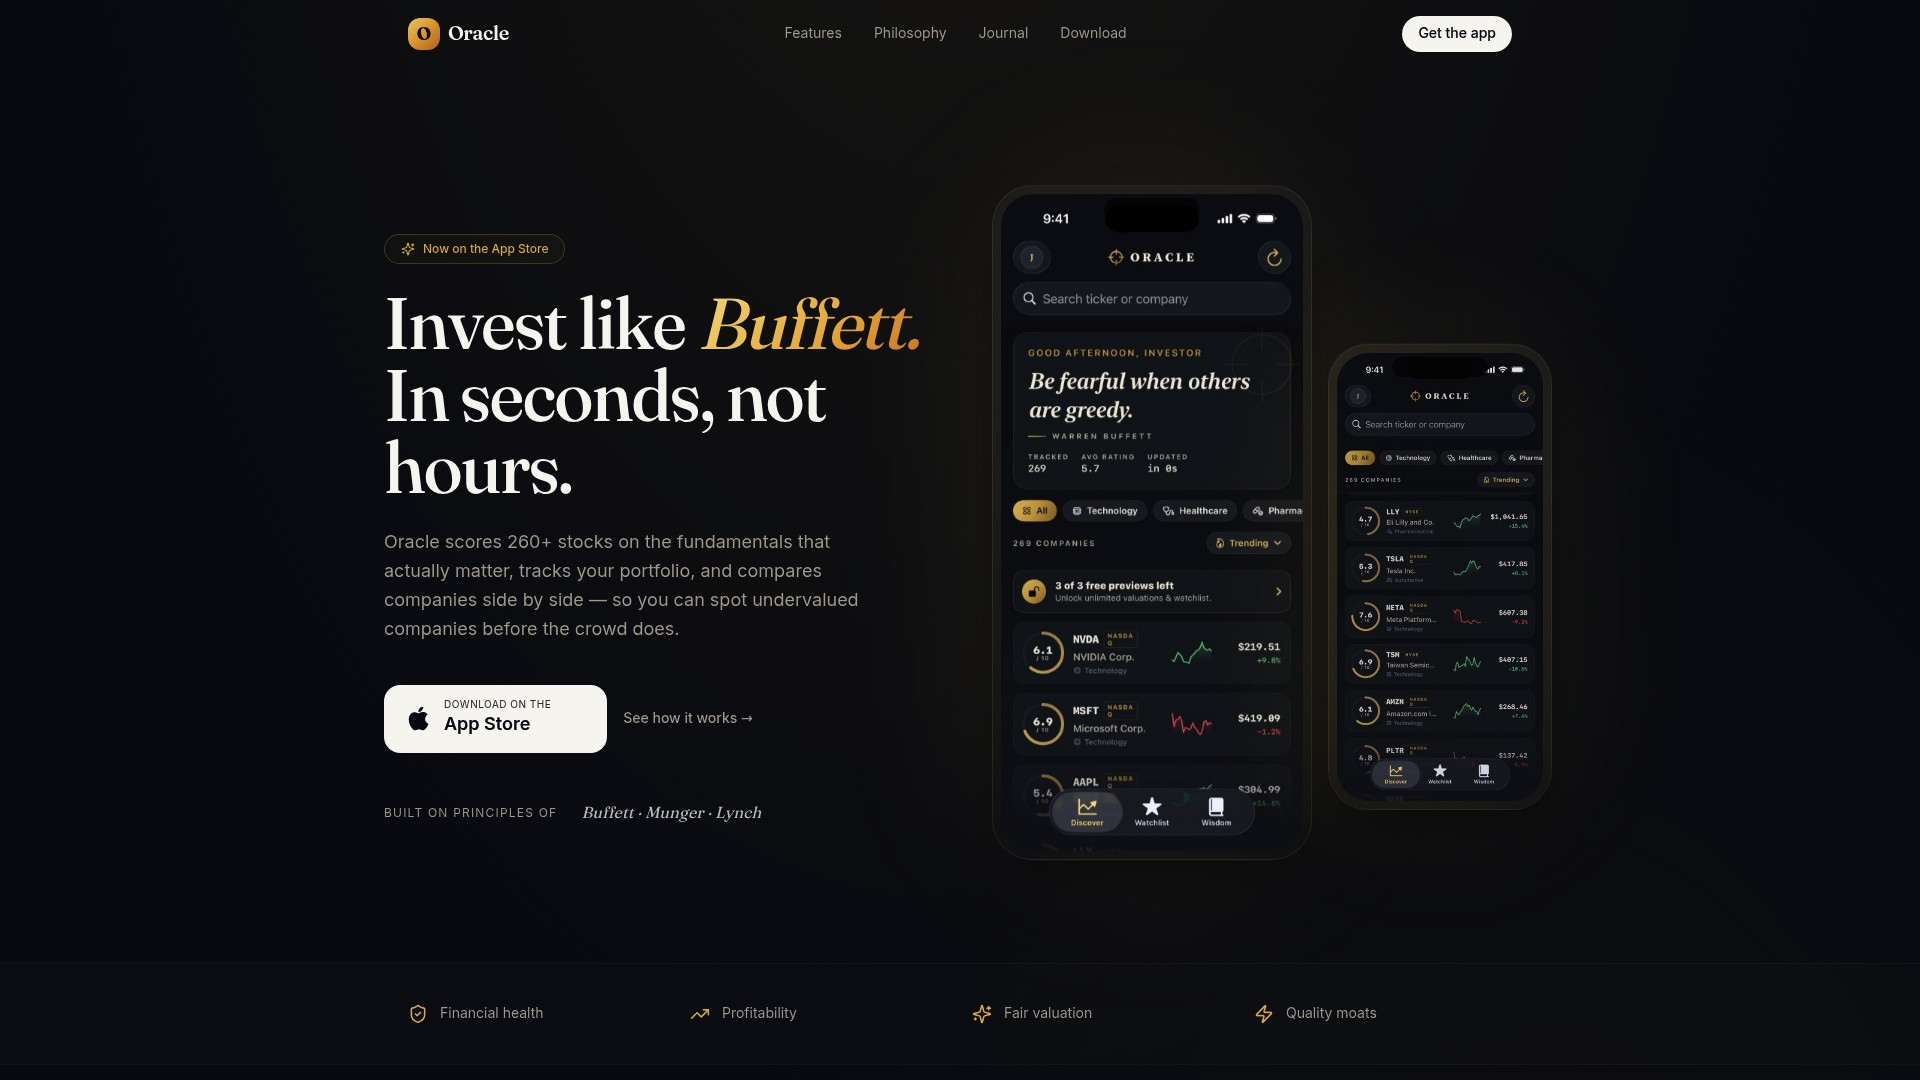
With a subscription, you get:
- Real-time tracking across the stocks you're watching, including short-interest context.
- Instant side-by-side comparisons so you can weigh a squeeze candidate against alternatives.
- Transparent scoring built from reported fundamentals, so you can see what's driving a rating.
Set alerts on the names you're watching and check their fundamentals before you act on a short-interest spike. Start with Premium Annual today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What does a days to cover of 5 actually mean?
It means short sellers would need about five average trading days to buy back their entire position at current volume levels, based on the formula of short interest divided by average daily volume. A reading that high relative to a stock's normal range can signal elevated short-squeeze risk, though it should be weighed against float and recent catalysts.
How often is short interest data updated?
FINRA requires member firms to report short interest twice a month, and the aggregated figures are published on a settlement-based schedule afterward. That means any days-to-cover number you see reflects a recent, not live, snapshot.
Why does days to cover sometimes show as N/A or a flat 1.00?
These are display conventions, not errors: FINRA's data file rules show N/A when average daily volume is zero and cap any value at or below 1.00 to avoid a misleadingly small decimal. Always check the underlying short interest and volume figures if a displayed value looks unusual.
Does a high days to cover guarantee a short squeeze?
No single metric guarantees a squeeze. A high reading combined with a small float, rising volume, and an upcoming catalyst raises the odds, but educational sources frame it as a sentiment indicator rather than a predictive trigger.
Can I see days to cover for stocks I'm tracking in Oracle Investments?
Our app surfaces short interest context alongside the fundamental scores we calculate for each stock, and Premium Annual subscribers can set alerts on the names they're watching. Pricing details for Premium Annual are available on our subscription page.
Sources
- FINRA — Equity short interest
- Investopedia — Days to cover
- SEC — Short sales rule materials (Reg SHO)