An unrealized gain is a profit on paper: you own an investment that is worth more than you paid, but you haven't sold it. A realized gain is that same profit locked in by a sale. The difference matters mostly for taxes and cash: a sale can create a tax bill, while a paper gain generally does not.
Below, you'll see how each one works, how to calculate them with a real example, how U.S. tax rules treat them, and how to decide what to do with a position that has grown.
TL;DR
- Unrealized gain: an investment you still own is worth more than your cost basis. It moves your portfolio value, not your tax return.
- Realized gain: you sold for more than your adjusted basis. The profit is real cash, and it is generally reportable to the IRS.
- Tax rates in the U.S.: short-term gains (held one year or less) are taxed as ordinary income; most long-term gains are taxed at 0%, 15%, or 20%.
- Exceptions exist: mutual funds and ETFs can pass taxable gains to you even if you never sold your shares.
- Losses count too: realized losses can offset gains, but the wash sale rule can block the deduction.
Table of Contents
- The core difference in plain terms
- How to calculate an unrealized gain or loss
- When an unrealized gain becomes realized
- Do you pay taxes on realized gains?
- Are unrealized gains taxable?
- Are unrealized gains good or bad?
- Realized losses and the wash sale rule
- Realized vs. recognized: a small distinction
- How to decide what to do with an unrealized gain
- Perspective
- See your gains next to the fundamentals
- Frequently asked questions
- Sources
The core difference in plain terms
Think of a stock you bought at $50 that now trades at $70. As long as you hold it, the $20 per share is unrealized. An unrealized gain, or paper profit, is an increase in an asset's market value over its original cost on an investment you still hold. The number changes every trading day. It can shrink, vanish, or turn into a loss before you ever touch it.
The moment you sell, the gain becomes realized. A realized gain occurs when you sell an asset for more than its purchase price, and that creates tax consequences unless the account is tax-deferred, such as a traditional IRA or 401(k).
Here is the side-by-side view:
| Unrealized gain | Realized gain | |
|---|---|---|
| Do you still own the asset? | Yes | No, it was sold |
| Is the profit certain? | No, it changes with the market | Yes, it is locked in |
| Cash in your hands? | No | Yes |
| Taxable event in a regular brokerage account? | Generally no | Generally yes |
| Shows up on Form 8949 / Schedule D? | No | Yes, for most sales |
| Can it disappear? | Yes | No (the tax consequence stays) |
The same logic applies to losses. A drop in price on a stock you hold is an unrealized loss. It becomes a realized loss only when you sell.
How to calculate an unrealized gain or loss
The formula is simple:
Unrealized gain or loss = current market value − cost basis
The part people get wrong is the cost basis. Cost basis is the original purchase price, including costs such as commissions and other fees. If you reinvested dividends, each reinvestment adds shares at a new price and raises your basis too.
A worked example
Say you buy 100 shares of a company at $50 each and pay a $5 commission.
- Cost basis: 100 × $50 + $5 = $5,005
- Months later the stock trades at $70, so the position is worth $7,000
- Unrealized gain: $7,000 − $5,005 = $1,995
If the stock later falls to $45, the position is worth $4,500 and you have an unrealized loss of $505. Nothing has been paid or deducted. Both numbers are just a snapshot.
Now suppose you sell all 100 shares at $70 and pay another $5 commission. Your proceeds are $6,995, and your realized gain is $6,995 − $5,005 = $1,990. That is the figure that goes on your tax forms.
Why basis accuracy matters
Tracking basis correctly matters because a lower reported basis can lead to overpaying taxes. Brokerages usually report basis for you on Form 1099-B, but if you transferred shares between firms, received them as a gift, or inherited them, check that the number is right before you file.
When an unrealized gain becomes realized
In most cases, an unrealized gain becomes realized only when the asset is sold. Holding, watching, and even borrowing against a position do not realize it.
A few practical points:
- Partial sales: If you sell 40 of your 100 shares, only the gain on those 40 is realized. The other 60 remain unrealized.
- Selling at a loss: A realized loss occurs when you sell for less than your adjusted cost basis. A capital loss may offset capital gains, subject to deduction limits.
- Tax-deferred accounts: Inside a traditional IRA or 401(k), buying and selling does not create a yearly tax bill on each trade. Taxes come when you withdraw.
Do you pay taxes on realized gains?
Yes, in a regular taxable account you generally do. The rate depends on how long you held the asset and your taxable income. Per the IRS, net capital gains may be taxed at different rates based on holding period and taxable income, and most sales are reported on Form 8949 and summarized on Schedule D.
Short-term vs. long-term
Short-term gains on assets held one year or less are taxed as ordinary income, while most net long-term gains are taxed at 0%, 15%, or 20%, depending on taxable income.
Here is what that holding period can mean on a $2,000 gain, purely as an illustration:
| Holding period | Rate example | Tax on $2,000 gain |
|---|---|---|
| One year or less | 24% ordinary bracket | $480 |
| More than one year | 15% long-term rate | $300 |
| More than one year | 0% long-term rate | $0 |
The 24% and 15% figures are examples only. Your own rate depends on your income and filing status.
What the 20% rule means
People often ask about "the 20% rule." It is the top long-term rate: 20% applies to net capital gains to the extent taxable income exceeds the thresholds set for the 15% rate. The 0% rate is also real. For tax year 2025, the 0% long-term rate applied to single filers with taxable income up to $48,350 and head-of-household filers up to $64,750. These thresholds are adjusted annually, so check the IRS page for the year you are filing.

Higher earners may owe more on top. A 3.8% net investment income tax applies to individuals with net investment income and income above set thresholds. State taxes can add to the total as well.
Are unrealized gains taxable?
For stocks you hold directly, no. You don't report an unrealized gain on your return, and it creates no tax. That is why selling is the decision that triggers the tax, and why timing it matters.
There is one common exception that catches investors off guard: funds. Mutual fund and ETF investors may owe taxes on capital gains distributions realized inside the fund, even if they haven't sold their own shares. The fund manager sold holdings at a profit, and the gain flows through to you. Before buying a fund late in the year in a taxable account, check whether a distribution is coming. Holding funds in an IRA or 401(k) sidesteps this.
Are unrealized gains good or bad?
Neither. An unrealized gain is information. It tells you the market currently values your holding above what you paid. What you do with it depends on your reasons for owning the stock.
Investors may hold unrealized gains if they believe the investment has room for future gains, and holding longer may lower the tax burden. That reasoning is sound when the business still looks healthy. It is weak when the only reason to hold is that you don't want to pay tax.
Two mistakes show up again and again:
- Treating paper gains as spendable money. A gain that is 30% on Monday can be 10% by Friday. Until you sell, the profit isn't yours to count on.
- Letting the tax tail wag the dog. A position that has become a large share of your portfolio may deserve trimming even if it creates a tax bill. Paying 15% on a gain is better than watching it round-trip to zero.
The second mistake is partly psychological. People mentally separate "house money" from "my money," which we cover in how mental accounting hurts your portfolio.
Realized losses and the wash sale rule
A realized loss isn't just a disappointment. It has a use. A realized loss can offset other capital gains to reduce your overall tax burden. If losses exceed gains in a year, the IRS limits how much you can deduct against other income, which is $3,000 a year for most filers ($1,500 if married filing separately), with the excess carried forward to later years, per IRS Topic 409.
There is a trap, though. The wash sale rule bars counting a capital loss when you buy the same or a substantially similar security within 30 days before or after selling at a loss. Sell on December 10, rebuy on December 20, and the loss is generally disallowed for now.
Two guides on our blog walk through the details: how the 30-day wash sale window works and tax loss harvesting for U.S. investors.

Realized vs. recognized: a small distinction
You may also see the term "recognized gain." A gain is realized when a transaction happens, and recognized when it counts for tax purposes. For ordinary stock sales they are the same thing at the same time. They can differ in special cases, such as certain like-kind exchanges of real property, where a gain is realized but its recognition is deferred. If your situation involves property, a business sale, or an inheritance, ask a CPA or enrolled agent rather than relying on a general rule.
How to decide what to do with an unrealized gain
The tax question comes second. The first question is whether you would buy the stock today at today's price. If yes, a paper gain is no reason to sell. If no, the gain is no reason to stay.
Use this checklist:
- Has the thesis changed? If the reasons you bought are weaker (falling margins, rising debt, a shrinking moat), selling may be right regardless of tax.
- Is the valuation stretched? A stock that has doubled may now cost far more than the business earns. Our guide on when to sell stocks goes through the signals.
- How long have you held it? If you are close to the one-year mark, waiting a few weeks can move a short-term gain into the long-term bucket. That can cut the tax rate meaningfully.
- How concentrated are you? If one position drives your portfolio, trimming can reduce risk. See our overview of downside protection strategies.
- Which account holds it? Selling inside an IRA has no immediate tax. Selling in a taxable account does.
- Can losses offset it? Other realized losses in the same year can shrink the taxable gain.
- What does turnover cost you? Frequent selling turns many small gains into taxable events. Our portfolio turnover checklist shows how those costs add up.
For long-term investors, the usual conclusion is to let good businesses compound and sell for a reason, not a reaction. We explain that mindset in long-term investing strategy for beginners and in time in the market.
If you are retired
Retirees often hold large unrealized gains from decades of investing and draw income from a mix of accounts. Which account you sell from, and in what order, can change your tax bill, and selling in a down market can hurt more than usual. Two reads help here: an income-first retiree investing strategy and sequence of returns risk. For your exact numbers, a CPA or fee-only financial planner can run the projection.
Perspective
Most investors learn the realized vs. unrealized distinction from a tax form, after the fact. We think it is more useful as a decision tool before you sell.
A paper gain tells you what the market thinks today. It doesn't tell you whether the business is worth owning. That is why we built Oracle Investments around company fundamentals: profitability, valuation, and financial health, scored by rules and with every input shown. When a position is up 80%, you don't need a hunch about the next headline. You need to know whether the business still earns its price.
Our scores are rule-based and grounded in reported fundamentals, not AI guesses, so you can see why a stock scores as it does and compare it side by side with others. We also bring in the thinking of investors like Warren Buffett, Charlie Munger, and Peter Lynch, who treated selling as a judgment about value, not a reaction to a gain.
Realize a gain because the facts changed or you need the money. Don't realize it, or avoid realizing it, just because a number on the screen is green.
Matt
See your gains next to the fundamentals
Tracking unrealized gains is only half the picture. The other half is whether each holding is still attractive at today's price. With Oracle Investments, you can follow your portfolio in real time and see profitability, valuation, and financial health scores for over 260 stocks, side by side, with no spreadsheets to set up. The paid subscription, Premium Annual, is available through the Apple App Store.
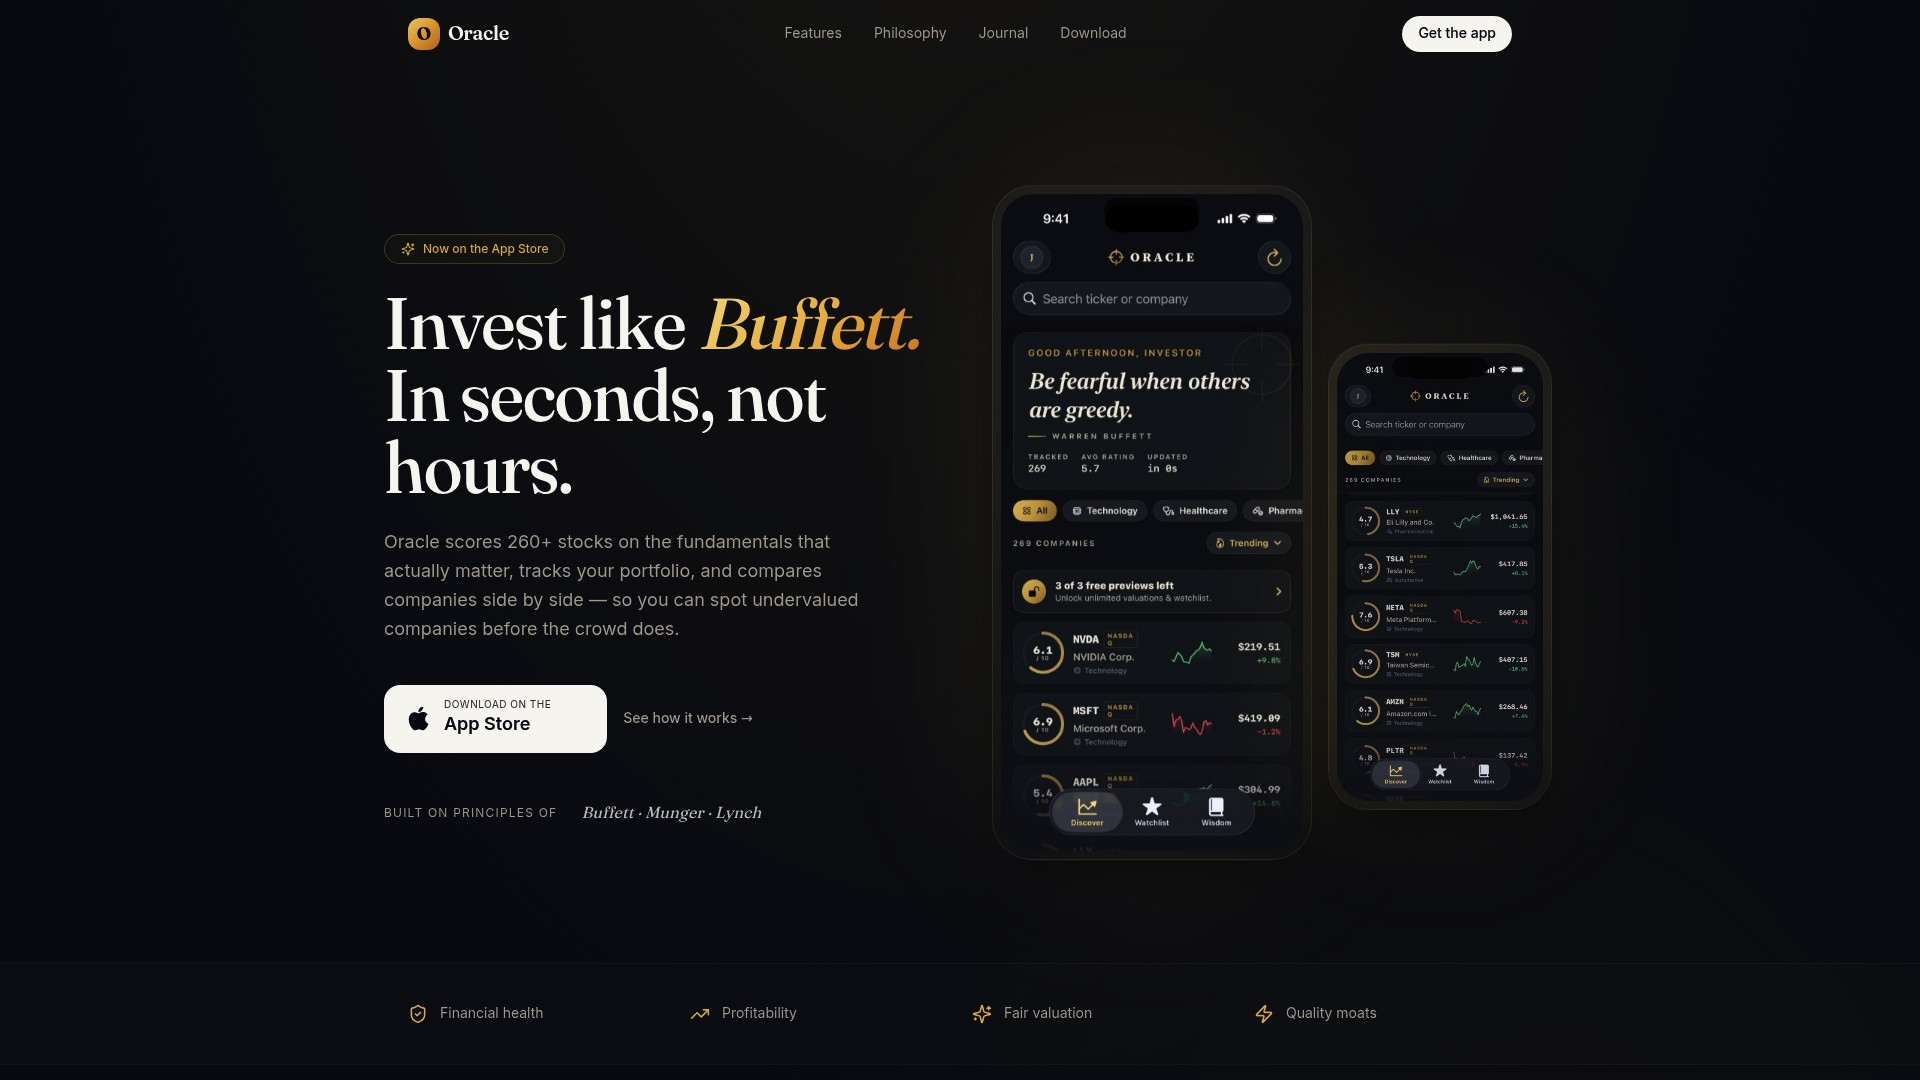
The next time you look at a big green number, check the fundamentals before you decide to sell or hold. You can start on the Oracle Investments page.
Frequently asked questions
What is the difference between realized and unrealized capital gains?
An unrealized gain is a paper profit on an asset you still own. A realized gain happens when you sell it for more than your cost basis. The sale is what can create a tax bill, as Investopedia explains.
Do you report unrealized gains to the IRS?
For stocks you hold directly, no. Only sales are reported, generally on Form 8949 and Schedule D. The exception is fund distributions: if a mutual fund or ETF passes capital gains to you, those are taxable even if you didn't sell shares.
Do you pay taxes on realized gains?
In a taxable account, usually yes. Short-term gains are taxed as ordinary income, and most long-term gains at 0%, 15%, or 20%, based on taxable income. Gains inside a traditional IRA or 401(k) aren't taxed when you sell within the account.
Can I use losses to offset my gains?
Yes. Realized losses first offset realized gains, and then up to $3,000 a year of other income for most filers, with the rest carried forward. Avoid buying the same or a substantially similar security within 30 days before or after the sale, or the wash sale rule can disallow the loss.
Is it better to hold or sell a stock with an unrealized gain?
It depends on the business, not the gain. If the company's fundamentals are still strong and the price is reasonable, holding can make sense, and holding longer than a year can lower your rate. If the thesis has broken or the position is too large, selling can be the right call even with a tax bill.
Sources
- Realized vs. Unrealized Gains: Understanding and Calculating (Investopedia)
- What Are Unrealized Gains and Losses? (Investopedia)
- Calculating Stock Gains and Losses: A Step-by-Step Guide (Investopedia)
- Topic no. 409, Capital gains and losses (IRS)
- Topic no. 559, Net investment income tax (IRS)
- Capital Gains Explained (FINRA)
- Capital Gains Tax: Rates, Rules, and Strategies (Vanguard)