Mr. Market is Benjamin Graham's picture of the stock market as a moody business partner. Every day he offers to buy your share of a company or sell you more of it, at a price set by his mood. You are free to say no. The lesson is that the price on your screen is an offer, not a verdict on what the business is worth.
This guide explains where the analogy comes from, walks through a numerical example, shows how to apply it before you trade, and covers what it does not promise.
TL;DR
- Mr. Market is Graham's allegory for a market that swings between pessimism and euphoria. He quotes a price daily, and you decide whether to act.
- Price and value are different things. Estimate the value of the business first, then compare it with the quote.
- Sell, buy, or do nothing are all valid answers. Most days, doing nothing is the right one.
- The analogy protects you from reacting to mood. It does not tell you when the market will turn or guarantee a return.
- A one-sentence written reason before each trade helps you tell a business decision from a mood-driven one.
Table of Contents
- Where the Mr. Market analogy comes from
- What Mr. Market actually represents
- Why his mood swings create opportunity
- A worked example with real numbers
- How to use the analogy before you trade
- What Graham wanted you to take from it
- Common mistakes when applying the analogy
- What the analogy does not tell you
- Perspective
- Put the analogy to work with Oracle
- FAQ
- Sources
Where the Mr. Market analogy comes from
Benjamin Graham, often called the father of value investing, introduced Mr. Market in his 1949 book The Intelligent Investor, according to the CFA Institute's Enterprising Investor blog. The parable appears in Chapter 8 of later editions, while the margin of safety discussion sits in Chapter 20, as Buffettpedia's chapter notes point out. The original 1949 edition numbered its chapters differently, so page references vary by edition.
Graham asks you to imagine that you own a small stake in a private business. In the version Oaktree Capital recounts, the stake cost $1,000, and a partner named Mr. Market turns up every day. He names a price at which he will either buy your interest or sell you an additional one.
The twist is his temperament. His estimate of the business swings from deeply pessimistic to wildly optimistic, even when the business itself has barely changed. Some days his quote is plausible and backed by real developments. Other days, in Graham's words as quoted by Oaktree, it looks "a little short of silly."
What Mr. Market actually represents
Mr. Market is not a person or a forecast. He is the sum of everyone trading a stock today. Investopedia describes him as a hypothetical investor driven by panic, euphoria and apathy, who reacts to his mood instead of analyzing fundamentals.
Two features make the character useful:
- He never stops quoting. You get a price every trading day whether or not anything has happened to the business.
- He does not mind being ignored. The offer carries no obligation. You can decline it, and tomorrow he will be back with another.
The CFA Institute article adds a nuance: Mr. Market has a rational side that works from hard data and an emotional side that gets excited, panicky or depressed. When the emotional side takes over, prices drift away from fair value. That drift is the thing a patient investor is trying to notice.
Why his mood swings create opportunity
Warren Buffett, Graham's most famous student, put the point bluntly. As Investopedia's Buffett guide summarizes, when Mr. Market is euphoric he will overpay for your shares, and when he is depressed he will sell quality businesses at bargain prices. The more extreme his swings, the more pricing errors there are for a disciplined investor to use.
The flip side is where most people get hurt. Graham warned that an investor who lets himself be stampeded by unjustified declines is turning his basic advantage into a disadvantage, a line quoted on Glen Bradford's Graham quotes page. The advantage is that you own a business with its own value. The disadvantage is letting a stranger's mood decide how you feel about it.
Markets also do not swing randomly around a calm center. Oaktree's memo compares investor psychology to a pendulum that spends far more time near euphoria or depression than at a happy medium. That is why the analogy is worth keeping in your head during both booms and sell-offs, and why how emotions move prices away from fair value is worth understanding in its own right.
A worked example with real numbers
Take Graham's $1,000 stake and say your own research says it is worth about $1,000. Here is how three different days could look, following the example Shortform walks through:
| Mr. Market's mood | His offer | What the business is worth to you | Rational response |
|---|---|---|---|
| Depressed | Buys your stake for $600 | $1,000 | Decline. Do not sell for less than it is worth. |
| Neutral | Quotes roughly $1,000 | $1,000 | Ignore the offer and keep owning the business. |
| Euphoric | Sells you more at $1,500 or $2,000 | $1,000 | Decline to buy. Consider selling some of what you own. |
Notice what stays constant: your estimate of the business. Only the quote moves. If a 40% drop in the quote leaves your estimate unchanged, nothing has been lost except the mood of the person across the table.
The key sentence in the table is the "worth to you" column. Without it, you have nothing to compare the offer against, and the analogy collapses into guessing. Pomegra's explanation of the allegory makes the same point: a 10% decline feels threatening without the framework, but with it you see a lower price for the same business, which you can ignore or use as a chance to buy more.

How to use the analogy before you trade
The analogy is only as good as the value estimate behind it. Here is a routine individual investors can follow.
Step 1: Estimate what the business is worth
Graham told the true investor to form his own view of value from the company's reports on its operations and financial position, instead of from Mr. Market's daily message, as quoted in Oaktree's memo. StockEducation lists book value, earnings power, discounted cash flow and qualitative adjustments as ingredients. Our guide to intrinsic value calculation shows how to turn those inputs into a number. If you want a fast first filter, the Graham number screen takes about five minutes.
Step 2: Demand a gap, not a coincidence
Price below value is not enough, because your estimate can be wrong. Graham's margin of safety is the difference between a security's quoted price and its intrinsic value, serving as protection against miscalculation and misfortune, according to Greenleaf Trust. StockEducation reports that Graham saw buying opportunities perhaps 25 to 40 percent below intrinsic value and selling opportunities perhaps 25 to 50 percent above. Treat those as a guide to scale, not a rule. For the full treatment, read what a margin of safety is.
Step 3: Name the reason in one sentence
The Financial Express offers a practical test. If you are selling because something has changed your view of the underlying business, that is a value decision. If you are selling because the price fell and the chart looks ugly, you are acting on Mr. Market's mood. Writing the reason in a single sentence before you place the trade is one of the few reliable ways to tell them apart.
Try it on yourself. "Their largest customer left and margins are shrinking" is a business reason. "It is down 15% this month and I am nervous" is a mood.
Step 4: Choose among three actions
As Forbes contributor Robert Laura describes it, you can sell, buy or do nothing. A price well above worth is a time to sell. A price far below is a time to buy. A price that is neither extreme gives you permission to do nothing, and that is the most common outcome.

What Graham wanted you to take from it
The point is not to ignore prices. The AAII's summary of Graham's approach says he urged investors to ignore Mr. Market's offers most of the time and act when his numbers depart substantially from fundamental valuations.
Graham put it directly: price fluctuations have one significant meaning for the true investor, which is the chance to buy wisely when prices fall sharply and sell wisely when they rise a great deal (Chapter 8, as quoted by Glen Bradford). Prices serve you. You do not serve them.
The Financial Express frames it as a distinction between price and value: the market is a place to transact, not a measuring device. It also separates volatility from risk. Volatility is the size and speed of price moves, while risk is the probability of permanent loss of capital. They are related, but they are not the same thing.
Common mistakes when applying the analogy
Skipping the value estimate. Calling a stock cheap because it fell is the opposite of the lesson. A falling price may be Mr. Market being right about a deteriorating business. Our piece on a tested undervalued stocks strategy explains why a low P/E alone is not a signal.
Confusing cheap with a bargain. Some businesses are cheap because they are in trouble. See how to find real bargains and avoid traps in deep value investing.
Treating every dip as a gift. The analogy asks you to act at extremes relative to your own estimate, not on every move. The most common beginner value investing mistakes include overreacting to short-term noise.
Checking prices constantly. Mr. Market is always talking. You do not need to listen every day.
What the analogy does not tell you
Mr. Market helps you decide how to respond to prices. It does not tell you when the pendulum will turn, and it does not guarantee a return. A stock can stay cheap for years, and your estimate of value can be wrong.
Timing is the usual trap. A Bernstein research paper on market timing, covering 1994 to 2018, concludes that most market timers end up with lower returns than long-term buy-and-hold investors. The advice from Highland Peak Wealth is similar: moving to cash can feel safe but often risks missing long-term goals.
The practical reading is that Mr. Market rewards a business view and a long horizon, not a prediction. Pair the analogy with a plan: our long-term investing strategy for beginners lays one out, and the case for time in the market shows why holding period matters.
A caution on a famous line: the saying that the market is a voting machine in the short run and a weighing machine in the long run is often credited to Graham, but the AAII notes nobody has located it in his published work. It does reflect how he and Buffett thought, so use it as a summary of the idea, not as a Graham quote.
Buffett's own 1987 shareholder letter, as Farnam Street reproduces, says success comes from sound business judgment plus the ability to insulate your behavior from the contagious emotions of the market, not from formulas or price signals.
Perspective
We built Oracle around one belief: most investors do not lose because they lack information, they lose because they react to Mr. Market instead of to the business.
That is why our scores are rule-based and drawn from reported company fundamentals, such as profitability, valuation and financial health. We avoid AI or model-driven guesswork, and the scoring inputs are shown, so you can see why a company scores the way it does. When a price drops, you can ask the Graham question: did the business change, or only the quote?
Scoring over 260 stocks side by side makes that question quick to answer. You can compare companies, spot ones that look undervalued on fundamentals, and keep the discipline of Graham, Munger, Buffett and Lynch without building a spreadsheet first.
Mr. Market will always be moody. Your process does not have to be.
Matt
Put the analogy to work with Oracle
The hardest part of the Mr. Market routine is having a value view ready when the quote turns dramatic. Oracle Investments scores over 260 stocks on profitability, valuation and financial health, lets you compare companies side by side, and tracks your portfolio in real time. It is designed so you can check the fundamentals behind a price move in seconds, without setup.
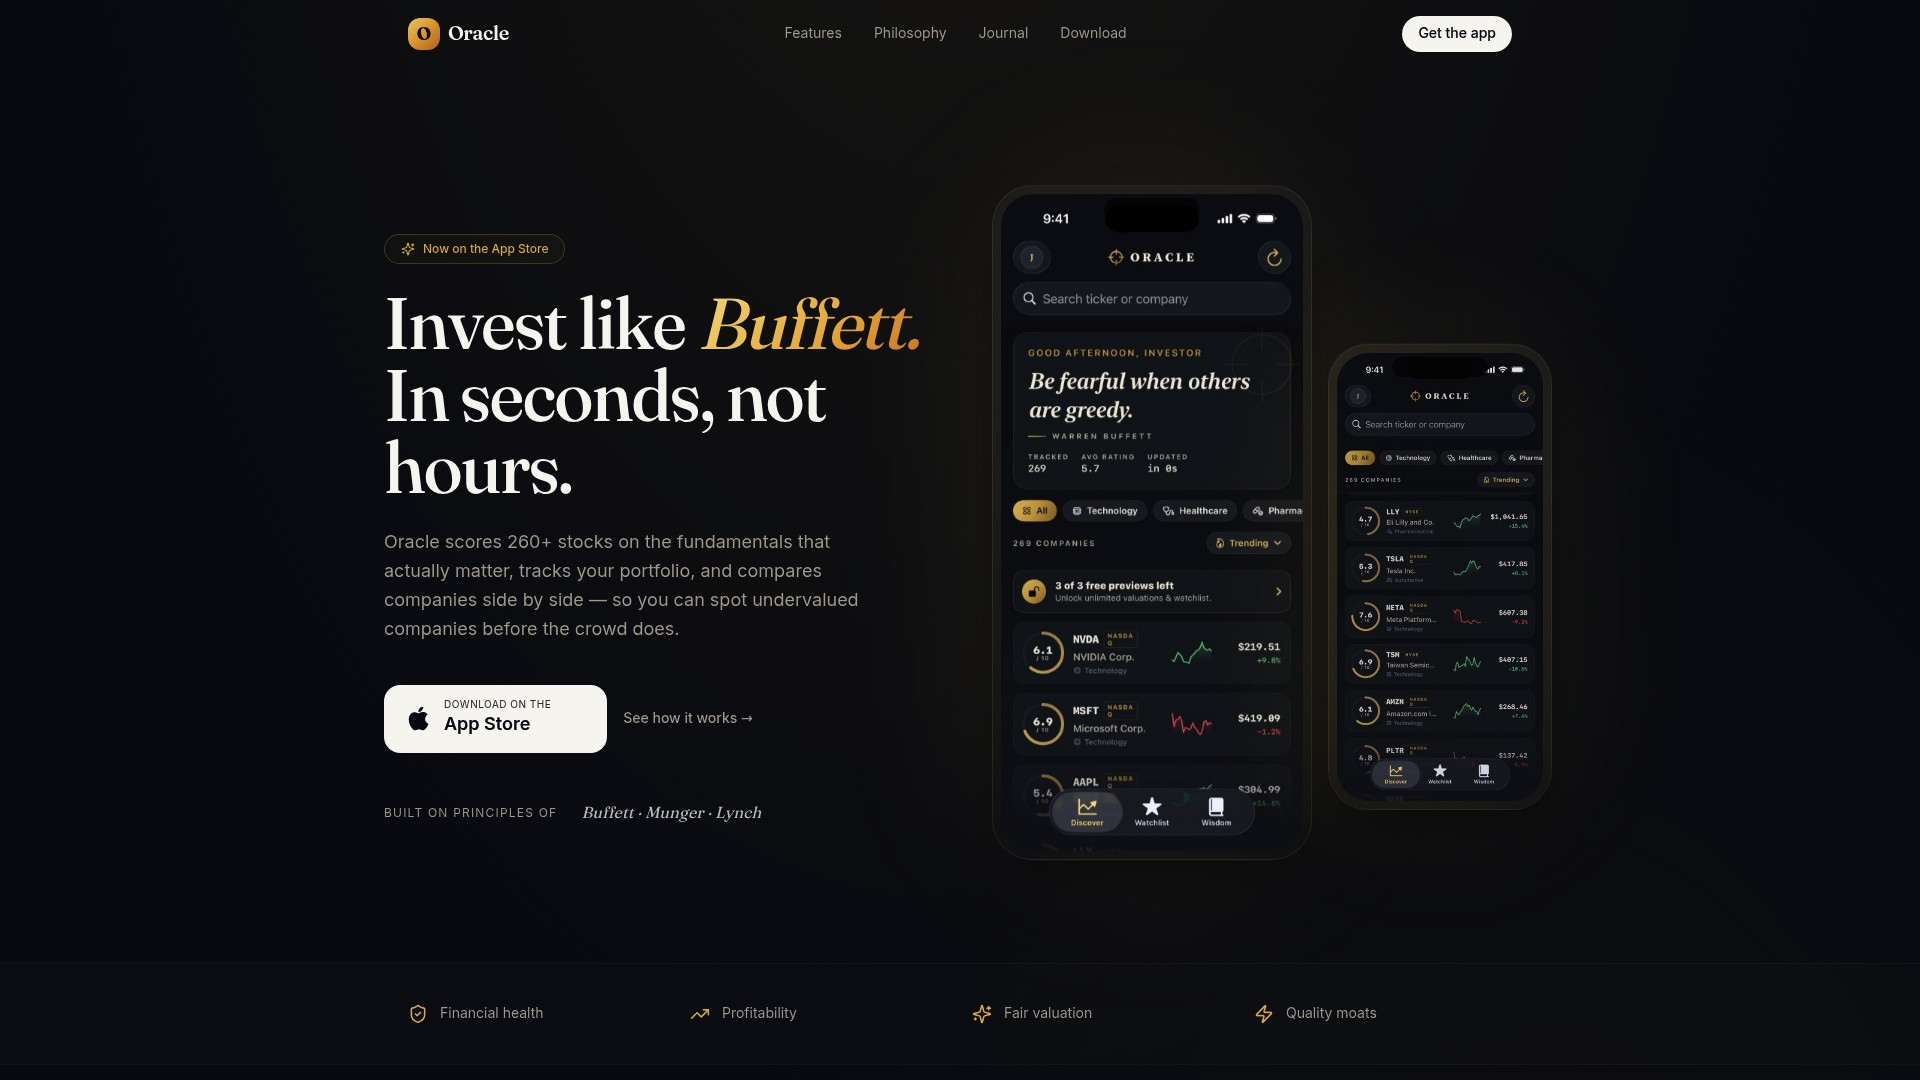
If you want that routine in your pocket, explore the Premium Annual plan in the app, or browse the free value investing lessons in The Oracle Journal.
FAQ
Who created the Mr. Market analogy?
Benjamin Graham, the economist and investor known as the father of value investing, created it. He introduced it in The Intelligent Investor in 1949. Warren Buffett later popularized it in his shareholder letters and talks.
Does Mr. Market mean I should buy every dip?
No. A lower price only matters if it is meaningfully below your own estimate of the business's value. If the decline reflects a real change in the company, the lower quote may be fair. Estimate value first, then compare.
What should I do when Mr. Market is euphoric?
Do not feel pressured to buy at his price. If the quote is far above what you think the business is worth, selling some or all of your stake is a valid response. If the price is merely high but not extreme, holding is also a reasonable choice.
Is the Mr. Market analogy a market timing strategy?
No. It does not predict when prices will turn. It gives you a way to respond to prices based on value, with patience. Research on market timing, including a Bernstein study of 1994 to 2018, found that timers usually trail buy-and-hold investors.
Sources
- Can Fundamental Momentum Diagnose Mr. Market? (CFA Institute)
- Benjamin Graham's The Intelligent Investor Chapter 8 (Buffettpedia)
- Mr. Market Miscalculates (Oaktree Capital)
- Mr. Market (Investopedia)
- Buffett's Guide to Controlling Your Investments (Investopedia)
- 50+ Benjamin Graham Quotes on Investing (Glen Bradford)
- Mr. Market: A Cautionary Tale of Investing Groupthink (Shortform)
- Mr. Market: Graham's Allegory (Pomegra)
- Mr. Market (StockEducation)
- The Intelligent Investor (Greenleaf Trust)
- Warren Buffett's 1987 lesson (The Financial Express)
- My Heartbreaking Stock Epiphany (Forbes)
- The Essence of the Benjamin Graham Approach (AAII)
- The Hidden Cost of Market Timing (Bernstein)
- Meet Mr. Market (Highland Peak Wealth)
- The Timeless Parable of Mr. Market (Farnam Street)