A capital allocation assessment is a structured review of where a company puts its money and whether that spending creates more value than it costs. The best-practice approach combines three moves: align every funding decision with strategy, prioritize projects where expected ROIC beats WACC, and enforce governance with staged, milestone-based funding. Start this week with a quick ROIC-versus-WACC scan of your current project list, then put a one-hour prioritization meeting on the calendar before the quarter closes.
TL;DR:
- Companies should focus on projects with expected ROIC consistently above WACC to ensure they create value with their capital.
- Final investment decisions must be owned by the CEO, supported by a small, disciplined committee that enforces clear milestones and kill criteria.
- Regularly tracking actual performance against projections and adjusting allocations based on validated data prevents repeating mistakes.
- Growth-stage firms must adapt their capital across flexible categories, and multi-segment companies benefit from allocating disproportionately to the most valuable segments.
- Conducting a quick ROIC versus WACC scan and establishing standardized evaluation tools enables a focused, two- to three-week review cycle.
Table of Contents
- What Is the Capital Allocation Framework Behind a Strong Assessment?
- How Do You Measure Whether Capital Allocation Is Working?
- What Are the Four Steps in a Capital Allocation Process?
- Who Should Actually Decide Where the Capital Goes?
- How Should Growth-Stage and Multi-Segment Companies Adapt This?
- What Does a Fast Capital Allocation Review Look Like?
- How Analytics Support a Disciplined Assessment
- Why Most Capital Allocation Mistakes Are Behavioral, Not Analytical
- Sources
- FAQ
What Is the Capital Allocation Framework Behind a Strong Assessment?
Every credible assessment rests on three pillars: strategic budgeting, project selection, and governance. Skip any one of them and the review turns into a spreadsheet exercise that nobody trusts.
Strategic capital budgeting starts with the plan, not the ledger. Budgets should flow from where the company wants competitive advantage in three to five years, not from last year's spending plus a growth percentage. If your strategy says "win in mid-market accounts," your capital budget needs a line item that says the same thing, in dollars. Firms that skip this step end up funding whatever business unit shouts loudest, which is a strategy in name only.
Project selection is where most assessments either earn their keep or fall apart. A workable filter runs each candidate project through four screens:
- Strategic fit: does this move the company toward a stated priority, or is it a side quest that happens to look profitable?
- Expected economics: what's the projected return relative to the cost of capital, and how sensitive is that number to your assumptions?
- Optionality: does funding this project now create the right to expand later at low additional cost, or is it a one-shot bet?
- Risk profile: what happens to the return if a key input, like customer acquisition cost or input pricing, moves against you?
Investment governance determines who actually gets to say yes. McKinsey's research on capital allocation governance makes a case that resonates with any manager who has watched a good project die in committee: the CEO should be the ultimate decision-maker, supported by a small strategic resource-allocation committee and a dedicated support team that keeps the analysis honest. Without that structure, decisions drift to whoever controls the budget process, and budget owners rarely want to defund their own turf.
The three pillars work together. Strategy sets direction, selection filters the candidates, and governance makes sure the right person signs off with the right information. Miss the governance piece and even a perfect selection process gets overridden by politics.
How Do You Measure Whether Capital Allocation Is Working?
The single most useful test in this entire process is comparing Return on Invested Capital (ROIC) to Weighted Average Cost of Capital (WACC). WallStreetPrep's framework on capital allocation puts it plainly: when ROIC sits above WACC, the company is creating economic value with every dollar deployed. When ROIC falls below WACC, the firm is destroying value even if net income looks fine on paper.
ROIC is calculated as net operating profit after tax divided by invested capital (debt plus equity, minus cash). WACC blends the cost of debt and the cost of equity, weighted by how much of each the company uses. A firm earning a ROIC above its WACC is generating positive economic spread on every dollar invested. That spread, not the raw ROIC number, is what tells you whether capital allocation is actually working. Readers who want the full mechanics behind the calculation can work through Oracleinvestments's guide to ROIC.
Where the numbers come from matters as much as the numbers themselves. The CFA Institute's guidance on capital investments flags three modeling errors that quietly wreck otherwise good analysis: double counting cash flows, ignoring how projects interact with each other, and failing to model reinvestment needs. Check for all three before trusting any project's numbers.
Beyond the ROIC-versus-WACC baseline, three tools round out the measurement toolbox:
- Net Present Value (NPV) discounts future cash flows to today's dollars, giving you a single number for whether a project adds value in absolute terms. Its weakness: NPV rewards scale, so a $50 million project with a modest NPV can outrank a $2 million project with a higher percentage return.
- Internal Rate of Return (IRR) tells you the percentage return a project generates, which is useful for comparing projects of different sizes. It gets unreliable when cash flows change sign more than once or when reinvestment assumptions don't match reality.
- Real-options thinking treats an investment as a right, not an obligation. Instead of approving the full budget upfront, you fund a pilot, learn from it, and decide later whether to expand, pivot, or walk away. This matters most for high-uncertainty bets like new product launches, where a decision tree beats a single NPV number every time.
Once money is deployed, the assessment doesn't stop. Track Economic Value Added (EVA), compare actual NPV realization against the original projection, and hold projects accountable to the milestones set at approval. A capital allocation framework that only evaluates projects before funding and never checks back afterward will keep repeating the same mistakes.
What Are the Four Steps in a Capital Allocation Process?
CFI's research on the capital allocation process breaks the workflow into four steps, and running an assessment means checking whether your organization actually executes each one, not just the ones that are easy.
- Idea generation. Business units, product teams, and finance should all be able to submit capital requests, but every submission needs a one-page business case: expected ROIC, capital required, and the strategic priority it serves. Finance owns the model template; the requesting team owns the assumptions.
- Analysis. This is where risks and opportunities get stress-tested. Build a base case, an upside case, and a downside case, then run a sensitivity table showing how the return changes if revenue comes in 15% light or costs run 10% high. MIT Sloan's research on capital allocation points to dynamic, checkpoint-based evaluation as the difference between organizations that make good bets and those that fund whatever got approved first.
- Planning and execution. Structure funding in tranches, not one lump sum. Release the next tranche only when the project hits a pre-agreed milestone, whether that's a customer pilot, a regulatory approval, or a cost target. Define kill criteria in advance, in writing, so a struggling project can be stopped without it turning into a political fight.
- Monitoring. Track actual performance against the original decision memo on a fixed cadence, usually quarterly. Compare realized NPV to projected NPV and flag any project that's drifted more than 20% off plan for a formal review.
Pro Tip: Write the kill criteria into the approval memo itself, in the same paragraph as the funding amount. A kill criterion that lives in a separate risk document gets ignored the moment a project champion starts lobbying for more time.
The deliverables that make this repeatable are simple: a scenario model, a sensitivity table, and a one-page decision memo for every project above your materiality threshold. Skip the memo and you'll be relitigating the same decision six months later with no record of what was actually agreed.
Who Should Actually Decide Where the Capital Goes?
Governance failures, not bad math, are the most common reason capital allocation assessments go nowhere. The numbers can be right and the decision still gets made by the wrong person, at the wrong time, with the wrong incentives.
McKinsey's research on capital allocation governance argues the CEO needs to be the decision-maker-in-chief, not a rubber stamp at the end of a process run by finance or by business unit heads competing for budget. That doesn't mean the CEO builds the models. It means the CEO owns the final call on where scarce capital goes, backed by a strategic resource-allocation committee and a support team strong enough to produce comparable, unbiased analysis across every candidate project.
A few governance checks separate disciplined organizations from ones that just look disciplined on a slide:
- Keep the prioritization list to a manageable number of projects under active review, generally somewhere in the 20 to 50 range. Beyond that, ranking quality collapses and everything starts looking equally urgent.
- Rank projects transparently, on the same metrics, in the same document, visible to everyone in the room. Side conversations about "special circumstances" are where bad projects survive.
- Set a fixed meeting cadence for the committee, monthly or quarterly, rather than convening only when someone escalates.
- Decide upfront whether the committee votes or advises. A committee that "recommends" but has no teeth just adds a step without adding discipline.
- Mandate a post-mortem on every project above a set size, win or lose, and require it within 90 days of completion.
Pro Tip: Require every capital request above your materiality threshold to be compared against at least two other live candidates in the same document, not reviewed in isolation. Isolated approvals almost always favor safe, incremental spending over the bigger bet that actually moves the business.
How Should Growth-Stage and Multi-Segment Companies Adapt This?
A ten-person startup and a multi-division enterprise are solving different allocation problems, even though the underlying math is identical.
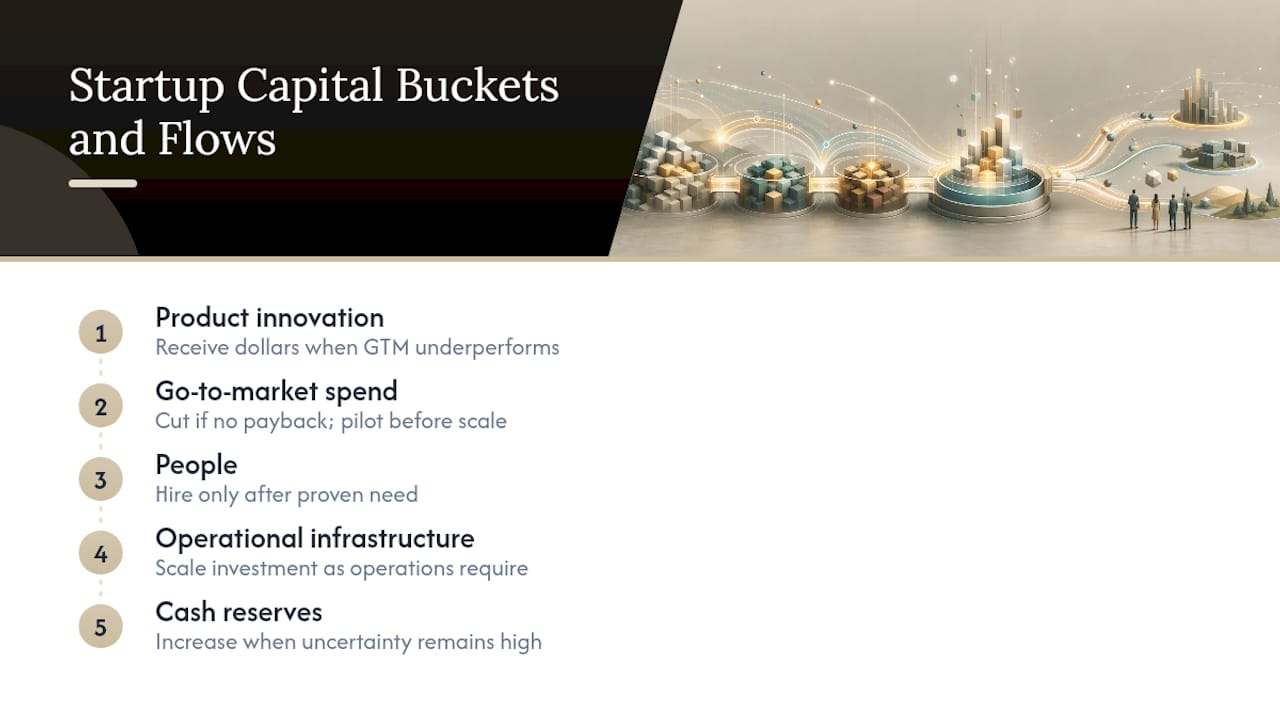
Growth-stage companies typically split capital across five buckets: product innovation, go-to-market spend, people, operational infrastructure, and cash reserves. The mistake most founders make is treating these as fixed percentages instead of variables that should shift as the business proves or disproves its assumptions. If go-to-market spend isn't producing payback within your target window, that's a signal to shift dollars toward product or reserves, not a reason to spend harder on the same channel.
For multi-segment companies, the core question is concentration versus diversification. BCG's analysis of capital allocation found that the strongest allocators show a wider spread in investment intensity across their business segments than average performers. In plain terms: they don't fund every division at roughly the same rate. They put a disproportionate share of capital behind the segment where a dollar produces the most value, and they reallocate regularly rather than defaulting to last year's split.
For high-uncertainty growth bets, sequencing matters more than sizing. Fund a small pilot, set a specific milestone that would justify the next round of investment, and resist the urge to commit the full budget before you've learned anything. This is real-options thinking applied at the growth-stage level, and it protects you from the single biggest failure mode in this category: full commitment to an idea before the market has told you whether it works.
What Does a Fast Capital Allocation Review Look Like?
You don't need a six-month consulting engagement to get a useful read on your current allocation. A focused review, run over two to three weeks, covers five steps:
- Collect the data. Pull invested capital, operating profit, and cost of capital by project or segment. Incomplete data here undermines everything downstream.
- Run the ROIC-versus-WACC scan. Rank every active project or segment by its economic spread, highest to lowest.
- Rank projects on a common template. Score strategic fit, expected economics, and risk on the same scale so comparisons are apples to apples.
- Convene the committee. Present the ranked list, not a narrative pitch for each project individually.
- Apply the tranche template. For anything moving forward, define the next milestone and the funding tied to it before the meeting ends.
The tool categories that make this repeatable are a standardized financial model template, a scenario pack for sensitivity testing, a milestone-gating template for tranche releases, and a portfolio dashboard that tracks realized versus projected returns. None of this requires exotic software, but it does require someone to own the templates so every project gets evaluated the same way. Readers building this out from scratch can find a broader survey of dashboard and modeling options in Oracleinvestments's roundup of portfolio analysis tools.
How Analytics Support a Disciplined Assessment
A capital allocation assessment lives or dies on data quality. PwC's research on capital allocation strategy points to a unified data foundation, linking financial, operational, and strategic metrics, as the difference between a rigorous review and one built on guesswork.
Oracleinvestments applies that same principle to individual stock analysis, scoring companies across profitability, valuation, and financial health on one consistent scale, the same discipline behind Oracleinvestments's portfolio risk assessment workflow. Consider two companies scored on identical metrics: one shows ROIC comfortably above its cost of capital with strong balance sheet health, the other shows ROIC below cost of capital despite similar revenue growth. Side-by-side scoring surfaces that gap immediately, something a narrative pitch deck rarely does.
Why Most Capital Allocation Mistakes Are Behavioral, Not Analytical
The models are rarely the problem. Companies stumble because they spread capital evenly across divisions to avoid internal conflict, ignore kill criteria once a project has a champion, and reward managers for hitting this quarter's number instead of the return on what they invested. Fix the behavior and the framework mostly takes care of itself: concentrate capital where marginal returns are genuinely highest, gate funding to real milestones, and hold committees to their own ranking. If you do one thing this quarter, run the ROIC-versus-WACC diagnostic on every active project and see which ones are actually earning their keep.
— Matt
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Capital Allocation | Strategic Framework + Ratio Calculator | WallStreetPrep
- Capital allocation starts with governance—and should be led by the CEO | McKinsey
- How the best companies allocate capital in 2026 | BCG
FAQ
Can you explain the CAPM in a simple way?
The Capital Asset Pricing Model estimates the return investors should expect for holding a risky asset: it adds a risk-free rate to a risk premium scaled by the asset's volatility relative to the market. It's one of the standard inputs used to calculate the cost of equity inside WACC.
What does a WACC of 12% mean?
A 12% WACC means the company must generate at least a 12% return on invested capital just to cover what its debt and equity investors require. Any project or segment earning below that rate is destroying value even if it's profitable in a simple accounting sense.
What should my asset allocation be at 30%?
Asset allocation by age is a personal investing question, not a corporate capital allocation one, and the right mix depends on individual risk tolerance and goals rather than a fixed rule. For companies, the equivalent question is how much capital to commit to a given segment or project, which should be driven by relative ROIC-versus-WACC spread rather than age or tenure.
What is the 12/20/80 rule?
There's no single, widely recognized rule like "12/20/80" in capital allocation or corporate finance. If you encountered this in a specific context, it likely refers to a firm-specific or informal guideline rather than an established industry standard.