The Sortino ratio tells you how much return an investment earned for each unit of bad volatility it put you through. It takes your average return, subtracts a target return, and divides by downside deviation, a measure that counts only the returns that fell short of that target. Gains never count as risk. That one change makes it a sharper tool than the Sharpe ratio for anyone who worries about losses more than about swings in general.
This guide covers the definition, the formula, a full worked calculation you can repeat in a spreadsheet, how to read a good or bad number, and where the ratio misleads.
TL;DR
- The Sortino ratio measures excess return per unit of downside risk, ignoring upside volatility.
- Formula: (average return minus target return) divided by downside deviation.
- Versus Sharpe: Sharpe divides by total standard deviation, so big gains hurt the score. Sortino does not penalize them.
- Higher is better, but only when you compare investments over the same period with the same target return.
- It is not a complete risk measure. Pair it with drawdown and valuation checks.
Table of Contents
- What the Sortino ratio measures
- The Sortino ratio formula
- Calculate the Sortino ratio: a worked example
- Sortino vs. Sharpe: what is the difference?
- How to interpret the result
- Using the ratio to compare funds and portfolios
- Where the Sortino ratio falls short
- Our perspective: risk starts with what you own
- See the fundamentals behind the risk
- FAQ
- Sources
What the Sortino ratio measures
Every risk-adjusted ratio answers the same question: was the return worth the risk? The Sortino ratio is a risk-adjustment metric that measures an investment's excess return for each unit of downside risk. It isolates harmful volatility from total volatility.
The idea behind it is simple. Most investors do not lose sleep when a stock jumps 15% in a month. They lose sleep when it falls 15%. The ratio is named after Dr. Frank Sortino, who argued that positive deviations should not be penalized the way negative ones are. Traditional volatility treats a surprise gain and a surprise loss as equally "risky." The Sortino ratio does not.
Three inputs drive the result:
- Return: the average return of the investment over your chosen period (monthly, weekly or yearly).
- Target return: the minimum acceptable return, often shortened to MAR. It can be 0%, the risk-free rate, inflation, or a goal such as 7% a year.
- Downside deviation: how far, and how often, returns fell below that target.
The target is the part beginners overlook. Change it and the ratio changes, which is why two published Sortino figures for the same fund can disagree without either being wrong.
The Sortino ratio formula
Written out:
Sortino ratio = (R − T) ÷ DD
- R is the average return per period.
- T is the target or minimum acceptable return, per the same period.
- DD is the downside deviation.
The numerator is excess return over your target. The denominator is where Sortino differs from older measures, so it deserves its own step.
How downside deviation works
Downside deviation takes only the returns that fall below the target, squares those shortfalls, averages the squares over the total number of periods, and takes the square root.
Two details matter:
- You divide by all periods, not just the losing ones. A fund that dips below target in 2 of 60 months should score far better than one that does so in 30 of 60.
- Squaring means a 6% shortfall counts far more than three 2% shortfalls. Big failures are penalized at a quadratic rate, which matches how most people feel about large losses.
Periods that meet or beat the target are entered as zero shortfall. They stay in the count but add nothing to the sum.
Calculate the Sortino ratio: a worked example
The numbers below are a made-up illustration, not real fund data. Suppose a stock returned the following over 12 months, and your target is 0% (you simply want not to lose money in a given month).
| Month | Return |
|---|---|
| 1 | +3% |
| 2 | −2% |
| 3 | +4% |
| 4 | −1% |
| 5 | +5% |
| 6 | +2% |
| 7 | −4% |
| 8 | +3% |
| 9 | +1% |
| 10 | −3% |
| 11 | +6% |
| 12 | +2% |
Step 1: average return. The twelve returns sum to 16%, so the average is 16 ÷ 12 = 1.33% per month.
Step 2: subtract the target. With a 0% target, excess return is 1.33%.
Step 3: isolate the shortfalls. Four months fell below target: −2%, −1%, −4% and −3%.
Step 4: square them. 4 + 1 + 16 + 9 = 30.
Step 5: average over all 12 periods. 30 ÷ 12 = 2.5.
Step 6: take the square root. √2.5 = 1.58%. That is the monthly downside deviation.
Step 7: divide. 1.33 ÷ 1.58 = 0.84 per month.
To express it on an annual basis, analysts often multiply a monthly ratio by the square root of 12 (about 3.46), which gives roughly 2.9. Be careful here. The CFA Institute notes that downside deviation is easy to miscalculate and that simply annualizing historical discrete data can overstate risk. Whatever convention you choose, state it and use it for every investment you compare.
Doing it in a spreadsheet
You do not need special software. Put the returns in column A and the target in a cell. In column B, use a formula that returns the shortfall only when the return is below target, otherwise zero, then square it. Average column B, take the square root, and divide the average excess return by that number. If you prefer to build a trading workflow around risk controls, a TradingView risk management setup can help you act on the numbers you calculate.
How the target changes the answer
Run the same twelve months with a 1% monthly target instead of 0%. Now the 1% month counts as meeting the target, but the +... months of 2% and above still pass, while the lower months add shortfalls: month 1 onward the 3% passes, and months that return less than 1% (−2, −1, −4, −3) fall short by 3, 2, 5 and 4 points. Squares: 9 + 4 + 25 + 16 = 54. Divided by 12 = 4.5, square root = 2.12%. Excess return is 1.33 − 1 = 0.33%, so the ratio drops to about 0.16. Same stock, same period, a very different score. That is why the target must always be disclosed.

Sortino vs. Sharpe: what is the difference?
The Sharpe ratio divides excess return by standard deviation, which measures all dispersion around the average, up and down. The Sortino ratio divides by downside deviation. Our Sharpe ratio guide covers the other side in detail.
Using the same twelve months and a 0% risk-free rate, the sample standard deviation is about 3.20% a month. Sharpe is 1.33 ÷ 3.20 = 0.42 per month, versus 0.84 for Sortino. Sortino is higher because the large positive months (+5%, +6%) inflated the standard deviation but did nothing to downside deviation.
| Sharpe ratio | Sortino ratio | |
|---|---|---|
| Risk measure | Standard deviation (all volatility) | Downside deviation (below target only) |
| Treats big gains as risk | Yes | No |
| Return benchmark | Risk-free rate | Any target or minimum acceptable return |
| Best for | Roughly symmetrical return patterns | Skewed returns, loss-averse investors |
| Main weakness | Punishes upside surprises | Needs a defined target and enough data |
The CFA Institute material states it plainly: Sharpe uses standard deviation, Sortino uses downside deviation, and Sortino is more applicable to negatively skewed distributions. Negative skew means occasional large losses sitting behind frequent small gains, a pattern common in strategies that sell options or lean on leverage. Sharpe can flatter those strategies. Sortino is more likely to expose them.
When returns are roughly symmetric, the two usually rank investments similarly. When they disagree, that is useful information. Maginn and colleagues suggested comparing rankings under both measures to see whether outperformance changes the assessment of risk-adjusted performance. If an investment looks great on Sharpe but mediocre on Sortino, its volatility is mostly on the painful side.
How to interpret the result
A higher Sortino ratio means better risk-adjusted performance: more excess return per unit of downside risk. Beyond that, there is no official grade scale, and rules of thumb vary by source and asset class. Use these practical readings instead:
- Negative: the average return fell below your target. The investment did not even pay you the minimum you asked for.
- Near zero: returns roughly matched the target, with some downside along the way.
- Positive and rising: you were paid more for each unit of downside. Between two candidates, the higher one has been the more efficient so far.
- Very high with few observations: be suspicious. If only one or two periods ever fell below target, the downside deviation is tiny and the ratio can explode. A short, calm track record is not proof of safety.
The number means little in isolation. A Sortino of 1.2 sounds fine until you learn the peer group sits at 1.8. Always compare against similar assets over the same window with the same target.
Using the ratio to compare funds and portfolios
The CFA material describes the main use: investors compare the risk-adjusted performance of different funds or portfolios, provided they use the same minimum acceptable return. It also helps you see how much of a fund's volatility is underperformance rather than welcome outperformance.
A sensible routine:
- Pick one target for every candidate. For a retiree it might be inflation or a withdrawal rate. For a growth investor, a market-return benchmark.
- Pull the same period of returns for each, ideally covering a full market cycle. The Corporate Finance Institute suggests looking at several years or at least a complete business cycle.
- Calculate Sortino and Sharpe side by side.
- Look for disagreement between the two, then investigate why.
- Check the worst stretch with a maximum drawdown calculation, since Sortino averages shortfalls and can hide one deep, prolonged decline.
For a wider view on this family of metrics, see our overview of risk-adjusted returns.
What about the S&P 500's Sortino ratio?
Readers often ask for a single number for the S&P 500. There is no one correct figure, because the result depends on the period, the return frequency (daily, monthly, annual), whether dividends are included, and the target you choose. A figure computed from monthly total returns with a 0% target will differ from one using daily returns and a Treasury-bill rate. To get a benchmark you can trust, download total return data for the period you care about, choose your target, and run the steps above. Then your own fund and the index are measured on identical terms.
Where the Sortino ratio falls short
The ratio is useful, not complete. The Financial Planning Association's journal notes that downside deviation can be miscalculated and that the ratio is not a full measure of risk. In practice, watch for these problems:
- History is not a forecast. A strong score describes what happened, not what the next year holds.
- Short samples mislead. A few calm months can produce an impressive ratio that collapses when the next downturn arrives.
- Target dependence. Two analysts using different targets will not agree, and neither is wrong.
- Averaging hides sequence. A portfolio can have a respectable ratio and still suffer a deep loss at a bad moment. If you are drawing income, read about sequence of returns risk.
- It ignores price paid. The ratio looks backward at returns. It says nothing about whether a company is cheap or expensive today.
That last point is why we treat ratios like this one as a check, not a buying signal. For a broader set of defensive tactics, see our guide to downside protection strategies.
Our perspective: risk starts with what you own
We build Oracle Investments around reported company fundamentals: profitability, valuation and financial health. Our scoring is rule-based, and every input is visible, so you can see why a stock scores the way it does. That shapes how we think about the Sortino ratio.

The ratio is a rear-view mirror. It tells you how bumpy the ride was, using price history. Value investors such as Warren Buffett, Charlie Munger and Peter Lynch framed risk differently: the chance of permanently losing capital, which comes mostly from overpaying for a weak business. A strong balance sheet, steady earnings and a sensible price are what reduce that chance. Downside deviation can only confirm afterwards whether it worked.
So we suggest a two-step habit. First, screen on fundamentals to find businesses you would be comfortable owning through a bad year. Then use Sortino and Sharpe, with a target you have chosen deliberately, to check whether the price history agrees with the story. When both point the same way, your confidence is better founded. When they conflict, you have found the right question to research next. Our piece on screening with fundamentals and timing with technicals explains how the two views fit together.
— Matt
See the fundamentals behind the risk
If you want the forward-looking half of the picture, Oracle Investments scores over 260 stocks on profitability, valuation and financial health, so you can compare companies side by side without building spreadsheets. It also tracks your portfolio, and it is available as a subscription through the Apple App Store. The Premium Annual plan is on our Oracle Investments page.
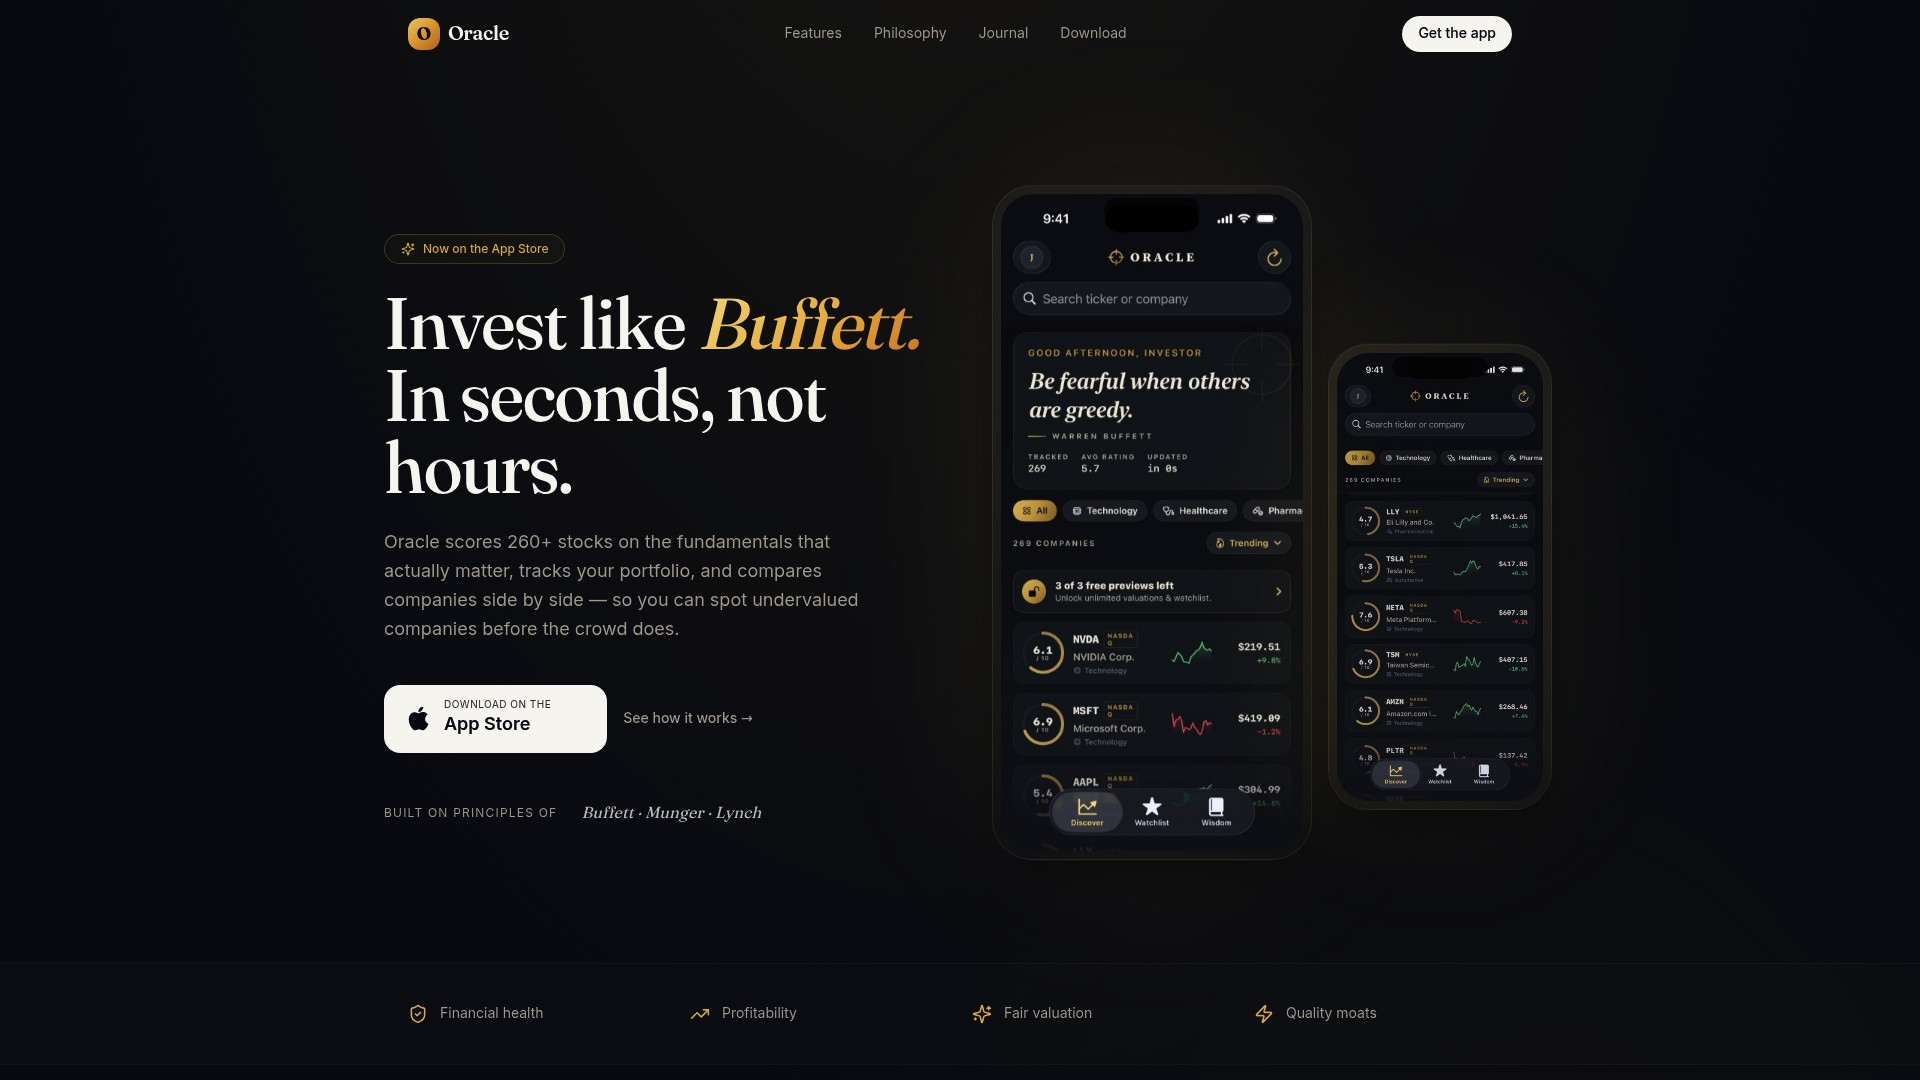
Pair it with the ratio work above: let the scores shortlist the companies, then let Sortino and drawdown tell you how their price history has behaved. If you are new to side-by-side analysis, our guide on how to compare stocks and our walkthrough on reading a value rating are good starting points.
FAQ
What is a good Sortino ratio?
Higher is better, but there is no universal cutoff because the result depends on your target return, the period and the return frequency. Use it to rank similar investments over the same window rather than to pass or fail one. Be cautious of very high figures built on only a few months of data.
Is Sortino better than Sharpe?
Neither is better in every case. Sortino is more suitable when returns are skewed or when you care only about losses, since it does not penalize large gains. Sharpe is simpler and more widely quoted. Running both and examining any gap between them tells you more than either alone.
What target return should I use?
Choose one that reflects your goal: 0% if you only want to avoid losses, a risk-free rate for a Sharpe-style comparison, or inflation or a withdrawal rate if you are funding spending. What matters most is using the identical target for every investment you compare, and stating it.
Can the Sortino ratio be negative?
Yes. If the average return is below your target, the numerator is negative and so is the ratio. It means the investment failed to deliver even your minimum acceptable return over that period. A more negative number is worse, though the scale becomes hard to interpret when downside deviation is small.
How many data points do I need?
More is better, and the sample should span a full market cycle so it includes both good and bad conditions. The Corporate Finance Institute suggests several years at minimum. With only a handful of periods, a single bad month can swing the downside deviation sharply.
Sources
- Sortino Ratio: A Comprehensive Definition and Calculation, Investopedia
- Understanding Downside Deviation: Definition, Uses, and Calculation, Investopedia
- The Sortino Ratio, CFA Institute
- An Intuitive Examination of Downside Risk, Financial Planning Association
- Sortino Ratio: Overview, How To Calculate, When To Use, Corporate Finance Institute
- TradingView Risk Management Setup Tips for Pro Traders