The Beneish M-score is a formula that screens a company's financial statements for signs of earnings manipulation, using eight ratios built from two years of reported data. A score above −1.78 signals a higher probability that management has manipulated earnings and deserves a closer forensic look. Calculating it takes about ten line items and a spreadsheet, or a few minutes with an online calculator.
TL;DR:
- Companies scoring near or above −1.78 have elevated odds of earnings manipulation, especially if their scores exceed −1.60, which warrants detailed financial review.
- Rapid sales growth and shrinking gross margins often trigger the M-score, but may reflect actual high growth, not manipulation.
- A high TATA ratio or increased receivables relative to sales suggests aggressive revenue recognition that should be verified through footnotes and cash flow comparisons.
- The model's accuracy diminishes for industries with high accruals or unusual asset structures, making context-specific analysis essential.
- Regular quarterly checks and comparison with broader valuation metrics help distinguish genuine financial issues from normal business fluctuations.
Table of Contents
- How the Beneish M-score formula works
- A worked example of calculating an M-score
- What the score means and what to check next
- Where the model breaks down and how to use it responsibly
- Trusted calculators and how to use them without errors
- Making the M-score part of a regular screening habit
- A faster way to screen fundamentals alongside the M-score
- Where these figures and formulas come from
- Sources
- FAQ
How the Beneish M-score formula works
The model, developed by accounting professor Messod D. Beneish, combines eight ratios into one linear equation. The commonly cited version of the formula is:
M = −4.84 + 0.92·DSRI + 0.528·GMI + 0.404·AQI + 0.892·SGI + 0.115·DEPI − 0.172·SGAI + 4.679·TATA − 0.327·LVGI
Each ratio compares the current year (t) to the prior year (t−1), pulled from the income statement, balance sheet and cash flow statement:
- DSRI (Days Sales in Receivables Index): receivables divided by sales in year t, versus the same ratio in year t−1. A jump suggests revenue is being recognized before cash changes hands.
- GMI (Gross Margin Index): prior year gross margin divided by current year gross margin. A ratio above 1 means margins are shrinking, a pressure point that can tempt manipulation.
- AQI (Asset Quality Index): the share of total assets that are not current or fixed assets, compared year over year, which flags cost capitalization instead of expensing.
- SGI (Sales Growth Index): current year sales divided by prior year sales, since rapid growth alone raises the odds' of aggressive accounting.
- DEPI (Depreciation Index): prior year depreciation rate divided by current year depreciation rate, which catches a slowdown in depreciation.
- SGAI (SG&A Index): SG&A expense as a share of sales, year over year.
- TATA (Total Accruals to Total Assets): income before extraordinary items minus operating cash flow, divided by total assets.
- LVGI (Leverage Index): total debt divided by total assets, current year versus prior year.
Every input comes from a standard 10-K or annual report. Financial institutions are typically excluded, since their balance sheet structure does not fit the model's assumptions.
A worked example of calculating an M-score
A compact example shows how the pieces fit together. Say a fictional company reports these figures for two consecutive fiscal years, in millions of dollars:
- Receivables and sales: receivables rise from $40 to $60 while sales grow from $400 to $480, pushing DSRI above 1 because receivables are growing faster than sales.
- Gross margin: gross margin falls from 35% to 30%, giving a GMI above 1 and signaling margin pressure.
- Asset quality and leverage: non-current, non-fixed assets grow as a share of total assets, and debt-to-assets ticks up slightly, nudging AQI and LVGI higher.
- Accruals: net income of $50 million against operating cash flow of only $30 million produces a TATA of roughly 0.10, once divided by total assets of around $200 million, a wide gap worth flagging on its own.
- Final score: plugging each ratio into the coefficients and summing the weighted terms might land the M-score around −1.50, above the −1.78 cutoff and worth a second look.
Fiscal-year alignment matters here. Mixing a calendar year with a shifted fiscal year, or blending trailing-twelve-month figures with year-end statements, distorts every ratio built on those figures. The Kelley School of Business calculator accepts twelve raw inputs across two years and returns the M-score, an implied odds ratio, and a comparison against sample averages, which removes most of the arithmetic risk. A calculator speeds the process, but it is only as reliable as the line items typed into it: check that units match (all in the same currency and scale) before trusting the output.
What the score means and what to check next
The −1.78 threshold is not arbitrary. It comes from mapping the M-score to a probability through a probit, or cumulative normal, transformation. At that cutoff, the original mapping implies roughly a 0.0375 probability, or about 3.75%, that the company is a manipulator, a baseline rate that rises sharply as the score climbs further above the cutoff.
Small movements near −1.78 can shift the estimated probability non-linearly, which is why a company scoring at −1.60 deserves more scrutiny than a simple pass/fail label suggests, according to CFA Institute's tutorial on probit analysis.
A flagged company is a starting point for research, not a conclusion. Useful next steps include:
- Reading footnotes on revenue recognition policy changes, which often precede a spike in DSRI or SGAI.
- Comparing accrual growth to operating cash flow growth over several quarters, not just one fiscal year.
- Checking for related-party transactions or unusual one-time adjustments disclosed near the flagged period.
Where the model breaks down and how to use it responsibly
The Beneish M-score is probabilistic, not proof. The original research by Beneish showed statistically significant power to separate manipulators from non-manipulators in holdout samples, but that separation is a tendency, not a certainty.
False positives are common in fast-growing companies, since rapid sales growth and shifting margins mimic the same ratios that flag manipulation. False negatives happen too: a company that manipulates earnings through methods outside the eight ratios, such as off-balance-sheet arrangements, can score clean.
- Genuine high-growth firms often trigger SGI and DSRI without any manipulation at all.
- One-off asset sales or restructuring charges can distort GMI or AQI for a single year.
- Industries with naturally high accruals, like construction or long-term contracting, may need their own normalized benchmarks rather than the general cutoff.
Pro Tip: Run the M-score alongside a broader earnings quality analysis rather than treating either one as a standalone verdict.
Trusted calculators and how to use them without errors
The Kelley School of Business calculator is the most widely cited free tool, built directly from Beneish's coefficients. It asks for twelve inputs across two years and returns the score, an odds ratio, and a comparison to sample averages, which makes it a fast first pass before deeper spreadsheet work.
- Keep every input in the same currency and the same units (thousands versus millions) across both years.
- Map each line item to the exact statement line it came from, so the calculation can be checked later.
- Trailing-twelve-month figures work as long as both years use the same convention.
Favor a manual spreadsheet check whenever a company's fiscal year shifted, or when a merger changed the reported line items year over year.
Making the M-score part of a regular screening habit
A quarterly M-score check on core holdings catches most emerging red flags without becoming a chore, and any score climbing past −1.78 should trigger a deeper read of the notes within days, not months. Pairing that habit with a fundamentals-based value rating gives a second, independent signal before deciding whether a red flag is a real problem or a growth story.
— Matt
A faster way to screen fundamentals alongside the M-score
Running the Beneish M-score by hand teaches you what drives the number, but checking it across a full portfolio quarter after quarter takes time most investors do not have. Oracle Investments scores over 260 stocks on profitability, valuation and financial health using transparent, rule-based inputs, so you can spot which holdings deserve a forensic follow-up before you ever open a 10-K.
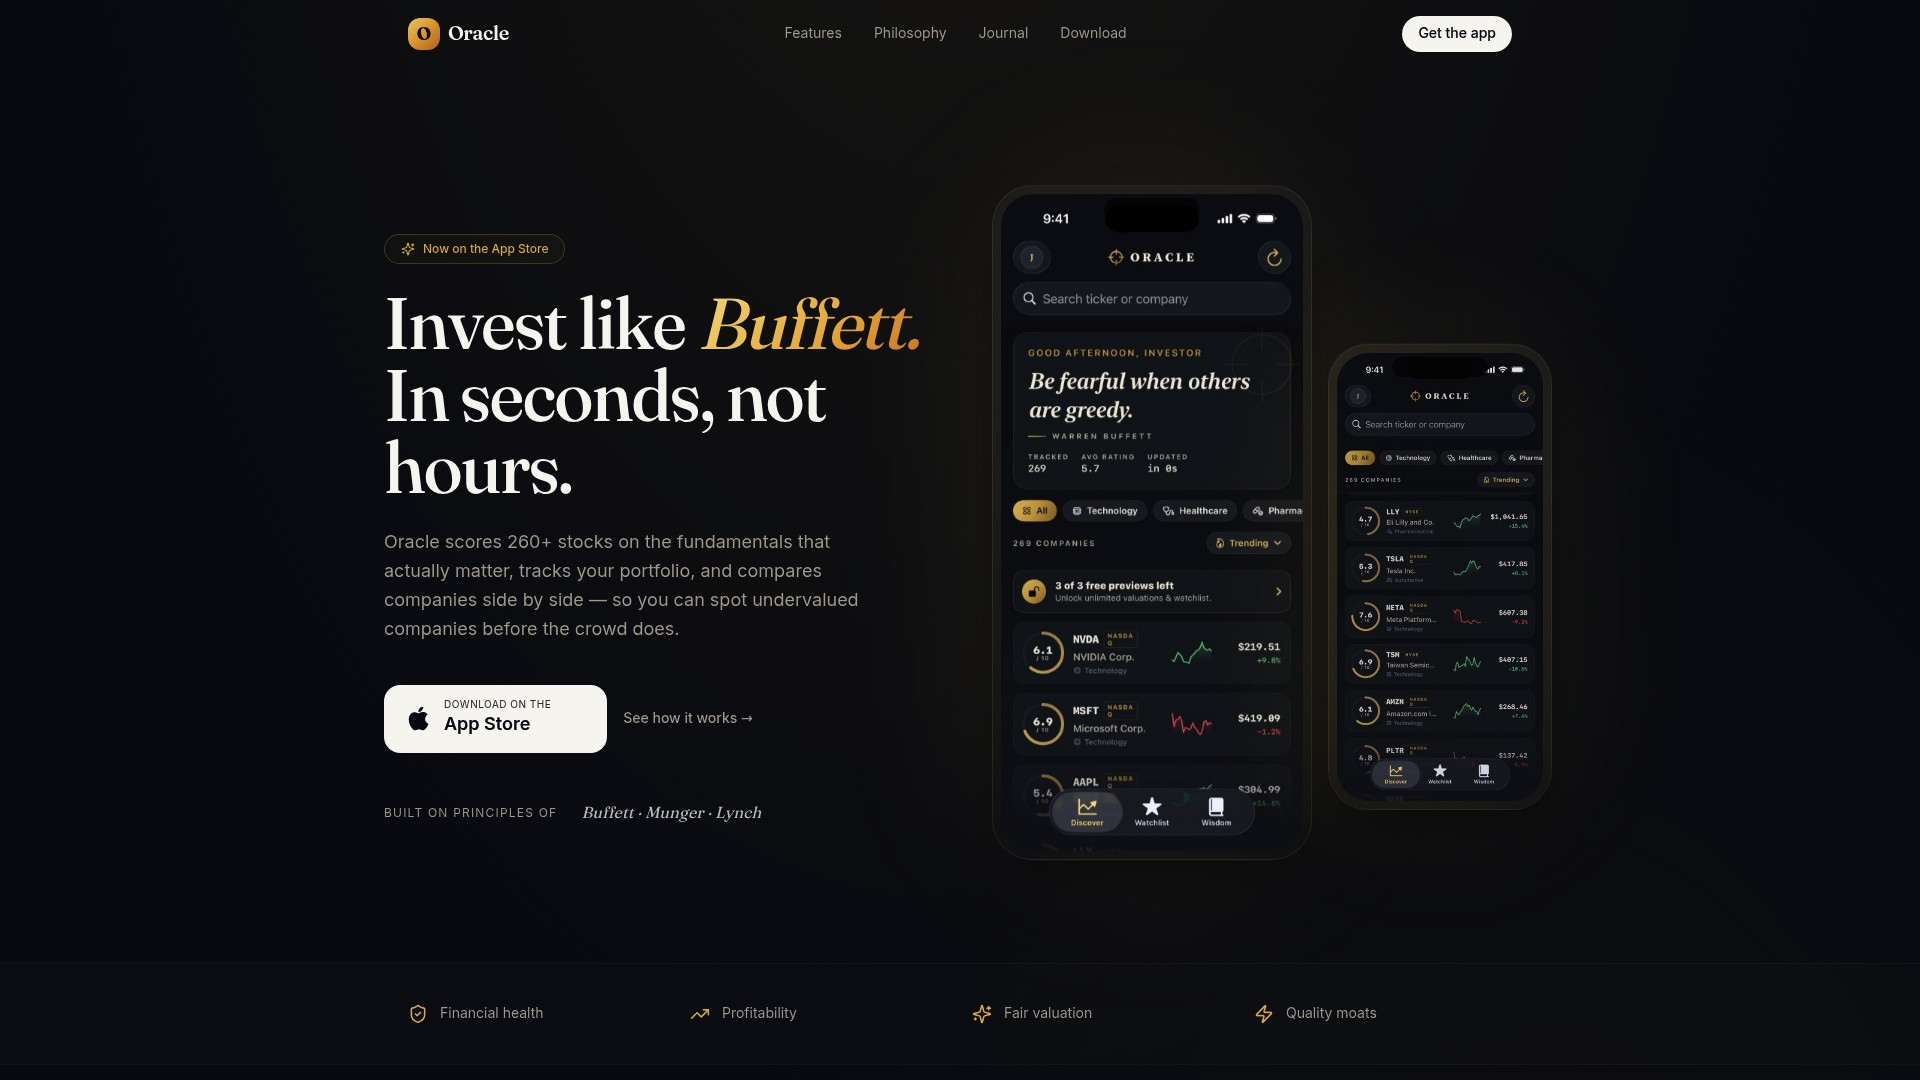
- See every scoring input behind a stock's rating, not just a final grade.
- Compare companies side by side to prioritize where a manual M-score check is worth the time.
- Pair the app's fundamentals view with complementary checks like the Piotroski F-score for a fuller picture.
Start with the Premium Annual plan to track your full portfolio and flag the names worth a closer look.
Where these figures and formulas come from
The formula, cutoff and probability mapping in this article come from the original Beneish 1999 paper, the Kelley School of Business calculator, and CFA Institute's probit analysis tutorial. Readers seeking broader investor perspectives can also explore Aspen's approach to investing.

This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Beneish M-Score Calculator - Kelley School of Business
- The Detection of Earnings Manipulation — Beneish (paper PDF)
- Beneish M-score — Wikipedia
FAQ
What is the Beneish M-score and how is it calculated?
The Beneish M-score is a formula that combines eight financial ratios, drawn from two consecutive years of statements, into a single number that estimates the likelihood of earnings manipulation. It is calculated by plugging ratios like DSRI, GMI and TATA into a linear equation with published coefficients, then comparing the result to a standard cutoff.
How is the M-score calculated step by step?
You calculate each of the eight ratios by comparing the current year to the prior year, then multiply each by its assigned coefficient and sum the results with the model's constant. The final number is compared against the −1.78 cutoff to judge whether further review is warranted.
What does a Beneish M-score above −1.78 mean?
A score above −1.78 signals a higher probability of earnings manipulation and calls for a closer look at the company's notes and accrual patterns. Under the original probit-based mapping, that cutoff corresponds to roughly a 3.75% estimated probability, a baseline that climbs as the score rises further.
Can the Beneish M-score prove a company committed fraud?
No, the M-score is a probabilistic screening tool, not proof of fraud. It is best used to prioritize which companies deserve deeper research into revenue recognition, accruals and note disclosures, rather than as a final verdict.