Yes, mean reversion works as a stock trading approach, but only within a narrow lane: range-bound names over holding periods of days to a few weeks, backed by a regime filter and a hard stop. The edge shows up in short-horizon reversals, not in fighting a real downtrend. The biggest failure mode isn't the math, it's buying a stock that looks statistically cheap while its underlying business is actually falling apart.
TL;DR:
- Mean reversion in stocks works best over short horizons of five to sixty days, particularly in range-bound market conditions, not during strong downtrends.
- Combining technical indicators like RSI(2), Bollinger Bands, and z-scores with a regime filter such as the 200-day moving average improves trade reliability and reduces false signals.
- Effective strategy building requires multiple components: a clear entry signal, a regime filter, a tight stop based on ATR, a defined target, and proper position sizing adjusted for liquidity.
- Backtests must incorporate realistic costs, slippage, and regime variations to accurately measure an edge, which is usually confined to range-bound periods.
- Supplementing technical signals with fundamental analysis helps avoid trades on fundamentally deteriorating stocks, especially when using automation or screening tools.
Table of Contents
- What Mean Reversion Means for Stocks
- Which Indicators Actually Signal a Reversion Setup?
- How Do You Build a Testable Mean Reversion Strategy?
- Backtesting: How Do You Know the Edge Is Real?
- Three Setups You Can Screen and Test Today
- Why Discipline Beats the Indicator You Choose
- Another Way to Screen Before You Trade
- Sources
- FAQ
What Mean Reversion Means for Stocks
Mean reversion is the idea that a stock's price will drift back toward its statistical average after moving too far away from it, whether that average is a 20-day moving average, a sector benchmark, or a paired stock's spread. Traders quantify "too far" using a z-score), which measures how many standard deviations the current price sits from its recent mean. A z-score of negative two means the price has dropped roughly two standard deviations below its typical range, a level many systems treat as statistically stretched.
The concept that separates a workable system from wishful thinking is half-life: the time it typically takes for half the deviation from the mean to close. Practical half-lives for tradable mean reversion in stocks tend to fall between 5 and 60 days, which is why most retail mean-reversion setups hold for a week or two, not a quarter.

Statistic to know: Short-horizon equity reversals, especially in mid-cap names, show measurable statistical edges over 1 to 5 day windows, according to the same half-life research. That's the window where mean reversion tends to outperform. Stretch the timeframe out to months and you're no longer measuring reversion, you're measuring the trend the stock is actually in.
Which Indicators Actually Signal a Reversion Setup?
Four tools do most of the work, and each one answers a slightly different question.
- RSI, particularly the fast-reacting RSI(2) variant, flags short-term exhaustion. A reading under 10 often marks an oversold bounce candidate, while a reading over 90 flags an overbought one, but RSI alone gives no information about the broader trend.
- Bollinger Bands plot a moving average with bands set at a multiple of standard deviation above and below it. A price touching the lower band signals statistical stretch, and band width itself is a regime clue: bands squeezing tight often precede a breakout, while wide bands suggest the stock is already in a volatile, trending phase where reversion setups get less reliable.
- Moving averages (the 20-day, 50-day, and 200-day are the common trio) work less as entry triggers and more as regime filters. A stock trading above its 200-day average is in a structural uptrend, and dips within that uptrend behave differently than dips in a stock already below its 200-day line.
- Z-scores applied to price or to a spread between two correlated stocks give the cleanest, most quantifiable read. Practical systems commonly use thresholds around plus or minus two for entries.
Lookback windows matter more than most traders assume. A 10-day lookback reacts fast but generates noise; a 60-day lookback smooths that noise but reacts slowly to genuine regime shifts. Volatility-normalized thresholds, meaning you adjust your z-score cutoff based on the stock's own recent volatility rather than a fixed number, cut down on false signals in choppier names.
How Do You Build a Testable Mean Reversion Strategy?
A workable blueprint needs five components, and skipping any one of them is how most beginner systems blow up.
- Entry: combine signals rather than trading one alone. A common hybrid is RSI(2) under 10 while the stock trades above its 200-day moving average, or a touch of the lower Bollinger Band paired with a z-score below negative two.
- Regime filter: require the stock to sit above its 200-day average, or check that ADX is below roughly 20 to 25, confirming the market isn't trending hard in one direction. Skip this and you're catching falling knives in a real downtrend.
- Stop: place it below the prior swing low or at 1.5 to 2 times ATR from entry. Remember that a stop order becomes a market order once triggered, and the SEC warns it can fill at a price meaningfully worse than the stop level in a fast-moving market.
- Target: exit at the 20-day moving average or when the z-score returns to zero, whichever comes first.
- Sizing: cap any single position at a small percentage of the portfolio, and cut size further in high-volatility or thin-volume names where slippage eats into the edge fast.
Pro Tip: Reduce position size by half in any stock trading under 500,000 shares of average daily volume. Liquidity gaps are what turn a clean mean reversion trade into a stop that fills three percent below where you expected.
The most common failure mode isn't a bad indicator, it's ignoring the regime filter because the setup "looks too good to skip."
Backtesting: How Do You Know the Edge Is Real?
A backtest only means something if it mirrors real trading friction. Start with a defined universe (liquid mid-caps and large-caps, since pairs trading and z-score approaches require assets that are genuinely cointegrated, not just correlated), a consistent lookback window, and realistic transaction costs and slippage baked into every trade.
Track these metrics, not just total return:
- Win rate and payoff ratio (average winner divided by average loser)
- Sharpe ratio and return skew
- Maximum drawdown
- Measured half-life of the reversion you're trading, checked against your assumed holding period
Split your results by regime. Run the same system through trending periods (high ADX, price above the 200-day average) versus range-bound periods, and you'll usually see the edge concentrate almost entirely in the latter. Be conservative with expectations: quant crowding has compressed some documented mean-reversion anomalies as more participants trade the same signals, so a backtest edge from a decade ago won't necessarily hold up today. This is also where fundamental screening earns its keep. A tool like Oracle Investments can help you filter out statistically cheap stocks whose underlying financial health is actually deteriorating, before you ever put them in a backtest.
Three Setups You Can Screen and Test Today
- RSI(2) dip in a 200-day uptrend: buy when RSI(2) drops under 10 while price sits above the 200-day moving average, with a stop at the prior swing low and a target at the 20-day average. Filter for market cap above $1 billion and average volume above 500,000 shares.
- Cointegrated pair spread: identify two stocks in the same sector with a statistically confirmed cointegration relationship, enter when the spread's z-score crosses negative two, exit at zero, and stop out if the z-score keeps widening past negative three.
- Bollinger lower-band bounce: within a stock that's been range-bound for at least 60 days (confirmed by low ADX), enter on a touch of the lower band, target the midline average, and skip the trade entirely if band width has recently expanded sharply, since that often signals the range is breaking.
Why Discipline Beats the Indicator You Choose
Every trader who's run a mean reversion book eventually learns the same lesson the hard way: the math is the easy part. Start on a small scale, ideally paper trading first, before committing real capital to any of these setups. Pair every technical signal with a basic fundamental check. Debt levels, revenue trend, and return on equity tell you whether a stock is oversold or just broken. Log every trade's actual fill against your intended entry, because slippage on stops quietly erodes backtested edges more than any single bad trade. Keep a running error log of what you got wrong.
— Matt
Another Way to Screen Before You Trade
Running mean reversion setups by hand means checking fundamentals stock by stock, and that's where most retail traders either skip the step or burn hours doing it manually. An investment scoring app evaluates stocks on profitability, valuation, and financial health, allowing users to check whether a technically oversold name's fundamentals support a bounce or reflect a business in decline.
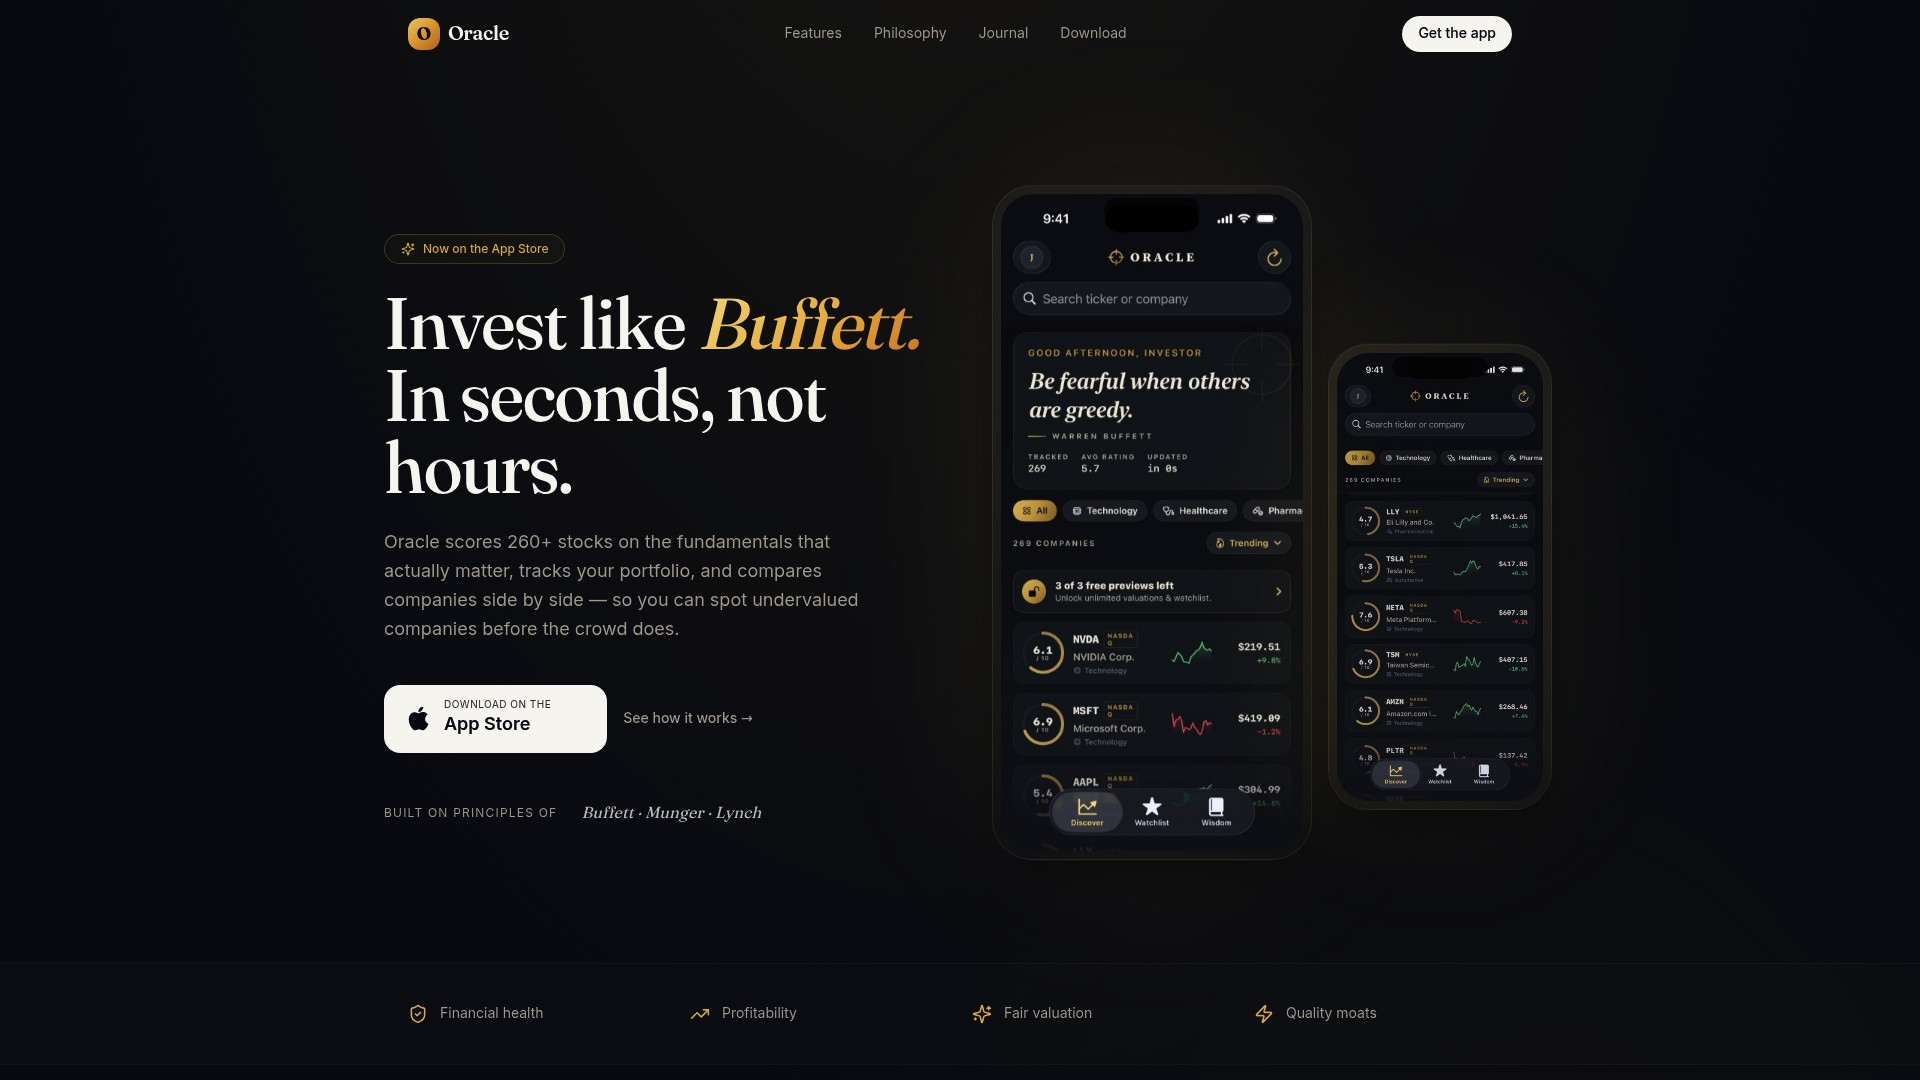
The app is rule-based and built on reported fundamentals rather than a model guessing at outcomes, showing inputs behind the score so users understand why a stock rates the way it does. It also folds in investing principles from well-known value investors, which pairs naturally with the quality-filter step described above. If you're building a mean reversion watchlist and want a fast way to compare candidates side by side or track how your test positions perform, check out Oracle Investments Premium Annual and see how it fits into your screening routine.
Sources
- Mean Reversion: What It Is & How to Trade It in 2026 | Quantt
- Mean reversion trading strategy — QuantifiedStrategies
- Trading 101 basics — SEC investor bulletin (PDF)
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What Is the 7% Rule in Stocks?
The 7% rule is a risk management guideline, most associated with growth investing, that says to sell a stock if it falls around 7% below your purchase price to limit losses. It's not a mean reversion rule specifically, but the same logic applies, a defined stop, whether it's a percentage or an ATR multiple, keeps a single bad trade from wrecking your account.
What Is the Best Mean Reversion Strategy for Making Money?
No single setup works in every market, but combining an oversold signal like RSI(2) with a trend filter like the 200-day moving average tends to outperform any indicator used alone, since it avoids buying dips inside a genuine downtrend. Pairing that with a strict stop and a realistic backtest across different market regimes matters more than the specific indicator you pick.
What Are the Signs That a Reversal Is Coming?
Watch for a price touching or piercing a Bollinger Band while RSI(2) sits in extreme territory (under 10 or over 90), combined with a z-score beyond ±2 relative to its recent average. None of these signals mean much in isolation, and none of them override a stock that's fundamentally deteriorating rather than just technically stretched.
What Is the 3-6-9 Rule in Trading?
There's no single, widely recognized rule with figures like "3-6-9" in mainstream trading literature tied to mean reversion, and definitions vary by source. If you've seen it referenced for a specific strategy, treat it as that source's own framework rather than an established industry standard.
Does Oracle Investments Help With Mean Reversion Trading?
Oracle Investments isn't a technical trading tool, but it scores stocks on fundamentals like profitability and financial health, which helps you separate a genuine bounce candidate from a value trap before you enter a position. Pricing for Premium Annual is available on the Oracle Investments site.