The equity risk premium (ERP) is the extra return investors expect from holding stocks instead of a risk-free asset like the 10-year U.S. Treasury. For practical U.S. valuation work, the most defensible approach is to check a current implied ERP alongside the Kroll recommended U.S. A single-point ERP estimate, used without sensitivity analysis, is one of the most common and costly errors in discounted cash flow (DCF) work.
Key Takeaways
| Point | Details |
|---|---|
| Use implied ERP as your primary input | Back out ERP from current market prices using a DDM or earnings-yield approach for the most market-consistent estimate. |
| Cross-check with Kroll's recommended table | Kroll's U.S. ERP and its paired risk-free rate are the practitioner standard for defensible valuation work. |
| Always run sensitivity analysis | Test your model at base ERP ±1% minimum; present a valuation range, not a single point. |
| Never mix nominal and real rates | Pair a nominal Treasury yield with a nominal ERP; mixing real and nominal inputs produces a meaningless result. |
| Oracleinvestments connects ERP to stock decisions | The app scores 260+ stocks on valuation and fundamentals, giving you a structured way to apply cost-of-equity analysis to real investment choices. |
Table of Contents
- What is the equity risk premium, and how does it work?
- Why does ERP matter for valuation and portfolio decisions?
- What are the three standard methods for estimating ERP?
- How do you calculate ERP step by step?
- Where do practitioners find U.S. ERP reference numbers?
- How do you choose the right ERP for your valuation?
- What are the most common mistakes when using ERP?
- What does history tell us about long-run ERP?
- How Oracleinvestments helps you apply ERP in stock analysis
- A practitioner's perspective on ERP in 2026
- Oracleinvestments: put your ERP analysis to work
- Sources
What is the equity risk premium, and how does it work?
The formal definition is straightforward: ERP = Expected Market Return − Risk-Free Rate. If the S&P 500 is expected to return a certain rate annually and the 10-year Treasury yields a lower rate, the implied ERP is the difference between these rates. That spread is what the market is collectively demanding to own equities instead of government bonds, according to Investopedia's equity risk premium definition.
Inside the Capital Asset Pricing Model (CAPM), ERP scales by beta to produce an asset-specific premium:
Cost of Equity = Risk-Free Rate + β × ERP
A stock with a beta greater than 1.0 and an ERP carries an equity premium above the risk-free rate proportional to the beta. That distinction matters: the ERP is a market-wide number. It measures the price of systematic, undiversifiable risk. It does not capture firm-level risks like a bad earnings quarter, a patent dispute, or a CEO departure. Those idiosyncratic factors belong in cash flow assumptions or a separate company-specific risk premium, not in the ERP itself.
- ERP = market-wide compensation for bearing equity risk
- Firm-specific risk = diversifiable; not captured in ERP
- Beta = the bridge between market-wide ERP and a single stock's required return
A quick numeric illustration: If the 10-year Treasury (GS10) yields a certain rate and you apply an ERP with a beta of 1.0, your cost of equity is the sum. Shifting the ERP can change the cost of equity by a percentage point, which can materially affect a stock's fair value depending on the growth profile.
Why does ERP matter for valuation and portfolio decisions?
ERP sits at the center of nearly every quantitative valuation. Its uses fall into four categories:
- Cost of equity in CAPM: The most direct application. Every DCF model for an equity security needs a discount rate, and ERP is the core input.
- Discount rate for DCF: A higher ERP compresses present values. When ERP rises, future cash flows are worth less today, which is why rising rate environments tend to hit high-growth stocks hardest.
- Asset-allocation benchmark: Comparing the implied ERP to historical norms helps portfolio managers decide whether equities are cheap or expensive relative to bonds — a form of earnings yield vs. Treasury comparison.
- Market sentiment gauge: ERP is not a precise predictor of next year's returns. Think of it as a thermometer, not a forecast. When implied ERP is unusually low, the market is pricing in optimism; when it spikes, fear is doing the pricing.
The sensitivity point deserves more attention than most analysts give it. That is not a rounding error. It is the difference between "fairly valued" and "overvalued" in many analyst reports. Running sensitivity on ERP is not optional; it is the minimum standard for credible valuation work.
Multi-factor models like the Fama-French three-factor model add size and value premiums on top of the market ERP. The ERP remains the foundation — the price of market risk — while the additional factors capture return patterns that CAPM alone cannot explain.
What are the three standard methods for estimating ERP?
Practitioners use three broad approaches, and they rarely agree on a number. Understanding why they diverge is as useful as knowing the methods themselves. The 2026 ERP review by Damodaran covers all three in depth, along with their practical trade-offs for valuers.
Historical premium
You take a long series of equity returns (typically the S&P 500 or a broad U.S. index), subtract the risk-free return for each year, and average the excess returns. The debate is in the details: arithmetic vs. geometric mean, which start date, which risk-free proxy. Geometric averages are lower and better reflect compounded wealth; arithmetic averages are higher and theoretically correct for a one-period forward estimate. Neither is wrong — they answer different questions.
Survey-based premium
CFOs, analysts, and academics are asked what ERP they expect. Surveys reflect current sentiment but are subject to anchoring bias and recency effects. Survey premiums reflect current sentiment but are subject to anchoring bias and recency effects. When markets have just rallied, surveys tend to produce lower ERP estimates; after a crash, they spike.
Implied (forward-looking) premium
This is the method most practitioners prefer for current valuations. You back out the ERP from today's market prices using a dividend discount model (DDM) or an earnings-yield approach. The logic: if you know the current index level, expected earnings or dividends, and a long-run growth rate, you can solve for the discount rate the market is implying — and subtract the risk-free rate to get the ERP. Damodaran's historical implied ERP series is the most widely cited public resource for this approach.
Pro Tip: When you need an ERP for a live valuation, start with the implied method for the current market signal, cross-check against the Kroll recommended U.S. ERP table for practitioner consensus, and use the historical average only as a long-run sanity check — not as your primary input.
| Method | Pros | Cons | Data needed | Typical bias |
|---|---|---|---|---|
| Historical | Long data history; objective | Backward-looking; sensitive to start/end date | Index returns, T-bill or T-bond series | Upward if using post-WWII bull period |
| Survey | Reflects current expectations | Anchoring; recency bias; low sample size | CFO/analyst survey results | Procyclical (low after rallies, high after crashes) |
| Implied/forward-looking | Forward-looking; market-consistent | Sensitive to growth assumptions | Index price, earnings or dividend forecasts | Depends on growth rate assumption |
How do you calculate ERP step by step?
Historical ERP calculation
- Choose your time period. A common choice is 1928 to present using annual S&P 500 data. Shorter windows (10–20 years) are noisier and more sensitive to the start/end market level.
- Gather equity returns. Use total return data (price appreciation plus dividends) for the S&P 500 or a comparable broad U.S. index.
- Select your risk-free series. The 10-year Treasury (GS10) is standard for long-horizon valuations. The 3-month T-bill is sometimes used for shorter-horizon work.
- Compute annual excess returns. For each year: Excess Return = Equity Return − Risk-Free Return.
- Average the excess returns. Arithmetic mean for a one-period forward estimate; geometric mean for a compounded long-run estimate. The arithmetic mean will be higher.
- Note the result and its standard error. Historical ERPs carry wide confidence intervals — often ±2–3 percentage points — which is itself an argument for sensitivity analysis.
A simplified example: if the S&P 500 has historically earned a significantly higher annual return than the 10-year Treasury over a long period, the arithmetic historical ERP is the approximate difference between these returns.
Implied ERP using earnings yield
The earnings yield is simply E/P — the inverse of the P/E ratio. A common shorthand for an implied ERP is:
Simple Implied ERP ≈ E/P − 10-Year Treasury Yield
- If the S&P 500 P/E is 22, then E/P = 1/22 ≈ 4.55%
- If the 10-year Treasury yields 4.3%, then Simple Implied ERP ≈ 4.55% − 4.30% = 0.25%
The E/P − GS10 dataset going back to 1871 shows this spread turned negative in 2023, which is not a forecast of negative equity returns — it reflects that earnings yields compressed relative to bond yields, a regime shift worth understanding rather than mechanically extrapolating.
A more structured implied ERP uses a two-stage DDM:
Spreadsheet workflow:
- Cell A1: Current S&P 500 index level (e.g., 5,500)
- Cell A2: Expected earnings per share for next 12 months (consensus estimate)
- Cell A3: Payout ratio or expected dividends
- Cell A4: Near-term growth rate (analyst consensus, years 1–5)
- Cell A5: Terminal growth rate (e.g., 2.5%, roughly nominal GDP)
- Cell A6: 10-year Treasury yield (GS10, pulled from FRED)
- Solve for the discount rate (r) that sets the present value of the dividend stream equal to A1 — that r is the implied cost of equity. Subtract A6 to get the implied ERP.
Wall Street Prep's ERP calculator walks through this formula structure with worked examples useful for analysts building their first model.
Where do practitioners find U.S. ERP reference numbers?
No single source owns the ERP. Professionals triangulate across several references, updating their inputs at least annually and more often when market conditions shift materially.
| Source | What it publishes | Notes | Update frequency |
|---|---|---|---|
| Kroll (formerly Duff & Phelps) | Recommended U.S. ERP and accompanying risk-free rate | Practitioner-standard table; includes recommended GS10 pairing | Periodic; check their Cost of Capital Navigator |
| Damodaran (NYU Stern) | Implied ERP series and historical implied ERP files | Most widely cited academic/practitioner implied series | Monthly (implied); annual (historical files) |
| S&P U.S. Equity Risk Premium Index | Index-based ERP commentary and data | Useful for market-level context and benchmarking | Regular index updates |
| Wall Street Prep | Educational ERP calculator and formula guides | Best for learning the mechanics; not a live data source | Static / course-cycle updates |
Key notes for practitioners:
- Kroll's recommended U.S. ERP is paired with a specific recommended risk-free rate. Use them together — mixing Kroll's ERP with a different risk-free rate breaks the internal consistency of the estimate.
- Damodaran's implied series is available as downloadable Excel files from NYU Stern. The January update is the most commonly cited in valuation reports.
- GS10 (10-year Treasury constant maturity) is the standard risk-free rate for U.S. equity valuations. Pull it from the Federal Reserve's FRED database for the most current reading.
How do you choose the right ERP for your valuation?
The choice depends on four factors: your time horizon, the purpose of the valuation, data availability, and the current market regime.
Time horizon: For a long-horizon DCF (10+ years), the implied ERP anchored to current market prices is the most internally consistent choice. It reflects what the market is pricing today, which is what you are trying to value. Historical averages are more appropriate as a cross-check or for regulatory/rate-setting contexts where long-run stability is valued over current-market precision.
Purpose of the valuation: Litigation and regulatory proceedings often require a defensible, documented methodology — Kroll's recommended table is widely accepted in U.S. courts and regulatory filings precisely because it is explicit about its methodology. Academic work may prefer Damodaran's implied series for its transparency and reproducibility.
Adjusting for company-specific risk: The market ERP applies to a stock with beta = 1.0. For a small-cap growth stock with beta = 1.5, the equity premium is 1.5 × ERP. For firms with significant leverage, consider re-levering beta using the debt-to-equity ratio before applying it to the ERP. Country risk spreads are added on top for non-U.S. operations.
Present the output as a range, not a point estimate. Stakeholders who see only one number are being given false precision.
Pro Tip: If your base-case ERP produces a valuation that is suspiciously close to the current market price, that is a red flag — not a confirmation. It may mean your ERP is reverse-engineered from the price rather than independently estimated. Always derive ERP from a method, then apply it to the price.
What are the most common mistakes when using ERP?
Most ERP errors fall into a few predictable categories, and the 2026 ERP practitioner review.pdf) flags several of them explicitly.
- Mixing nominal and real rates. If your risk-free rate is a nominal Treasury yield, your ERP must also be derived in nominal terms. Using a real earnings yield against a nominal bond yield produces a number that is neither fish nor fowl.
- Using a short sample window. A 10-year historical ERP estimated from 2014–2024 captures a low-rate, high-multiple environment that may not represent the long run. Short windows amplify recency bias.
- Treating E/P − 10Y as a forward forecast. A negative or near-zero E/P − GS10 reading (as seen in 2023) does not mean equities will underperform. It means earnings yields compressed relative to bond yields — a structural observation, not a return prediction.
- Applying market ERP without a beta adjustment. The ERP is a market-wide number. Applying it directly to a specific stock without scaling by beta overstates the required return for low-beta stocks and understates it for high-beta ones.
- Ignoring regime shifts. An ERP estimated from the 1950–1980 inflationary period looks very different from one estimated in the 2010–2020 low-rate era. Blending them without adjustment can produce a number that reflects no regime accurately.
The correct response is to recognize that the simple E/P proxy is a backward-looking yield comparison, cross-check it against an implied DDM-based ERP, and use the Kroll recommended table as a practitioner anchor.
Pro Tip: Document every ERP assumption in your model: the source, the date pulled, the method, and the risk-free rate it is paired with. If you cannot explain your ERP choice in two sentences, it is not ready for a client presentation.
What does history tell us about long-run ERP?
Long-run evidence on the equity risk premium is both compelling and humbling. The Mehra and Prescott retrospective documents that historical U.S. equity returns have exceeded safe returns by margins that standard consumption-based models struggle to explain — a phenomenon they labeled the "equity premium puzzle."
The E/P minus 10-year Treasury dataset going back to 1871, constructed from Shiller's data, shows how much this spread has varied across regimes. It was deeply negative in the late 1970s and early 1980s (when bond yields spiked), strongly positive through much of the post-war period, and compressed again in the 2020s. The series is useful for historical context but carries a critical caveat: it is a backward-looking yield comparison, not a structural forward-looking estimate.
What does this mean for practitioners? Historical averages carry wide uncertainty bands. The puzzle itself suggests that either investors were irrationally risk-averse in the past, or that future equity returns will be lower than history implies — neither of which is a comfortable foundation for a single-point ERP assumption.
The practical takeaway: use historical series for context and as a sanity check on implied estimates. When the implied ERP and the historical average diverge significantly, that divergence is itself informative — it tells you something about current market pricing relative to long-run norms.
How Oracleinvestments helps you apply ERP in stock analysis
Applying ERP correctly requires pulling live Treasury rates, selecting a practitioner ERP source, assigning a beta, and running the cost-of-equity calculation — then repeating it across scenarios. That workflow is where errors accumulate.
Oracleinvestments streamlines this process for individual investors and analysts working through stock valuation:
- Real-time financial data: The app tracks key fundamentals across more than 260 stocks, giving you the profitability and valuation inputs you need to contextualize ERP-driven cost-of-equity estimates.
- Side-by-side stock comparisons: Compare two companies' valuation profiles simultaneously, which makes it easier to see how different beta assumptions and ERP inputs shift relative attractiveness.
- Valuation scoring: Oracle's scoring system incorporates valuation metrics that interact directly with discount rate assumptions — helping you spot stocks where a higher ERP would flip the valuation signal.
- Investment wisdom integration: The app embeds frameworks from Warren Buffett, Charlie Munger, and Peter Lynch, grounding quantitative ERP work in the qualitative judgment that separates good analysis from mechanical number-crunching.
Pro Tip: Use Oracleinvestments' side-by-side comparison to run a quick sensitivity check: find two similar companies with different betas and apply your ERP range to both. The spread in implied cost of equity will show you exactly how much beta choice matters relative to ERP choice.
For a deeper look at how valuation scores translate into investment decisions, the Oracle value rating guide explains the scoring methodology in plain terms.
A practitioner's perspective on ERP in 2026
The debate between implied and historical ERP has never been fully resolved, and it probably never will be. My view: in 2026, with Treasury yields meaningfully above their post-2008 lows and equity multiples still elevated by historical standards, the implied ERP deserves more weight than the historical average in most U.S. valuation contexts. The historical average reflects a world of structurally lower rates and different inflation regimes — applying it mechanically today risks systematically underestimating the discount rate. That said, no single implied estimate should be trusted without a historical cross-check and a sensitivity run. The right answer is almost always a range, presented honestly, with the assumptions documented. Analysts who report a single ERP number as if it were a fact are either overconfident or under-informed.
Oracleinvestments: put your ERP analysis to work
Most investors spend hours building ERP assumptions and then struggle to connect those inputs to actual stock decisions. Oracleinvestments closes that gap. The app scores over 260 stocks on profitability, valuation, and financial health — giving you a structured way to apply the cost-of-equity framework this guide covers without building everything from scratch in a spreadsheet.
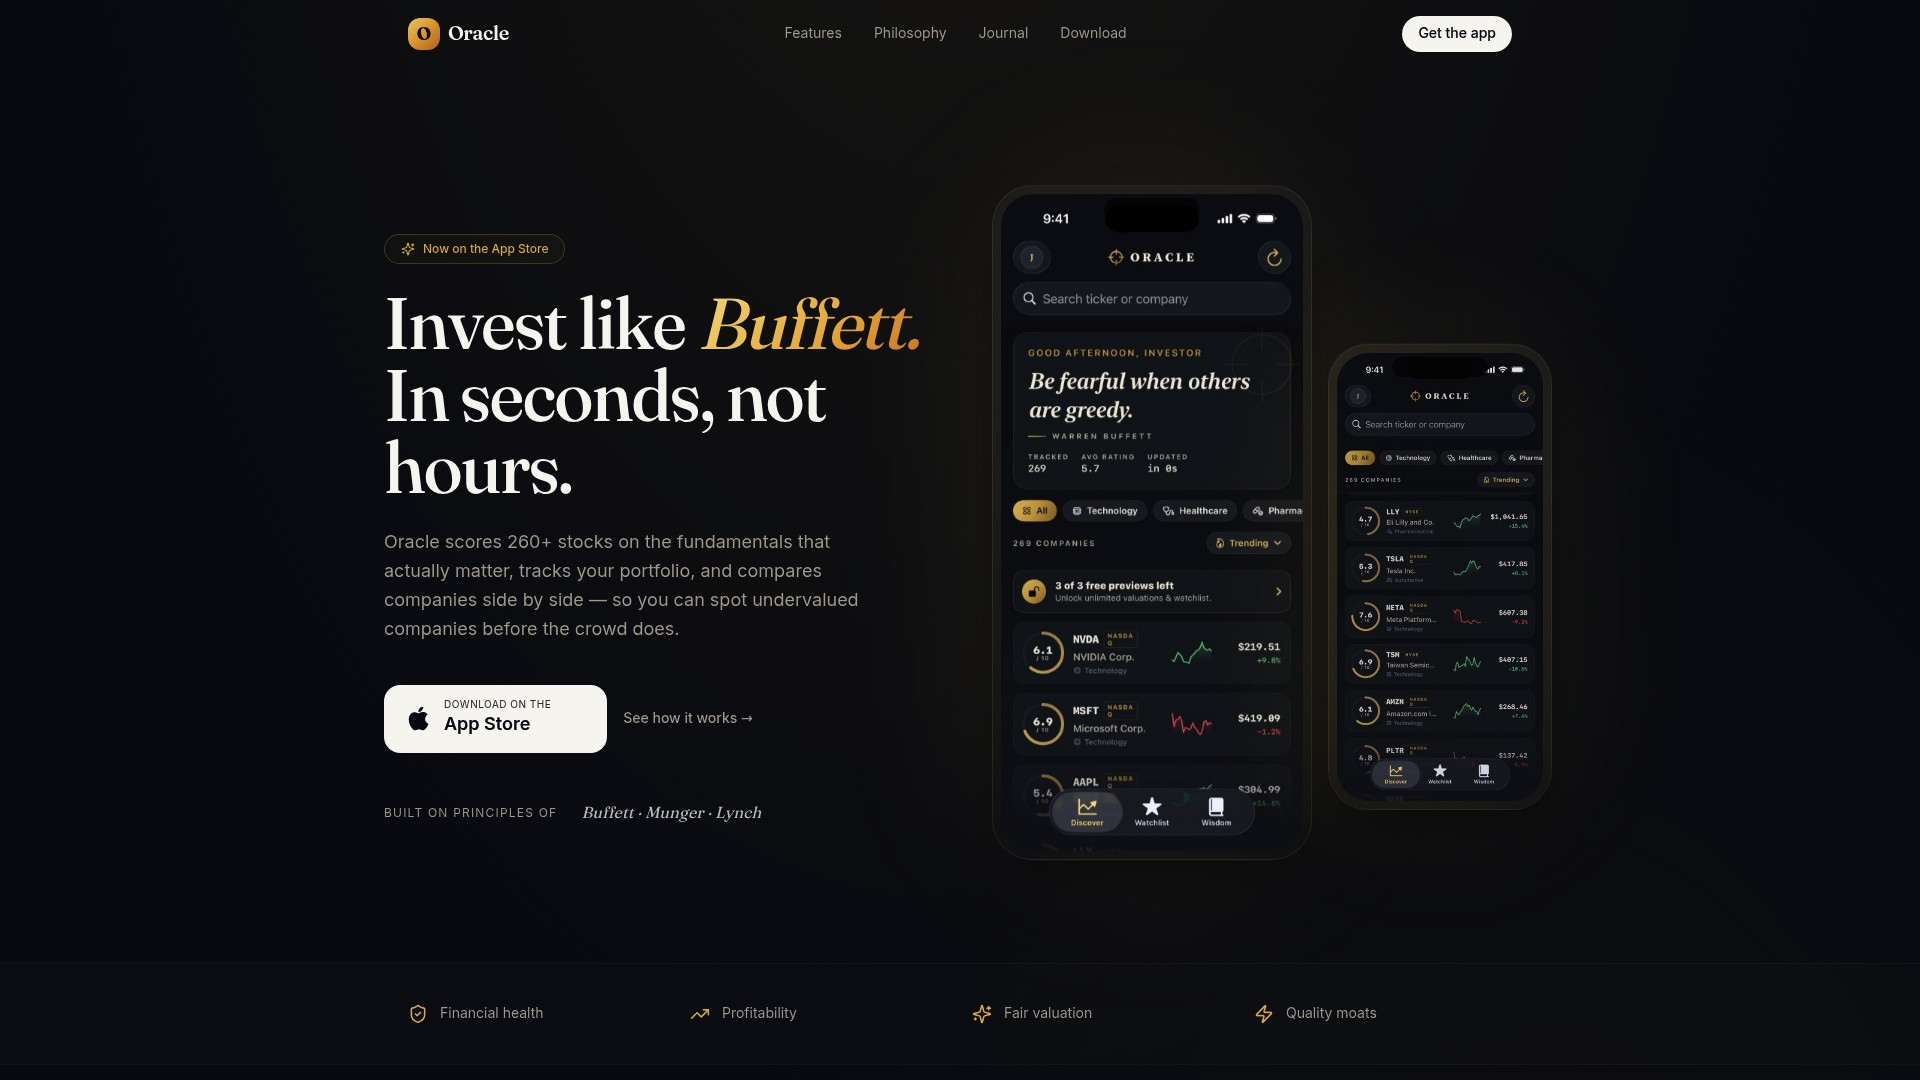
Where this guide gives you the methodology, Oracleinvestments gives you the data layer: real-time fundamentals, instant comparisons, and valuation scores that reflect the kind of discount-rate thinking that ERP analysis demands. It is available on the Apple App Store, and the Oracle Investments landing page shows exactly what the subscription includes. If you are serious about applying ERP to real stock decisions rather than just understanding it in theory, that is the logical next step.
Sources
- Equity risk premium (Investopedia)
- US Equity Risk Premium: E/P Minus 10Y Treasury Since 1871
- THE EQUITY PREMIUM IN RETROSPECT
- Historical Implied Equity Risk Premiums
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.