A 13F filing is a quarterly list of the U.S. stocks a large investment manager held on the last day of a quarter. It is useful research for finding ideas and checking conviction, but it is a snapshot that arrives late, so it works best as a starting point for your own analysis of a company's fundamentals, not as a signal to buy or sell. Oracle Investments scores over 260 stocks on profitability, valuation and financial health, which gives you a way to test any name you spot in a 13F against the numbers.
TL;DR
- Form 13F is a quarterly report of long stock holdings from institutional managers that oversee $100 million or more in qualifying securities.
- It is filed within 45 days of quarter end, so you are always looking at a position that is at least several weeks old.
- It leaves out short positions, cash, bonds, foreign shares and private holdings, so a visible stock may be hedged in ways you cannot see.
- Compare share counts between quarters, not dollar values, to see what a manager actually bought or sold.
- Treat a 13F position as a reason to research a company, then check its fundamentals yourself.
Table of Contents
- What a 13F filing is and who files one
- What counts as a 13F security
- When 13F filings are due
- What a 13F shows, and how to read one
- How to compare 13F filings over time
- What 13F filings leave out
- Using a 13F as research, not as a signal
- Where Oracle fits in
- Our perspective
- Frequently asked questions
- Sources
What a 13F filing is and who files one
Form 13F is the report institutional investment managers file under Section 13(f) of the Securities Exchange Act of 1934. The SEC's Form 13F FAQ says a manager must file when it uses U.S. mail or other interstate commerce in its business and exercises investment discretion over $100 million or more in Section 13(f) securities. "Investment discretion" simply means the manager decides what to buy and sell.
The definition of a manager is broad. Investor.gov explains that it covers investment advisers, banks, insurance companies, broker-dealers, pension funds and corporations that manage their own portfolios. That is why you will find famous hedge funds, giant index fund companies and small family-run advisers all in the same database.
The filing is electronic. The SEC's Form 13F instructions require submission through EDGAR, the SEC's public filing system, unless a hardship exemption is granted. Anyone can read the results for free.

What counts as a 13F security
Only certain securities are reported. According to Investor.gov, these include exchange-traded equities (Nasdaq included), certain equity options and warrants, closed-end fund shares and certain convertible debt. Open-end mutual fund shares are excluded. The SEC publishes an official list of qualifying securities each quarter, and the SEC FAQ points filers to it.

The practical meaning: a 13F is strongest for managers whose money sits mostly in U.S. stocks. For a manager who invests heavily in bonds, foreign markets, private companies or derivatives, the filing shows only a slice of the portfolio.
When 13F filings are due
The rule is a 45-day lag. The SEC's instructions say a filer reports within 45 days after the end of each calendar year and after each of the first three calendar quarters of the following year. In practice, that gives you a rhythm:
| Quarter end | Filing deadline (about) |
|---|---|
| March 31 | mid-May |
| June 30 | mid-August |
| September 30 | mid-November |
| December 31 | mid-February |
When the 45th day falls on a weekend or holiday, the deadline moves to the next business day. The SEC FAQ lists the exact dates for each year, and it is the page to check for the current schedule. Many managers file close to the deadline, so the most useful batch of filings tends to land in the last week or two before it.
What a 13F shows, and how to read one
Each filing has three parts you will meet on EDGAR.
The cover page. It gives the reporting period (a calendar quarter end), the manager's name and address, and the type of report. A "13F-HR" is the standard holdings report, and a "13F-HR/A" is an amendment. A sample EDGAR filing shows this layout.
The summary page. It lists the number of line items and the total reported value. That one figure gives you a quick sense of scale. The same sample filing shows 6,977 entries, which is typical of an index-style manager with thousands of holdings, and very different from a concentrated fund with 20.
The information table. This is where the research happens. An SEC information table has these columns:
| Column | What it tells you |
|---|---|
| Name of issuer | The company |
| Title of class | Common stock, ETF shares, and so on |
| CUSIP | A nine-character ID for the security, useful for matching rows between quarters |
| Value | The market value at quarter end |
| Shares or principal amount | How many shares the manager held |
| Put/Call | Flags positions that are options |
| Investment discretion | Whether the manager decides alone (sole), shares the decision or neither |
| Voting authority | Who votes the shares |
Start with the largest positions by value, then look at the share count and the put/call column. A row marked "Put" or "Call" is an options position, not stock ownership, and reading it as a share holding is a common beginner mistake.
A note on how values are reported
Older filings report values in thousands of dollars. The SEC's amendments to Form 13F, effective January 3, 2023, require values rounded to the nearest dollar and drop the old convention of omitting the trailing "000". If you compare a 2021 filing with a 2025 one, check the header so you do not misread a figure by a factor of 1,000. The same rule also allows optional disclosure of a security's FIGI identifier.
How to compare 13F filings over time
One filing is a photograph. Two or more filings in a row tell a story. Here is a simple routine for any manager you follow.
- Open the manager's two most recent 13F-HR filings on EDGAR. Put the latest and the prior quarter side by side.
- Match rows by CUSIP, not by name. Company names can be written differently between filings, while the CUSIP stays the same.
- Compare share counts, not dollar values. Value moves with the stock price. If shares are unchanged and the value rose 20%, the manager did nothing: the stock did.
- Sort the changes into four groups: new positions, added shares, trimmed shares and complete exits.
- Look at the position's weight. A new position worth 0.3% of the portfolio is a small bet. A new position worth 8% is a statement.
- Check several quarters. A manager who has added to the same company for four quarters straight tells you more than one who bought once.
This is a method, not a guarantee. A bigger share count can come from a stock split or from a client adding money to a fund, so it is worth reading the company's own news before you read anything into the change.
What 13F filings leave out
This is where most mistakes happen. The SEC FAQ and Investor.gov together point to these gaps:
- Short positions. The FAQ says shorts must not be reported or netted against longs. A big long position can be partly or fully hedged and you would never know. If shorting is new to you, our guide to short interest explained for beginners covers the basics.
- Written options. Options a manager has sold are not reported. Held options and warrants on the official list may be.
- Cash, bonds and non-listed assets. Only qualifying securities appear, so cash, most bonds, open-end mutual funds, foreign-listed shares and private holdings are absent.
- Cost basis. You see how many shares were held, not what the manager paid. You cannot tell whether a position is a gain or a loss.
- Small positions. Positions under 10,000 shares and under $200,000 in value may be omitted.
- Intra-quarter trades. Anything bought and sold between quarter ends never shows up.
- Confidential treatment. A manager can request that certain positions be withheld for a period.
Short-position reporting is a separate matter. According to Dechert's 2026 compliance reminder, the SEC's rules for reporting short positions on Form SHO were sent back by the Fifth Circuit in August 2025 and the SEC has issued temporary exemptions, so short-position disclosure is not in effect.
Using a 13F as research, not as a signal
By the time you read a 13F, the data is up to about 135 days old: a quarter has passed, plus up to 45 days. A manager may already have sold what you are looking at. Copying a filing line by line means you buy after the move, without knowing the manager's cost, their hedges or their reason.
What a 13F does well is narrow your search. Three uses work for individual investors:
- Idea generation. If a long-only value manager opens a new position, that company deserves a look.
- Conviction check. If you already own a stock, seeing experienced managers add to it over several quarters is context, not proof.
- Learning. Reading how disciplined investors build concentrated portfolios teaches you more than any glossary.
In every case, the next step is the same: look at the company yourself. That means profitability, valuation and financial health. Our guide to comparing stocks with 3 to 6 metrics gives a five-step template, and screening with fundamentals and timing with technicals explains why the order matters. Insider purchases are another disclosure worth pairing with a 13F, and how to read insider buying signals shows how. If a manager you follow trades a lot, portfolio turnover tells you how quickly a quarter-old snapshot goes stale.
A worked example
Suppose a manager you follow held 2,000,000 shares of a company in March and 3,000,000 in June. That is a 50% increase in shares, whatever the price did. Now suppose that position is 6% of a 40-stock portfolio. That is a meaningful bet. You would then check whether the company's profit margins, valuation and debt justify the interest. If the numbers do not stand up, the manager's name is not a reason to buy. If they do, you have found an idea through someone else's work and confirmed it through your own.
Where Oracle fits in
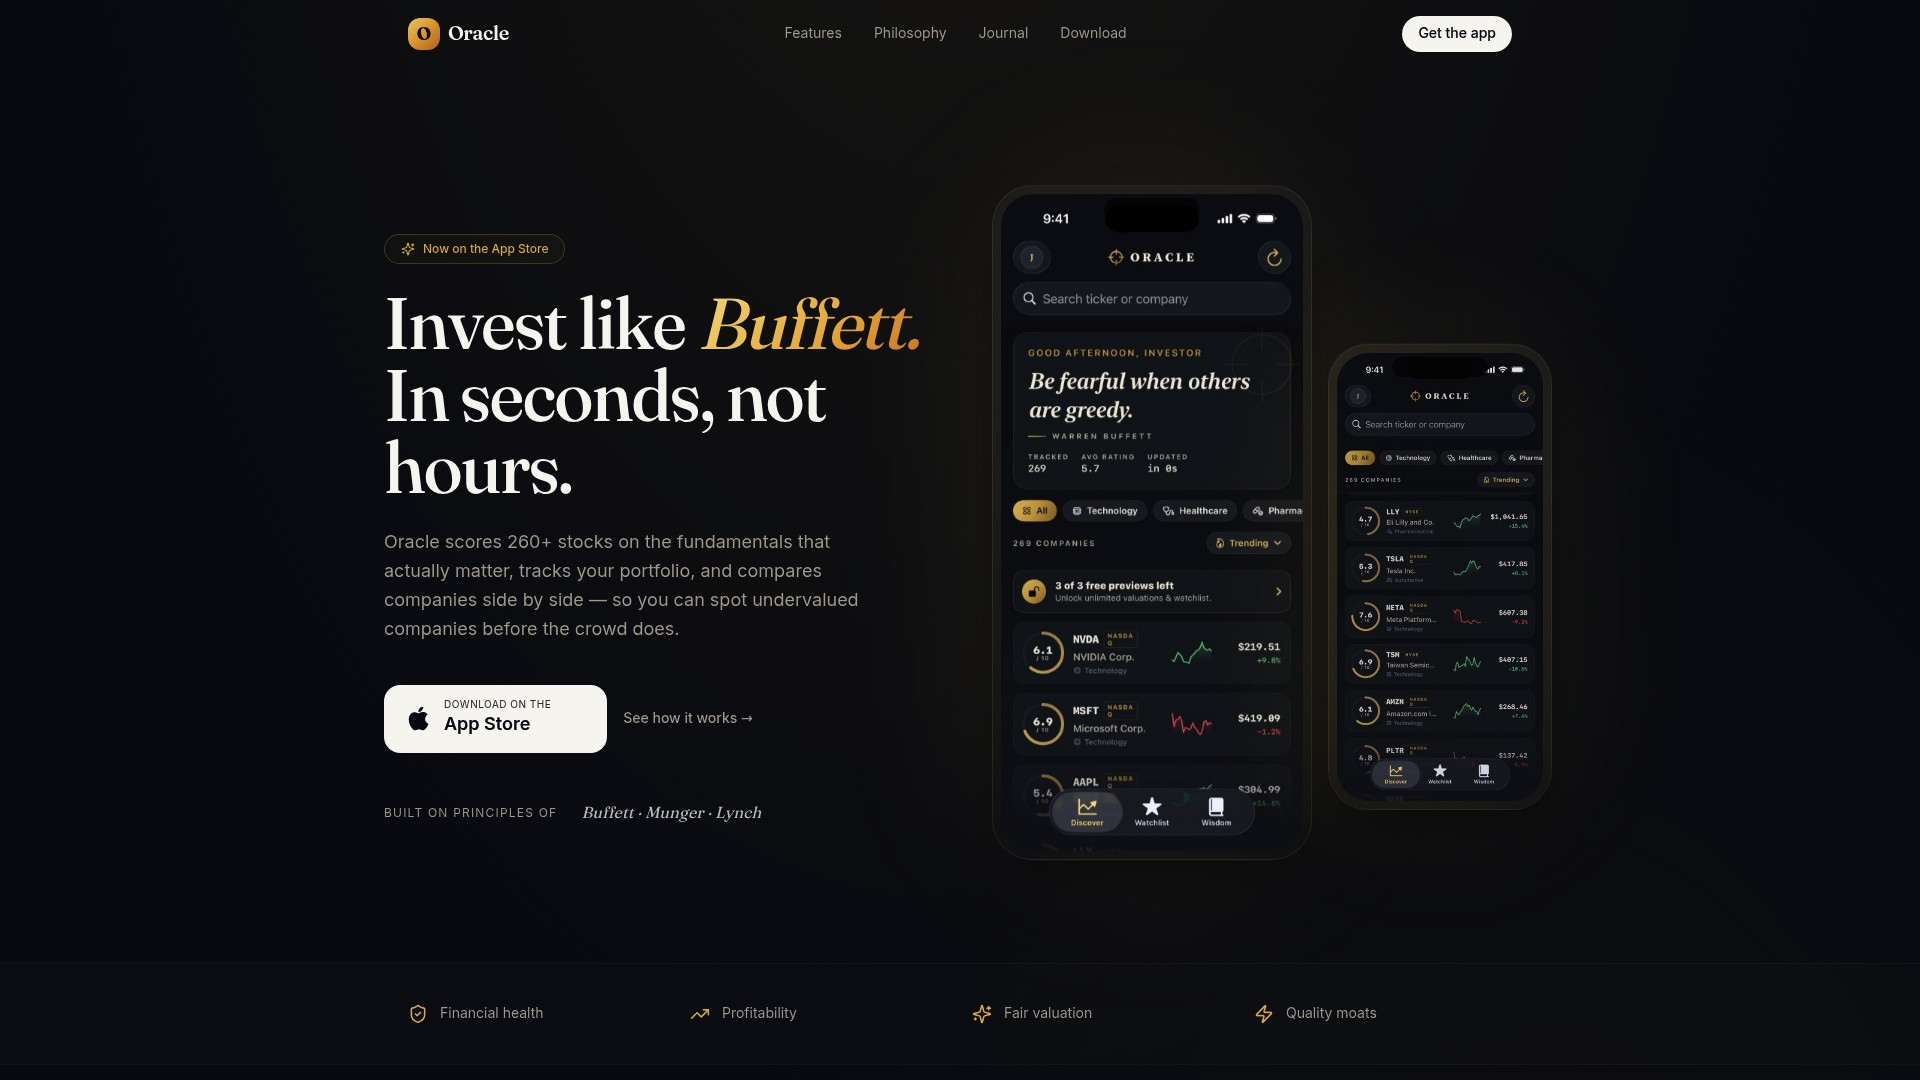
A 13F gives you a name. The harder part is deciding whether the company is worth owning at today's price. Oracle Investments scores over 260 stocks on key fundamentals, and the scoring is rule-based, with all inputs shown. You can place two companies side by side, such as a stock a manager added and the one it replaced, and see the differences in profitability, valuation and financial health. If you are new to reading scores, how to read a value rating in under a minute walks through it.
The app also carries the thinking of Warren Buffett, Charlie Munger and Peter Lynch, the sort of investors whose holdings people often look up in 13Fs. It tracks your portfolio in real time as well, so your own holdings sit next to the ideas you collect.
Our Premium Annual plan is available through the Oracle Investments app, with no setup or spreadsheets.
Our perspective
We built Oracle because investors often have more information than they can use. A 13F is a good example: it is public, it is free, and it names some of the best-known investors in the world. Yet the filing cannot tell you why a position was taken, what it cost or whether it has since been sold.
That is why we start from the company, not the crowd. Our scores come from reported fundamentals, they follow set rules, and every input is visible, so you can see what drives a number instead of trusting a black box. A 13F tells you where to look. The fundamentals tell you whether to stay.
The lesson from Buffett, Munger and Lynch is not to copy what others hold. It is to understand what you own. Use 13Fs to find questions worth asking, and let the business answer them.
Matt
Frequently asked questions
Can I copy a hedge fund's 13F to pick stocks?
Not reliably. The filing shows long positions at one quarter end and arrives up to 45 days later, with no cost basis, no short positions and no reasoning. Use it to find companies to research, then judge them on their own fundamentals.
Who has to file a 13F?
Institutional investment managers that exercise investment discretion over at least $100 million in Section 13(f) securities, per the SEC. Individual investors and small advisers below that threshold do not file.
Where do I find 13F filings?
On the SEC's EDGAR system, which is free to use. Search for the manager by name, then open its 13F-HR filings and read the information table. Because the filings are electronic, every quarter is available to compare.
Does a 13F show everything a fund owns?
No. It shows qualifying long positions only. Short positions, cash, bonds, foreign shares, open-end mutual funds and private holdings are not included, and small positions may be omitted. The filing is most complete for managers that hold mainly U.S. stocks.
Sources
- SEC: Frequently Asked Questions About Form 13F
- Investor.gov: Form 13F glossary entry
- SEC: Form 13F instructions (SEC 1685)
- SEC EDGAR: sample 13F-HR/A filing
- SEC EDGAR: sample 13F information table
- SEC final rule amending Form 13F, effective January 3, 2023
- Dechert: 2026 reporting and compliance reminder