Operating leverage measures how sensitive a company's operating income is to changes in sales, driven entirely by the mix of fixed and variable costs. A firm with high fixed costs sees operating income swing much harder than revenue does, in both directions. This single ratio, often called the Degree of Operating Leverage (DOL), explains why some businesses report explosive profit growth on modest sales gains, and why the same business can post brutal losses when sales dip.
TL;DR:
- Companies with high fixed costs can see operating income increase sharply with sales growth but face rapid losses if demand drops unexpectedly.
- The degree of operating leverage varies significantly across industries, with manufacturing and software firms often exhibiting high DOL, while retail and staffing have low DOL.
- A high DOL ratio amplifies both profit potential during expansion and risk during downturns, making accurate sales forecasting essential for high-DOL businesses.
- Operating leverage changes with sales volume, so regular recalculations are necessary to maintain an accurate risk assessment, especially near break-even points.
- Investors should pair DOL figures with margin stability and balance sheet strength, as the ratio alone does not indicate business quality or long-term sustainability.
Table of Contents
- What Is Operating Leverage and Why Does It Matter?
- How Do You Calculate Operating Leverage?
- Worked Examples: High vs. Low Operating Leverage
- Is High Operating Leverage Good or Bad?
- Operating Leverage vs. Financial Leverage: What's the Difference?
- What Are Typical Operating Leverage Levels by Industry?
- How Do You Calculate DOL From Financial Statements?
- How Investors Use Operating Leverage in Stock Analysis
- Where Does DOL Calculation Go Wrong?
- Where Did the Concept of Operating Leverage Come From?
- How Should Operating Leverage Shape Business Decisions?
- How Do You Run Sensitivity Analysis With Operating Leverage?
- How Does Sales Volume Actually Move Profits Through Operating Leverage?
- Which Companies Show High vs. Low Operating Leverage in Practice?
- What Actually Matters When You Read a DOL Number
- Screen for Operating Leverage Risk With Oracle Investments
- Sources
- FAQ
What Is Operating Leverage and Why Does It Matter?
Operating leverage comes down to one structural fact: some costs move with sales, and some don't. Rent, equipment depreciation, and salaried staff stay flat whether a company sells 10,000 units or 100,000. Materials, sales commissions, and shipping costs rise and fall with volume. The ratio between those two cost types determines how much operating income reacts to a change in revenue.
Fixed costs are the anchor. A factory lease of $50,000 a month doesn't change if production doubles. Variable costs scale with output, like raw materials or piece-rate labor. The gap between revenue and variable costs is the contribution margin, and that margin is what pays down fixed costs before anything becomes profit.
Here's the mechanic that makes operating leverage matter:
- Once fixed costs are covered, every additional dollar of contribution margin drops straight to operating income.
- A company with mostly fixed costs needs fewer incremental sales to see operating income jump sharply.
- The same structure works against the company when sales fall, since fixed costs don't shrink to match.
This is why First Round Review's explainer on operating leverage frames it as a double-edged tool: it magnifies profitability on the way up and magnifies losses on the way down, particularly in capital-intensive businesses.
How Do You Calculate Operating Leverage?
There isn't one single operating leverage formula. Analysts use three, depending on what data is available.
- Contribution margin method: DOL = Contribution Margin ÷ Operating Income. Use this when you have an income statement broken into fixed and variable costs.
- Unit-based method: DOL = [Q × (P − V)] ÷ [Q × (P − V) − Fixed Costs], where Q is units sold, P is price per unit, and V is variable cost per unit. This works best for manufacturers with clean per-unit economics.
- Percent-change method: DOL = % Change in Operating Income ÷ % Change in Sales. This is the most practical version for outside analysts, since it only requires two years of reported financials.
All three formulas are standard reference points in Investopedia's operating leverage guide, and they should return roughly the same number when applied to the same period.
Statistic check: a DOL of 2 means a 1% increase in sales produces a 2% increase in operating income, based on the classic $40,000 contribution margin against $20,000 operating income example that shows up across Investopedia's calculations.
One edge case trips up a lot of people: when operating income is zero or negative, DOL becomes undefined or produces a nonsensical negative number. A company barely above break-even can show a wildly inflated DOL, not because its cost structure changed, but because the denominator is tiny. Always sanity-check DOL against the underlying dollar figures before trusting the ratio on its own.
Worked Examples: High vs. Low Operating Leverage
Numbers make this concrete faster than any formula description. Here's a high fixed cost manufacturer against a low fixed cost service business, using the same revenue base.
High operating leverage: a capital-intensive manufacturer
- Revenue: $1,000,000. Variable costs: $400,000. Contribution margin: $600,000.
- Fixed costs: $500,000. Operating income: $100,000.
- DOL = $600,000 ÷ $100,000 = 6.
- A 10% sales increase (to $1,100,000) lifts operating income by roughly 60%, to about $160,000, since variable costs and contribution margin scale proportionally while fixed costs stay put.
Low operating leverage: a staffing or retail business
- Revenue: $1,000,000. Variable costs: $800,000. Contribution margin: $200,000.
- Fixed costs: $100,000. Operating income: $100,000.
- DOL = $200,000 ÷ $100,000 = 2.
- The same 10% sales increase only lifts operating income by about 20%, to roughly $120,000.
Same starting operating income, same revenue growth, very different outcomes. That's the entire story of operating leverage in one comparison.
Break-even analysis explains why. Below that point, losses accumulate fast because fixed costs don't budge. Margin of safety, the cushion between current sales and break-even sales, shrinks fastest for high-DOL businesses when demand softens.
Pro Tip: DOL isn't a fixed personality trait of a company. It changes every time sales move, so recalculate it whenever you update a forecast rather than reusing last year's number.
Is High Operating Leverage Good or Bad?
Neither, by itself. High operating leverage is a magnifier, not a direction. It amplifies whatever is already happening to sales.
- During growth phases, high DOL businesses convert revenue gains into outsized operating income gains, which is why fast-growing software and manufacturing names often post profit growth well above revenue growth.
- During downturns, the same structure turns a modest sales decline into a much sharper income decline, since fixed costs keep accruing regardless of demand.
- Forecasting risk compounds with DOL. A 5% sales forecast error at DOL of 6 becomes a 30% operating income error, which makes high-DOL companies harder to model reliably.
- Managers with high fixed-cost structures can lower risk by outsourcing production, leasing instead of buying equipment, or shifting toward variable-cost labor arrangements.
- Pricing power matters more for high-DOL firms, since a company that can raise prices without losing volume protects its contribution margin when costs rise.
The practical takeaway: operating leverage tells you how much a sales forecast matters. Get the forecast right, and high DOL rewards you generously. Get it wrong, and the same ratio punishes you just as hard.
Operating Leverage vs. Financial Leverage: What's the Difference?
Operating leverage comes from cost structure. Financial leverage comes from capital structure, specifically how much debt a company carries relative to equity. They're separate risk sources that stack on top of each other.
- Financial leverage magnifies net income changes based on fixed interest obligations, the same way operating leverage magnifies operating income based on fixed operating costs.
- Degree of Total Leverage (DTL) combines both: DTL = DOL × DFL, giving you the total sensitivity of net income (or earnings per share) to a change in sales.
- Example: a company with DOL of 3 and DFL of 2 has a DTL of 6, meaning a 10% sales increase produces roughly a 60% increase in net income, and the same magnitude of decline if sales fall 10%.
This distinction matters for investors evaluating total firm risk, according to West Georgia University's leverage primer. A company can have low operating leverage but high financial leverage (a heavily indebted retailer), or the reverse (an all-equity semiconductor fab). Judging risk from either metric alone misses half the picture.
What Are Typical Operating Leverage Levels by Industry?
Operating leverage tracks cost structure, and cost structure tracks business model, so certain industries cluster predictably.
- Software, airlines, semiconductor fabrication, and heavy manufacturing tend to run high DOL, since upfront infrastructure and R&D dominate the cost base while incremental unit costs stay low.
- Retail, staffing, consulting, and many services tend to run low DOL, because labor and inventory costs scale directly with sales volume.
- Seasonal businesses can show misleadingly high DOL in slow quarters simply because fixed costs get spread over less revenue, not because the underlying structure changed.
- The only fair comparison is within-industry, ideally against percentile ranges for similar-sized peers, since comparing a software company's DOL to a grocery chain's tells you nothing useful.
How Do You Calculate DOL From Financial Statements?
Pulling DOL from a 10-K or annual report takes a few deliberate choices, since companies rarely label costs as "fixed" or "variable" directly.
- Start with net sales (revenue) from the income statement.
- Treat cost of goods sold (COGS) and direct sales costs as variable, since they scale with units sold.
- Treat depreciation and amortization (D&A) plus selling, general, and administrative expenses (SG&A) as a reasonable proxy for fixed costs, a common shortcut used in academic work.
- Compute contribution margin as revenue minus variable costs, then operating income as contribution margin minus fixed costs.
- Divide contribution margin by operating income to get DOL.
Some empirical researchers scale fixed costs by the market value of assets rather than book value, which better matches theoretical models but makes the ratio sensitive to swings in stock price, according to a Cambridge working paper on operating leverage estimation. Book-value scaling is more stable but can understate leverage for asset-light, high-growth firms. For a full walkthrough of extracting the right line items, see this income statement analysis checklist.
Pro Tip: If a company doesn't break out COGS cleanly, use SG&A trends over three to five years as a rough fixed-cost baseline. Costs that barely move despite big revenue swings are your fixed layer.
How Investors Use Operating Leverage in Stock Analysis
Operating leverage isn't just an accounting exercise. It shapes how professional investors size risk and forecast earnings volatility.
- Research using fixed costs scaled by market value of assets (D&A plus SG&A) has found that operating-leverage measures can predict differences in stock returns across companies, according to an academic study on market-based operating leverage.
- Not every high-DOL company is riskier than it looks. Some firms have a natural "operating hedge," where variable costs move in ways that partially offset fixed-cost amplification, which research from MIT Sloan suggests can make the DOL-to-returns relationship less predictable than a simple linear story.
- Persistent margins matter as much as the DOL number itself. A company that has kept its contribution margin stable for years is a more reliable high-DOL bet than one with a single strong quarter.
- The scoring model evaluates profitability, valuation, and financial health side by side across a broad set of stocks, which makes it easier to spot a company carrying extreme operating leverage relative to its margin stability and balance sheet strength, rather than judging DOL in isolation. Pair that screen with a broader fundamental analysis checklist before drawing conclusions.
Where Does DOL Calculation Go Wrong?
DOL is a moving target, not a fixed company attribute, and that trips up a lot of otherwise careful analysts.
- DOL typically peaks just above the break-even point and declines as sales move further away from it, since fixed costs become a smaller share of the cost base at higher volume, per Varsity Tutors' explanation of DOL behavior.
- Using D&A plus SG&A as a fixed-cost proxy is a reasonable simplification, but it can misclassify costs that are actually semi-variable, like sales staff bonuses baked into SG&A.
- Scaling fixed costs by market value of assets aligns better with theory but introduces noise from stock price swings that have nothing to do with the underlying business.
- Always report DOL at a stated sales baseline, usually current fiscal year or trailing twelve months, and re-run the calculation under a 10% higher and lower sales scenario to see how much the ratio itself shifts.
Where Did the Concept of Operating Leverage Come From?
Operating leverage traces back to early 20th-century cost accounting, when factory owners first started separating fixed overhead (plant, machinery, salaried supervisors) from variable costs (raw materials, hourly wages) to understand break-even points. Break-even analysis itself emerged from manufacturing cost studies in the 1920s and 1930s, as industrial firms scaled up capital investment and needed a way to model how thin profit margins could turn negative fast if volume dropped.
The formal "leverage" terminology, borrowing the physics metaphor of a lever amplifying force, entered mainstream corporate finance textbooks by the mid-20th century, once financial leverage from debt financing was already a well-established concept. Pairing "operating" leverage with "financial" leverage gave analysts a cleaner way to separate two distinct sources of earnings volatility: cost structure and capital structure. That framing, distinguishing the two and multiplying them into Degree of Total Leverage, has held up as the standard treatment in corporate finance ever since, as laid out in West Georgia University's leverage primer.
What's changed more recently is the empirical side. Academic finance shifted from treating operating leverage as a purely descriptive accounting ratio toward testing whether it actually predicts stock returns, using market-value-scaled fixed-cost measures instead of simple book-value ratios. That shift matters for anyone using DOL today: the concept still comes from factory-floor cost accounting, but the tools for measuring it have gotten considerably more rigorous.
How Should Operating Leverage Shape Business Decisions?
Operating leverage isn't just something analysts calculate after the fact. It should shape decisions before a company commits capital, because the cost structure choice determines how forgiving or unforgiving future sales swings will be.
A company deciding between buying a $2 million production line or leasing capacity from a contract manufacturer is really deciding how much operating leverage it wants to carry. Buying locks in fixed costs and depreciation, raising DOL and the potential upside on volume growth. Leasing keeps costs variable, capping both the upside and the downside. Neither choice is automatically right. It depends on how confident management is in demand forecasts.
Pricing strategy connects directly to this. A high-DOL company facing a sales slowdown has less room to cut prices to defend volume, since it needs every unit's contribution margin to cover fixed costs already locked in. A low-DOL competitor can discount more aggressively because its cost base flexes down with lower volume anyway.
Expansion planning is another place this shows up. Companies contemplating a new facility or major headcount increase are effectively choosing to raise their DOL. That decision should be paired with a realistic sales growth range, not a single-point forecast, since the entire value of the expansion depends on hitting volume that clears the new, higher break-even point. Boards and CFOs increasingly build operating leverage explicitly into capital allocation reviews for exactly this reason: it converts a spending decision into a risk decision.

How Do You Run Sensitivity Analysis With Operating Leverage?
Because DOL changes with the sales level, a single DOL calculation tells you the sensitivity at one point, not the full range of possible outcomes. Sensitivity analysis fixes that by testing multiple sales scenarios against the same cost structure.
Start with a base case using current-year or trailing-twelve-month sales and costs. Recalculate operating income and DOL under all three. What usually shows up is that DOL itself is highest in the downside case, closest to break-even, and lowest in the upside case, since fixed costs become a smaller share of the cost base as volume rises.

This is where scenario planning earns its keep for both managers and investors. An investor modeling a stock can stress-test earnings estimates across a realistic sales range instead of trusting a single forecast, which matters most for companies sitting close to their break-even point, where a small miss on sales assumptions produces an outsized miss on earnings.
How Does Sales Volume Actually Move Profits Through Operating Leverage?
The mechanism is simpler than it sounds once you isolate it: every unit sold beyond break-even contributes its full contribution margin straight to operating income, because fixed costs are already covered. Every unit sold below break-even subtracts that same margin from an already-negative operating result.
That's why operating income growth outpaces revenue growth for high-DOL companies on the way up, and why it falls faster on the way down.
The practical consequence is that sales volume forecasts deserve more scrutiny at companies with high operating leverage than the revenue number alone suggests. Analysts who apply the same margin-of-error assumptions to both are underestimating risk at the high-DOL company and overestimating it at the low-DOL one.
Which Companies Show High vs. Low Operating Leverage in Practice?
Business model explains almost all of the variation in real-world operating leverage, and a few patterns show up consistently across sectors.
Airlines sit near the top of the high-DOL spectrum. Fleet ownership, leases, airport gate contracts, and crew staffing are largely fixed regardless of how full the planes are, which is why a few percentage points of load-factor decline can wipe out a quarter's profit, and why a strong travel season can produce outsized income gains.
Software companies with high upfront engineering and infrastructure costs but near-zero marginal cost per additional customer sit at the extreme end of operating leverage, which is part of why profitable software businesses can post operating margin expansion that outpaces revenue growth for years running.
On the low end, staffing agencies and many consulting firms carry operating leverage close to 1, since labor cost scales almost one-for-one with billable revenue. Grocery retail sits low as well, since inventory and store labor flex with sales volume, which is one reason grocery margins stay thin but comparatively stable through economic cycles compared to capital-intensive manufacturing.
What Actually Matters When You Read a DOL Number
The single most overlooked point about operating leverage is that the number by itself says nothing about quality. A DOL of 5 on a company with a durable competitive moat and pricing power is a very different bet than a DOL of 5 on a commodity producer with no control over its selling price. The ratio tells you how much a sales swing gets amplified. It says nothing about whether that swing is likely to be up or down.
For investors: don't screen for high or low DOL in isolation. Pair it with margin stability and balance sheet strength before drawing conclusions. For managers: treat every fixed-cost commitment as a leverage decision, not just a spending decision, and stress-test it against a realistic downside case before signing the lease or buying the equipment.
— Matt
Screen for Operating Leverage Risk With Oracle Investments
Calculating DOL by hand for one company is manageable. Doing it consistently across a watchlist of twenty stocks, then cross-checking each against profitability and valuation, is where most individual investors give up. This app was built to close that gap: it scores a wide range of stocks on profitability, valuation, and financial health using transparent, rule-based inputs, not a black-box model, so you can see exactly why a company's fundamentals look strong or shaky before you factor in its cost structure.
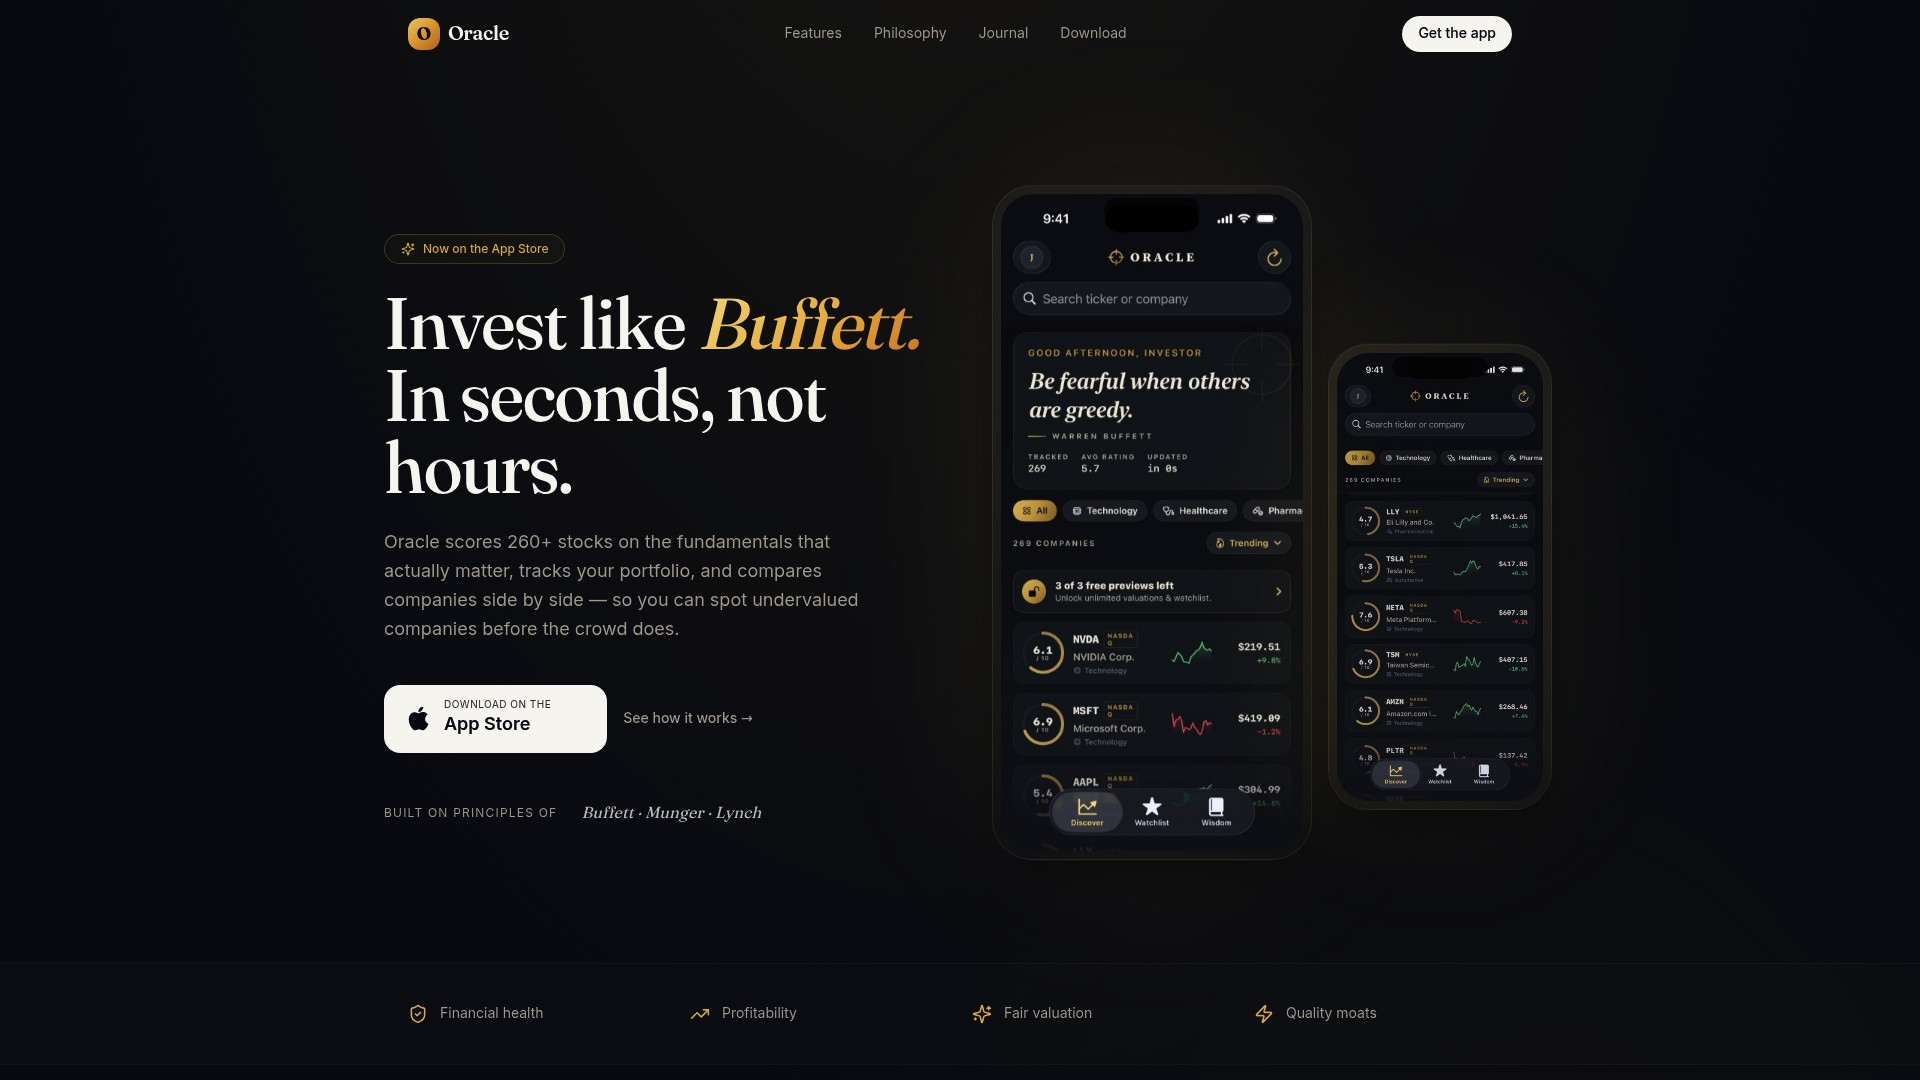
The app's side-by-side comparison feature lets you line up a high-fixed-cost manufacturer against a low-fixed-cost competitor and see how their margin trends and financial health scores diverge, without building a spreadsheet from scratch. It also folds in investing principles from Warren Buffett, Charlie Munger, and Peter Lynch, so you're applying operating leverage analysis alongside the same discipline value investors have used for decades. Pair it with real-time portfolio tracking to watch how margin-sensitive holdings react as earnings season unfolds. Check current features and start building your own comparisons with the Premium Annual subscription.
Sources
For deeper detail on the formulas and examples covered here, see Investopedia's operating leverage guide and First Round Review's operating leverage glossary entry. For the academic measurement approach and predictive research, review the market operating leverage study. For a practical break-even primer, see this small business break-even guide.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- Investopedia — Operating leverage
- First Round Review — Operating leverage (glossary)
- West Georgia University — Leverage primer
- Academic paper on operating leverage (market operating leverage measure)
FAQ
What Is Meant by Operating Leverage?
Operating leverage measures how much a company's operating income changes in response to a change in sales, driven by the proportion of fixed versus variable costs in its cost structure. A company with mostly fixed costs has high operating leverage, meaning small sales changes produce large operating income swings, as explained in Investopedia's overview.
Is High Operating Leverage Good?
High operating leverage is good when sales are growing, since it magnifies profit gains, but it becomes a liability when sales decline, since fixed costs still have to be paid. Whether it's "good" depends entirely on the reliability of the sales forecast behind it, according to First Round Review's analysis.
What Is a Good Operating Leverage Ratio?
There's no universal "good" DOL, since it depends heavily on industry and business model; capital-intensive sectors like manufacturing and airlines naturally run higher DOL than service businesses. The better question is whether a company's DOL is stable and well understood relative to its industry peers, rather than chasing a specific target number.
How Do I Calculate Operating Leverage?
The most common method divides contribution margin (revenue minus variable costs) by operating income, giving you the DOL ratio directly from the income statement. You can also use the percent-change method, dividing the percent change in operating income by the percent change in sales across two periods, both of which are detailed in Investopedia's formula breakdown.
Does Oracle Investments Track Operating Leverage Directly?
Oracleinvestments scores companies on profitability, valuation, and financial health rather than publishing a standalone DOL figure, but its side-by-side comparison tools make it easier to spot margin volatility patterns consistent with high operating leverage. Combining that screen with the calculation steps in this article gives you a fuller picture than either approach alone.